Connect with us

Business

Bank of England plans new site to expand Leeds office

Published

on

Business Live

The Bank of England has secured Capitol House in Leeds to replace Yorkshire House, with a move planned for late 2028. It previously announced plans for at least 500 staff in the city by 2027.

The Bank of England

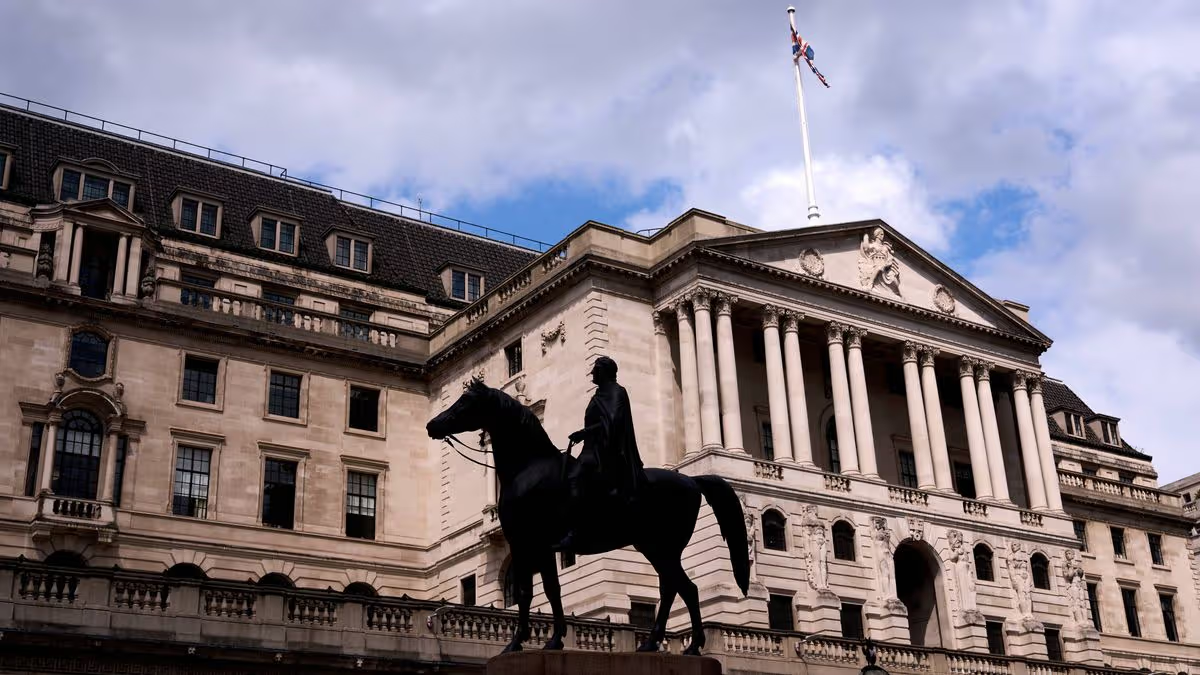
The Bank of England offices at Threadneedle street in London.(Image: PA)

The Bank of England is preparing to launch a new office in Leeds as it continues to strengthen its foothold in the city.

Britain’s central bank has secured a long-term base at Capitol House in Bond Court, Leeds, which it says will accommodate its “growing headcount” in the city and ultimately replace its existing premises at Yorkshire House.

Advertisement

The Bank currently employs just under 300 staff in Leeds, having previously announced ambitions to grow its West Yorkshire workforce to at least 500 by 2027. The relocation to Capitol House is scheduled for late 2028.

Bank governor Andrew Bailey said: “The Bank’s new office in Leeds is an important milestone in our long-term commitment to the city. We have seen first-hand the value of the exceptional talent, expertise and fresh perspectives that Leeds and the wider region offer.

“Moving to Capitol House strengthens our presence across the UK and helps ensure the Bank better reflects and represents the people, businesses and communities we serve.”

Tracy Brabin, mayor of West Yorkshire, said the move would support efforts to drive growth across the regions.

Advertisement

She said: “The Bank of England putting down even deeper roots in Leeds is a powerful endorsement of our Northern Square Mile, and signals a national belief in our region’s economic future.”

She added: “The Bank establishing a permanent base in Leeds won’t just be good for the people of West Yorkshire – it will help ensure that the future of our national economy is shaped by voices from across our regions and nations.

“That is how we’ll deliver good growth in every postcode and build a stronger, brighter UK economy that works for all.”

The enhanced presence in Leeds also forms part of a wider restructuring of its property portfolio, known as its location strategy programme, which will see it renovate its historic Threadneedle Street headquarters and reportedly close the neighbouring Moorgate site.

Advertisement

The Bank stated the Threadneedle Street renovation is “designed to allow consolidation of the Bank’s property footprint in London by end-2028”.

The Bank originally opened a Leeds branch in 1827 under Thomas Bischoff, who served as the Bank’s first agent.

It operates 12 agencies throughout the UK, working from a network of offices in Belfast, Birmingham, Bristol, Cardiff, Fareham, Glasgow, Leeds, Manchester, Newcastle and Nottingham.

Advertisement
Continue Reading
Click to comment

You must be logged in to post a comment Login

Leave a Reply

Business

Is switching really worth it?

Published

on

Is switching really worth it?

Alongside the familiar national providers, a growing number of smaller network builders, often called alt-nets, are offering their own full fibre broadband deals. The result is a choice that can feel welcome, but also harder to read at a glance.

The basic question is simple: do the smaller providers actually offer something better, or do they just look better on paper? For households comparing monthly bills, speeds and contract terms, that question matters more than brand recognition. A cheaper headline price means little if service falls short when it is needed most.

Big telecom companies still have the advantage of scale. Their networks cover far more homes, their customer service systems are more established, and their packages are easier to find.

Free newsletters
Advertisement

The stories that matter to UK business, straight to your inbox.

Advertisement

Alt-nets, meanwhile, tend to focus on specific areas and promise a more direct route to full fibre, which can be appealing for people stuck on slower lines.

What alt-nets usually bring to the table

Alt-net is a broad label, but the common thread is that these companies build their own fibre infrastructure rather than relying entirely on legacy copper networks. That matters because a full fibre connection can deliver faster downloads, lower latency and better performance when several people are online at once. In practical terms, that can make video calls steadier and gaming less frustrating.

The appeal is not only technical. Smaller operators often market themselves as more responsive, with shorter support chains and fewer layers between the customer and the network owner. For someone who has spent weeks chasing a fault report, that promise can sound refreshing. Does it always play out that way? Not necessarily, but the idea has traction for a reason.

Alt-nets also tend to enter areas where competition has been thin. That can put pressure on the larger providers to improve pricing or speed up upgrades. In a street-by-street market, one new network can change the conversation quickly, especially if neighbours start asking why they are still paying for older technology.

Advertisement

Where big telecom still has the edge

Large telecom brands are not standing still. They usually have broader coverage, more bundles and clearer options for households that want broadband, mobile and TV on one bill. For many customers, that convenience still outweighs the appeal of a newer name.

There is also a practical point about reliability of rollout. A national operator may already have fibre available in one form or another across a large part of the country, while an alt-net may only serve selected streets. If your postcode is covered, switching looks easy. If not, the choice is made for you before you even start comparing tariffs.

Customer experience is more mixed than either side would like to admit. Large providers can be slow to resolve complaints, but they also have bigger support structures and more mature escalation processes. Smaller networks may feel more personal, yet a local fault can be just as frustrating if the team is under-resourced or still scaling up.

The real costs are not always in the headline price

When people compare broadband offers, they often focus on the monthly fee. That is understandable, but it misses a few details that matter over the life of the contract. Installation charges, contract length, in-contract rises and router quality can all affect the total cost.

Advertisement

Some alt-nets attract attention with sharp introductory pricing. Once the promotion ends, the bill can move closer to what larger providers charge. Big telecom firms do the same thing, though they may also offer other services that soften the blow for families already buying from the same group. The headline number is only the opening line.

Another factor is flexibility. A shorter contract may suit renters or people expecting to move. A longer one might be fine for homeowners who want certainty and do not plan to change addresses soon. The best full fibre broadband deal is not necessarily the fastest or the cheapest, but the one that fits the household’s habits.

Who gains most from switching?

Households still on older broadband are the most obvious winners if an alt-net reaches their street. Full fibre can be a clear improvement, especially for homes with several users streaming, downloading and working at the same time. A flat that shares one connection between remote workers and students will feel the difference quickly.

Some customers also switch for service reasons rather than speed alone. If a provider has been slow to fix faults or unclear about price rises, the temptation to move is strong. Brand loyalty weakens fast when support calls keep ending in the same scripted answers.

Advertisement

For others, staying put may be the better move. If your current package already performs well and the switching process would bring early termination fees or installation disruption, the gain may be too small to justify the hassle. Not every household needs to chase the newest network just because it exists.

What readers should check before deciding

A careful comparison should start with coverage, because availability determines everything else. Then comes the upload speed, which can be overlooked when consumers only look at download figures. Anyone who sends large files, backs up photos or works from home will want that number to be realistic.

It also helps to read the small print on price rises and exit fees. Promotions can look attractive until the second year arrives. One useful question is whether the provider has a genuine track

record in the area, rather than a launch promise that sounds good but has not yet been tested at scale.

Advertisement

That is where the alt-net versus big telecom debate becomes more grounded. The decision is not about ideology or brand preference. It comes down to whether the local network, the contract terms and the support setup match the way people actually use the internet at home.

Why the choice is getting sharper

Competition in broadband is no longer just about faster speeds. It is about who can deliver a stable service at a fair price, with enough clarity that customers know what they are signing up for. Smaller networks have pushed that issue onto the table, and larger firms have had to respond.

The market is likely to stay uneven for a while. Some areas will have several fibre options, while others will still depend on a single dominant provider. For readers trying to decide whether switching is worth it, the answer will depend less on the logo on the router and more on what happens after the engineer leaves the driveway.

Advertisement

Continue Reading

Business

Nutanix: Profit Taking Is Appropriate Here (Downgrade)

Published

on

Server racks in server room data center - Cloud Computing, Artificial Intelligence, Database Concept - 3d illustration

Nutanix: Profit Taking Is Appropriate Here (Downgrade)

Continue Reading

Business

Critics say California got too little in deal to let Paramount buy Warner Bros

Published

on


Critics say California got too little in deal to let Paramount buy Warner Bros

Continue Reading

Business

Raytheon wins $34 million contract for V-22 software support

Published

on


Raytheon wins $34 million contract for V-22 software support

Continue Reading

Business

Endava stock tumbles 10% on CFO leave, accounting probe

Published

on


Endava stock tumbles 10% on CFO leave, accounting probe

Continue Reading

Business

GE Aerospace declares $0.47 quarterly dividend

Published

on


GE Aerospace declares $0.47 quarterly dividend

Continue Reading

Business

founder Josh Payne in line for $350m payout

Published

on

founder Josh Payne in line for $350m payout

Josh Payne, the 32-year-old founder of British data centre start-up Nscale, is in line for performance-related share payments worth up to $350m (£260m) after the company floats in New York, according to its prospectus.

The document, released on Friday night, said the package was designed to ensure Payne’s “continued long-term alignment” with shareholders. Nscale is targeting a valuation of about $35bn (£26bn) as demand grows for the computing power that underpins artificial intelligence.

How the award is structured

The potential share-based payments account for about 2.5 per cent of Nscale’s share capital, according to the prospectus. They will vest in stages between 2028 and 2032 if the company hits various targets.

Free newsletters
Advertisement

The stories that matter to UK business, straight to your inbox.

Advertisement

The company said 40 per cent of the shares will be linked to stock price targets and a further 40 per cent to the deployment of computing capacity. The remaining 20 per cent relates to “other operational targets”.
The prospectus said: “Our compensation committee and board of directors believe that Mr Payne’s continued leadership is critical to our ability to successfully execute our long-term strategy, capitalise on emerging market opportunities and create substantial shareholder value.”

Payne’s compensation in 2025, including share awards, was £17.2m. That was just below the £17.7m paid to Pascal Soriot at AstraZeneca, the highest in the FTSE 100.

Payne was born and raised in New South Wales, on Australia’s east coast. He worked in a coal mine and as a manual labourer before setting up a bitcoin-focused company, Arkon Mining, in 2019. Nscale was spun out of that business, since renamed Arkon Energy, in 2024.

Advertisement

Revenue, losses and contracts

The company has grown on the back of contracts with US technology groups and backing from industry figures. It was valued at about $14.6bn in a funding round in March led by Aker, the Norwegian industrial investment company, and 8090 Industries, a US investment firm.

Nvidia also took part in that round. The chipmaker has invested more than $2bn in Nscale, including $1bn in convertible notes, and Jensen Huang, Nvidia’s chief executive, has described the company as a “national champion for the UK”. Nscale is a major customer of Nvidia and also has a $1.2bn contract to supply it with computing capacity.

The prospectus showed revenue of $140.6m in the six months to June, up from $10.4m a year earlier. Net losses widened over the same period from $368.9m to $1.02bn.

Nscale said it expects losses to continue because of the “substantial upfront capital expenditure” needed to expand its data centre capacity and buy the hardware required to deliver its contracts.

Advertisement

At the end of August, the company said it had 55 megawatts of active capacity: 7MW from its own data centres and 48MW rented from third parties. That capacity is tied to $2.6bn in contracted revenue. A further 1.3 gigawatts is in the pipeline, tied to $101bn of contracts that have not yet started. One megawatt can support about 600 to 1,000 homes.

Nscale has signed a six-year contract worth $45bn with Anthropic, under which the AI lab will lease capacity at Nscale’s site in West Virginia from next year. It has also signed long-term agreements with Microsoft running until 2033 and worth $44bn, building on an earlier arrangement to supply the Microsoft UK supercomputer project.

The company, which raised £750m last year for its UK data centre plans, claims to have “line of sight” to 10GW of capacity.

The prospectus also set out risks. It said: “Our limited operating history, including our limited history of selling our AI cloud infrastructure offering, the dynamic and rapidly evolving market in which we sell our platform, and the concentration of our revenue from a limited number of customers, as well as numerous other factors beyond our control, may make it difficult to evaluate our current business, future prospects and other trends.”

Advertisement
Jamie Young
About the author

Jamie Young

Jamie Young is Senior Reporter at Business Matters, covering SME finance, employment law and Westminster policy since 2016. He has reported on every Budget and Autumn Statement since 2018, helped make sense of the ‘covid era’ and the bounce-back loan scheme from launch through the fraud investigations, and broke the magazine’s coverage of the 2024 late-payment reforms. He joined Business Matters straight from completing his BA in Administration from Exeter University and is NCTJ-qualified. Reach him at jyoung@cbmeg.co.uk

Advertisement

Continue Reading

Business

2027 Social Security COLA projected at 3.6% by AARP after CPI data

Published

on

Social Security SSI benefits to be paid early due to weekend calendar quirk

Social Security beneficiaries are expected to see a larger cost-of-living adjustment (COLA) in 2027 than they received for this year, according to new estimates that follow the release of August inflation data.

By law, the annual Social Security COLA is calculated using the Bureau of Labor Statistics’ consumer price index (CPI) inflation data for the months of July, August and September based on a variant of the dataset known as CPI-W. The COLA boosts beneficiaries’ payments to account for a rise in the cost of living, and the COLA for 2026 amounted to a 2.8% increase.

Advertisement

The BLS released the August CPI inflation data that showed consumer prices were up 3.4% from a year ago, while the CPI-W was up 3.5% over the last year.

Several groups have released estimates for the 2027 COLA based on the data from the last two months and estimates for September’s data, which have the COLA landing in a range from 3.4% to 3.6%.

CONSUMER PRICES REMAIN ELEVATED IN AUGUST AHEAD OF FED’S NEXT MEETING

Social Security card and US Capitol building

Social Security’s annual COLA will be officially announced after the release of the September CPI inflation data next month. (Getty Images/stock)

The nonpartisan Committee for a Responsible Federal Budget (CRFB) estimated that based on the latest data, the 2027 COLA will be 3.4%.

Advertisement

AARP projected that the 2027 COLA will be 3.6%, based on its analysis of recent inflation readings and projections for the coming weeks.

Rich Johnson, vice president of financial security at the AARP Public Policy Institute, noted that many older adults rely on Social Security for the bulk of their income and that the group’s forecast aims to help them plan based on how the COLA may affect their finances.

“Family budgets have been under increasing pressure because of rising prices. The sooner that we can give them reliable information as to how much their benefits might [increase next year], the sooner they can start planning,” Johnson said.

ONE TYPE OF SOCIAL SECURITY ADJUSTMENT COULD CUT THE 75-YEAR SHORTFALL IN HALF

Advertisement

Johnson said that the AARP’s estimate incorporates the Federal Reserve Bank of Cleveland’s inflation projections for September and that while those figures aren’t “set in stone,” the data helps compile the estimate.

“With only one month of inflation data to go until the 2027 COLA is finalized, there’s less uncertainty about what that increase will be,” he added. “Unless prices change dramatically in September, we’re confident that the COLA will be in the mid-3% range.”

The Senior Citizens League predicted the 2027 COLA will be 3.5% following the release of the August CPI inflation data, down slightly from its estimate of 3.6% the prior month. A 3.5% COLA would increase average benefit checks by $67.90 and would boost the monthly benefit from $1,940.08 to $2,007.98, TSCL reported.

AMERICA’S $40T NATIONAL DEBT IS ‘STEALING FROM OUR NEXT GENERATION,’ ECONOMIST WARNS

Advertisement
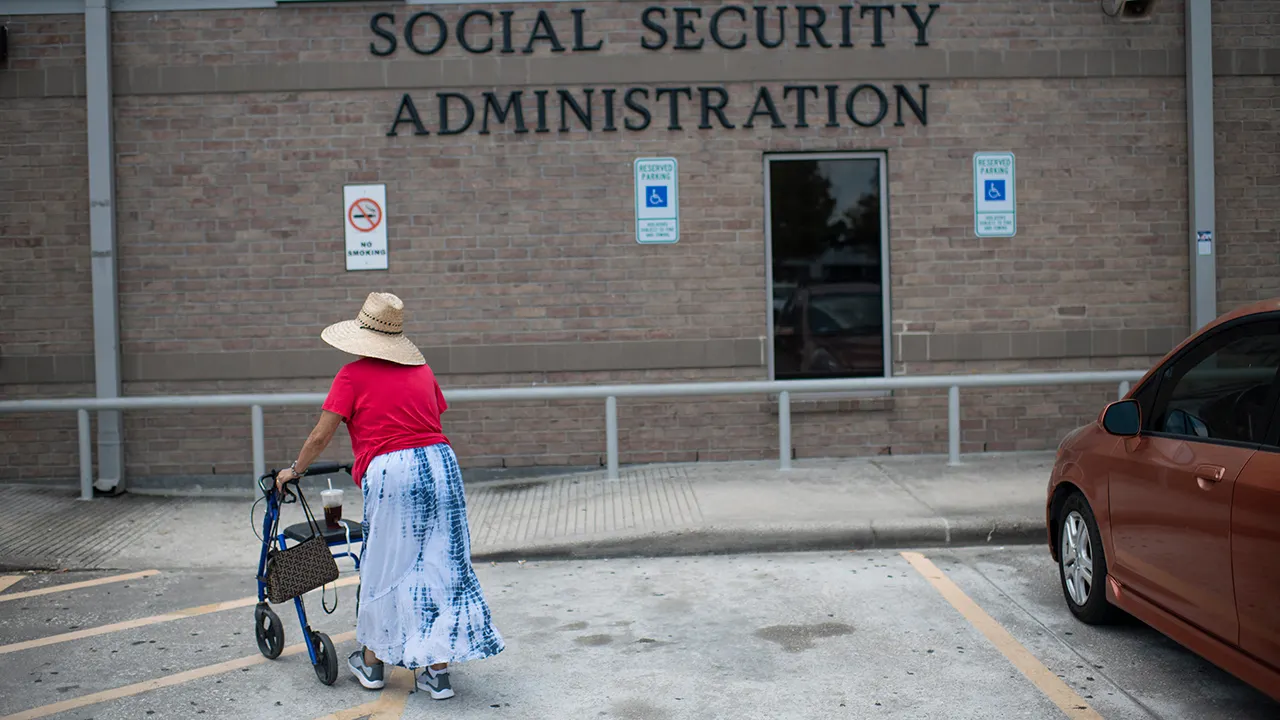
Woman with walker heads into Houston Social Security office

Social Security’s COLA is expected to be larger in 2027 than in 2026 due to higher inflation. (Mark Felix/The Washington Post)

“The biggest thing we’re watching with the COLA announcement coming are short-term shocks to the economy that push inflation way up or down in the next 30 days,” said TSCL executive director Shannon Benton.

“No matter if the COLA announcement comes in slightly higher or slightly lower than our prediction, seniors will probably end up disappointed in the long run. The reality is that older Americans allocate their budgets differently than people still in the workforce, so inflation hits them differently. The CPI-W captures the experience of urban wage earners, which doesn’t represent the average senior’s budget,” Benton added.

GET FOX BUSINESS ON THE GO BY CLICKING HERE

The final piece of data for the 2027 COLA will be released on Oct. 14, when the BLS releases the September CPI inflation data.

Advertisement
Continue Reading

Business

Stifel initiates Rush Street Interactive stock with buy rating

Published

on


Stifel initiates Rush Street Interactive stock with buy rating

Continue Reading

Business

Ducommun: Why I See Upside Despite Aerospace Multiple Pressure (NYSE:DCO)

Published

on

Delta 737 Mt Hood.

This article was written by

Dhierin-Perkash Bechai is an aerospace, defense and airline analyst.
Dhierin runs the investing group The Aerospace Forum, whose goal is to discover investment opportunities in the aerospace, defense and airline industry. With a background in aerospace engineering, he provides analysis of a complex industry with significant growth prospects, and offers context to developments as they occur, describing how they might affect investment theses. His investing ideas are driven by data informed analysis. The investing group also provides direct access to data analytics monitors.
Learn more.

Analyst’s Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.

Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.

Advertisement
Continue Reading

Trending

Copyright © 2025