Connect with us

Business

Barclays starts bullish coverage on Hill & Smith on U.S. infrastructure demand

Published

on

Continue Reading
Click to comment

You must be logged in to post a comment Login

Leave a Reply

Business

EWY: The Bubble Faded, But Korea Still Needs New Buyers

Published

on

South Korea semiconductor chip trade tariff. 3d rendering

EWY: The Bubble Faded, But Korea Still Needs New Buyers

Continue Reading

Business

Rates mostly higher following the Fed

Published

on

Rates mostly higher following the Fed

According to the Zillow lender marketplace, mortgage rates are mostly higher following the first Fed rate increase in three years.

The average 30-year fixed rate today, Friday, September 18, 2026, is 7.05%, up 4 basis points since yesterday. The 15-year fixed loan is currently at 6.43%, 1 basis point lower than yesterday. The 5/1 ARM is 7.16%, up 6 basis points from Thursday.

Read more: Weekly survey of mortgage lenders with the lowest rates: Breaking the 7% barrier

Advertisement

Here are the current purchase rates, according to the latest Zillow data, for Friday, September 18, 2026:

  • 30-year fixed: 7.05%

  • 20-year fixed: 6.92%

  • 15-year fixed: 6.43%

  • 5/1 ARM: 7.14%

  • 7/1 ARM: 6.66%

  • 30-year VA: 6.46%

  • 15-year VA: 6.00%

  • 5/1 VA: 6.34%

Remember, these are national averages and have been rounded to the nearest hundredth. 

These are the latest refinance rates, according to the latest Zillow data, for Friday, September 18, 2026:

  • 30-year fixed: 7.07%

  • 20-year fixed: 6.96%

  • 15-year fixed: 6.46%

  • 5/1 ARM: 7.13%

  • 7/1 ARM: 6.70%

  • 30-year VA: 6.64%

  • 15-year VA: 6.73%

  • 5/1 VA: 5.86%

Again, the numbers provided are national averages rounded to the nearest hundredth. Mortgage refinance rates are often higher than rates when you buy a house, although that’s not always the case.

Advertisement

Learn more: Dig deeper into the 7 home refinance options

Your mortgage rate plays a large role in how much your monthly payment will be. Use this mortgage calculator to see how your mortgage amount, rate, and term length will impact your monthly payments:

You can bookmark the Yahoo Finance mortgage payment calculator and keep it handy for future use, as you shop for homes and the best mortgage lenders.

A mortgage interest rate is a fee for borrowing money from your lender, expressed as a percentage. You can choose from two types of rates: fixed or adjustable.

A fixed-rate mortgage locks in your rate for the entire life of your loan. For example, if you obtain a 30-year mortgage with a 6% interest rate, your rate will remain at 6% for the entire 30-year term unless you refinance or sell.

Advertisement

An adjustable-rate mortgage locks in your rate for a predetermined period and then adjusts it periodically. Let’s say you get a 7/1 ARM with an introductory rate of 6%. Your rate would be 6% for the first seven years, then the rate would increase or decrease once per year for the last 23 years of your term. Whether your rate goes up or down depends on several factors, such as the economy and housing market.

At the beginning of your mortgage term, most of your monthly payment goes toward interest. Your monthly payment toward mortgage principal and interest stays the same throughout the years. However, less and less of your payment goes toward interest, and more goes toward the mortgage principal or the amount you originally borrowed.

Read more: Determine whether an adjustable-rate vs. fixed-rate mortgage is better for you

A 30-year fixed-rate mortgage is a good choice if you want a lower mortgage payment and the predictability that comes with having a fixed rate. Just know that your rate will be higher than if you choose a shorter term, and you will pay significantly more in interest over the years.

Advertisement

You may want to consider a 15-year fixed-rate mortgage if you aim to pay off your home loan quickly and save money on interest. These shorter terms come with lower interest rates, and since you’re cutting your repayment time in half, you’ll save a lot in interest in the long run. But you’ll need to be sure you can comfortably afford the higher monthly payments that come with 15-year terms.

Read more: Learn how to decide between a 15-year and 30-year fixed-rate mortgage

Typically, an adjustable-rate mortgage might be suitable if you plan to sell before the introductory rate period ends. Adjustable rates usually start lower than fixed rates, and then your rate will change after a predetermined amount of time. However, 5/1 and 7/1 ARM rates have been similar to (or even higher than) 30-year fixed rates recently. Before getting an ARM just for a lower rate, compare your rate options from term to term and lender to lender.

Rates are rising for the most part. The average 30-year fixed rate today, Friday, September 18, 2026, is 7.05%, up 4 basis points since yesterday. The 15-year fixed loan is currently at 6.43%, 1 basis point lower than yesterday. The 5/1 ARM is 7.16%, up 6 basis points from Thursday.

Advertisement

According to Freddie Mac, the average 30-year mortgage rate was 6.95% through Wednesday, up from 6.76% a week earlier. A year ago, the average 30-year mortgage rate was 6.26%.

According to the latest forecasts, the MBA expects the 30-year mortgage rate to average between 6.6% and 6.7% through the rest of 2026. Fannie Mae predicts a 30-year rate between 6.7% and 6.8% through the end of the year.

Mortgage rates are likely to remain little changed in 2027. The MBA forecasts 30-year fixed rates of 6.7% for all of 2027. Fannie Mae is predicting average rates will be between 6.7% and 6.8% throughout 2027. 

Advertisement
Continue Reading

Business

Up to 4.40% APY return available with a 2-year CD

Published

on

Up to 4.40% APY return available with a 2-year CD

If you’re looking for a secure place to store your savings, a certificate of deposit (CD) may be a great choice. These accounts often provide higher interest rates than traditional checking and savings accounts. However, CD rates can vary widely. Learn more about CD rates today and where to find high-yield CDs with the best rates available. Here is a look at some of the best CD rates available today from our verified partners:

Today’s CD rates vary quite a bit. In general, however, CD rates have been declining for quite some time due to the Fed’s decision to cut its benchmark rate three times in the latter part of 2024 and three times in 2025. Even so, with the Fed leaving rates unchanged so far in 2026, some banks are still offering competitive CD rates.

For institutions offering competitive rates, top rates reach about 4% APY. This is especially true for shorter terms of one year or less. 

Advertisement

Today, Friday, September 18, 2026, the highest CD rate is 4.40%, and it’s offered by Happen Bank on its 2-year CD.

Compare these rates to the national average as of August 2026 (the most recent data available from the FDIC):

Compared with today’s top CD rates, national averages are much lower. This highlights the importance of shopping around for the best CD rates before opening an account.

Online banks and neobanks are financial institutions that operate solely via the web. That means they have lower overhead costs than traditional brick-and-mortar banks. As a result, they’re able to pass those savings on to their customers in the form of higher interest rates on deposit accounts (including CDs) and lower fees. If you’re looking for the best CD rates available today, an online bank is a great place to start.

However, online banks aren’t the only financial institutions offering competitive CD rates. It’s also worth checking with credit unions. As not-for-profit financial cooperatives, credit unions return their profits to customers, who are also member-owners. Although many credit unions have strict membership requirements that are limited to those who belong to certain associations or work or live in certain areas, there are also several credit unions that just about anyone can join.

Whether or not you should put your money in a CD depends on your savings goals. CDs are considered a safe and stable savings vehicle — they don’t lose money (in most cases), are backed by federal insurance, and allow you to lock in today’s best rates.

Advertisement

However, there are some drawbacks to consider. First, you must keep your money on deposit for the full term; otherwise, you’ll be subject to an early withdrawal penalty. If you want flexible access to your funds, a high-yield savings account or money market account might be a better choice.

Additionally, although today’s CD rates are high by historical standards, they don’t match the returns you could achieve by investing your money in the market. If you’re saving for a long-term goal such as retirement, a CD won’t provide the growth you need to reach your savings goal within a reasonable time frame.

Read more: Short- or long-term CD: Which is best for you?

Advertisement
Continue Reading

Business

Journey Energy: Eventually Quality Will Matter

Published

on

Bonterra Energy: Charlie Lake Is The New Core Area

Journey Energy: Eventually Quality Will Matter

Continue Reading

Business

U.S. Markets Sell Off After Fed’s Warsh Says Inflation Is Still ‘Too High’

Published

on

U.S. Markets Sell Off After Fed’s Warsh Says Inflation Is Still ‘Too High’

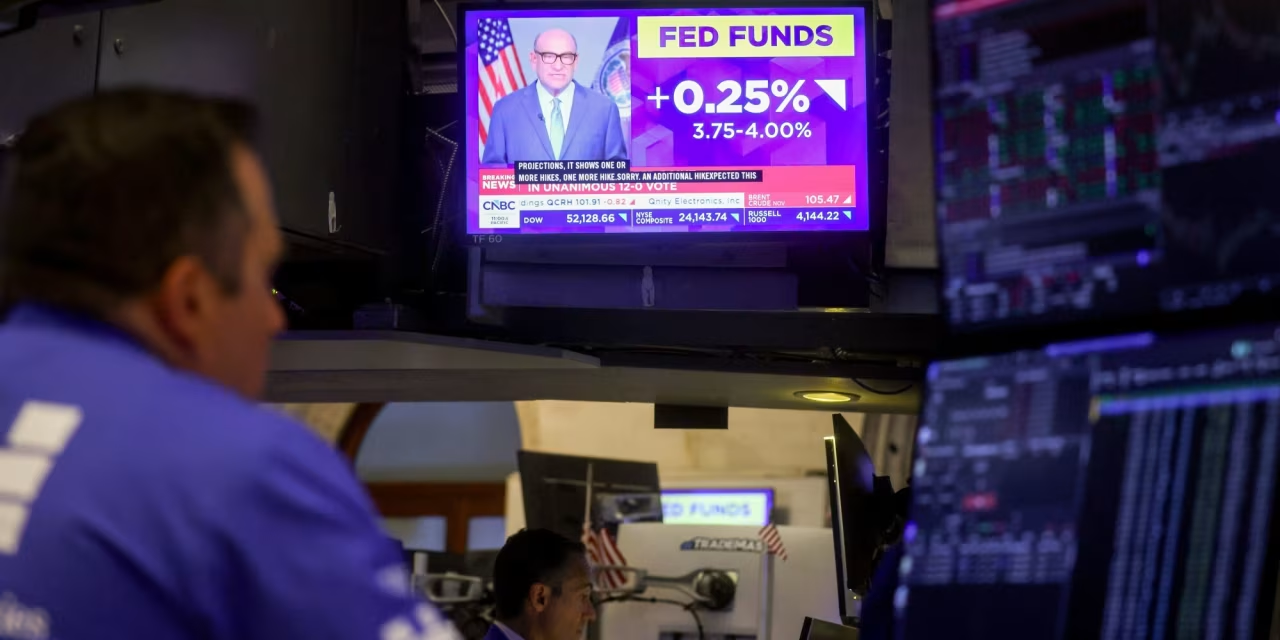
Federal Reserve Chairman Kevin Warsh made it clear inflation is still a problem. Wall Street was left wondering how far the Fed will go to address it. 

Stocks slumped and the 10-year Treasury yield settled above 5% for the first time since July 2007 after Warsh struck a decidedly hawkish tone in remarks following the central bank’s decision to raise interest rates for the first time in three years.

“Inflation is too high and has been for too long,” Warsh said in remarks to reporters on Wednesday afternoon. He later added: “Today’s action starts to show that we’re serious about this.” 

Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8

Advertisement
Continue Reading

Business

Bruce victims on their own as State seeks to drop prosecution

Published

on

Bruce victims on their own as State seeks to drop prosecution

Yes. Corporate subscriptions are available for teams and organisations, with discounted rates as user numbers increase. Pricing starts from $1,625 + GST per user.
Get in touch
to discuss the right option for your organisation.

Business News subscriptions are used by executives, investors, consultants and professionals who need to stay informed and make better decisions about the WA market. When you subscribe you’ll get

  • Unlimited access to WA’s most trusted business journalism
  • Data & Insights — detailed profiles of WA companies, people, projects and deals
  • MyBN — a personalised feed based on the companies, people and sectors you follow
  • Special publications and industry reports
  • Daily and weekly email newsletters

Data & Insights is a research tool built specifically for the WA market. It draws on more than 30 years of Business News reporting, updated regularly to reflect what’s happening now. Use it to:

  • Look up detailed profiles of WA companies, including financials, directors and ownership
  • Find decision-makers and track their career movements
  • Research live and completed projects across WA industries
  • Monitor deals, appointments and market activity
  • Access industry rankings and league tables

Data & Insights is updated daily by our dedicated research team, which uses the latest announcements, ASX filings and editorial coverage to keep our person, company, list and project records up to date.

Business News welcome all opportunities to make our dataset accurate, complete and current, so if you have an update request, please email the team at
general@businessnews.com.au, and we’d be happy to assist.

Advertisement

MyBN
is part of every subscription. It’s your personalised view of Business News. You can follow the companies, people, sectors and projects that matter to you, and get a news feed and alerts tailored to your interests. You can save articles to read later and retain only what you need.

Only subscribers have full access to all content on the Business News website.

Advertisement

If staying informed about the WA economy is part of your job, and/or you’re looking for networking opportunities in WA, Business News is built for you.

Business News subscribers are:

  • Executives and directors tracking competitors, clients and market movements
  • Investors and advisers researching companies, deals and industry trends
  • Consultants and professionals staying across sectors relevant to their clients
  • Business owners looking for leads, context and market intelligence

Most Business News publications cover national or global markets. Business News is focused entirely on Western Australia, which means the journalism, the data and the intelligence are all built around WA companies, people and projects — not adapted from a national feed. Data & Insights, included with every subscription, combines more than 30 years of WA-specific editorial research with live business data. There’s no comparable product for the WA market.

Advertisement

The Morning Digest Email provides a comprehensive wrap of the major headlines, relevant to WA business, and includes with a snapshot of the overnight news covering oil, gold and ASX-listed companies.

The Afternoon Wrap Email focuses on the news covered by our team of journalists during the course of the working day, including exclusive stories and analysis, all of which relates to WA business and the local economy.

The BN Weekender Email contains a wrap of the Business News from the week that was, highlighting the top stories in each area of WA business.
Sign up for free.

Advertisement

We’re happy to help.
Get in touch
and our team will come back to you.

Advertisement
Continue Reading

Business

Microsoft Stock Hit My Target. Now I’m Stepping Back (NASDAQ:MSFT)

Published

on

Microsoft: I Like This Price And I Like This Strategy More Than The Stock (NASDAQ:MSFT)

This article was written by

I’m an ACC-qualified finance professional with a Master’s in Audit & Accounting from Istanbul University and certificates in Data Analytics from Coursera. For over two years, I’ve worked as a Data Scientist and Financial Analyst at a leading property management firm in Istanbul, where I developed budgets, set targets, and applied data-driven insights to maximize profitability. My expertise spans financial modeling, market analysis, and investment research, including hands-on experience in stocks and cryptocurrency. Through concise, conversational writing, I now share these insights to help readers make smarter financial and investment decisions.

Analyst’s Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.

Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.

Advertisement
Continue Reading

Business

Columbia Disciplined Growth Fund Q2 2026 Commentary (RDLAX)

Published

on

Northern Small Cap Index Fund Q1 2026 Commentary (Mutual Fund:NSIDX)

Columbia Threadneedle Investments is a leading global asset management group that provides a broad range of actively managed investment strategies and solutions for individual, institutional and corporate clients around the world. Columbia Threadneedle Investments is the global asset management group of Ameriprise Financial, Inc. (NYSE: AMP). For more information please visit columbiathreadneedleus.com.

Continue Reading

Business

Parker Group to reclaim The Royal Hotel in Perth CBD

Published

on

Parker Group to reclaim The Royal Hotel in Perth CBD

Parties have executed a deed to return The Royal Hotel in Perth to Parker Group’s hands, which includes a $850,000 fund from the John Parker-led hospitality business.

Continue Reading

Business

The WRU has a business plan for cutting a region but it needs to be shared

Published

on

Business Live

The WRU now has the opportunity, when appearing before the Senedd committee, to finally put the record straight

WRU CEO Abi Tierney(Image: Mark Lewis/Huw Evans Agency)

For months those questioning the Welsh Rugby Union’s decision to reduce the professional game from four teams to three have been told the decision followed extensive consultation, detailed analysis and independent challenge.

When WalesOnline recently raised concerns about the lack of supporting data, the WRU said it would “publish the information soon”, including more detail on the reasoning, evidence, criteria and weightings behind its proposals. Now, at long last, we finally know that decisive evidence exists, but the WRU does not intend to publish it in a form that would allow anyone to test its conclusions.

Advertisement

In correspondence with me last month, chief executive Abi Tierney confirmed that the board considered a “detailed, fully costed business case comparing three teams against a reformed four-team alternative” before reaching its decision last autumn.

According to Ms Tierney, this incorporated financial analysis, strategic considerations, risks and stakeholder feedback. That confirmation matters, as we now know a business case apparently underpinned one of the most important and effectively irreversible decisions in Welsh rugby history.

Unfortunately, none of us can currently see it because Ms Tierney conveniently said the material is commercially confidential and “will not be published in the form you have requested”. Instead, member clubs will receive what she describes as “the appropriate briefings and evidence through the proper channels” before the WRU’s annual general meeting.

That language is very revealing because it suggests that clubs are not being promised the business case or underlying model, but whatever the WRU decides is “appropriate”. They may receive selected presentations explaining a decision already made without the evidence needed to test its assumptions or develop an alternative.

Advertisement

Sadly, for a modern organisation that is supposed to hold to the highest standards of governance, that is not meaningful transparency but managed disclosure. Explaining where three professional teams should be located is no substitute for demonstrating why Welsh rugby must be reduced to three teams in the first place.

In other words, the WRU is offering evidence about the consequences of its decision while withholding the evidence that supposedly justified making it.

Following a letter from that Hayley Parsons and I sent to the Senedd’s sport and culture committee about this failure to reveal the data to the clubs once again, Ms Tierney and the WRU are to be invited to appear before the committee for the second time this year.

So what should the WRU reveal when they appear before members of the Senedd?

Advertisement

Without getting too technical, they should start with details of the formal post-consultation option appraisal the board considered in October 2025 and submit, as evidence, the underlying financial model, including annual projections, funding allocations, revenue assumptions, owner contributions, and transition costs.

Without it, Senedd members and their constituents cannot establish what reducing the number of teams saves, whether the preferred structure survives less favourable assumptions, whether alternatives were assessed fairly, or whether the calculations were independently verified.

The WRU must also explain what it means by a “reformed four-team alternative” and whether that option incorporated the same shared services, central efficiencies, player controls, pathway reforms and commercial improvements assumed for three teams, or was the preferred model compared with a weaker version of four that was never given an equal opportunity to succeed?

The committee should also consider the wider consequences of removing a professional team, especially given that an independent report found the Scarlets generated over £1m in annual gross value added and supported 336 jobs, alongside extensive work with schools, community clubs and disadvantaged groups.

Advertisement

In Swansea, substantial public and private investment has already been committed to the Ospreys and the redevelopment of the ground at St Helen’s.

It would have been better to have had the answers made public before having to ask a Senedd committee to intervene, but we cannot know what the board considered because the business case remains withheld. Indeed, Ms Tierney told me that correspondence about governance and disclosure should be properly conducted with member clubs rather than “individual columnists or commentators”.

That is a curious position as the WRU seems happy to use the media to assure the public that evidence would be published but appears less comfortable when one of the Western Mail’s longest-serving columnists asks what will be disclosed.

Speaking truth to power has been one of this column’s central purposes for over twenty years, and I will not be discouraged from doing so simply because the organisation being scrutinised would prefer the questions not to be asked publicly.

Advertisement

Yes, the WRU is entitled to refuse to answer, but it should not pretend that the questions are illegitimate in doing so, and it will be interesting to see if it adopts the same approach with the Senedd and its member clubs as it did when it responded to my request for this information.

The WRU may ultimately be right that three (or even two) teams represent the only sustainable future, and anyone proposing an alternative must explain how it would be financed, but how on earth can any alternative be tested while the WRU withholds its financial data and assumptions?

And it is ironic that Ms Tierney, when speaking at the Welsh Select Committee last January, said that she would not “apologise for being data-driven”, and yet the more they hide this data, the more mistrust they generate in their ability to govern the game.

Therefore, the issue is no longer whether the evidence exists – it does – and given that Ms Tierney said member clubs should pursue these matters, I hope at least one will now formally request the complete business case and supporting evidence before the union’s AGM late this year.

Advertisement

The WRU now has the opportunity, when appearing before the Senedd committee, to finally put the record straight and, as part of its evidence, to provide all the information required to scrutinise its decision.

But if the WRU again refuses a reasonable request to do so from the democratically elected members of the Senedd whose constituents across Wales are supporters of local, regional and national rugby, then they can no longer claim that the problem was who asked the question, but that the WRU never wanted anyone outside its board to see the answer.

Continue Reading

Trending

Copyright © 2025