Connect with us

Business

Significance of Online Reputation Management in this Age

Published

on

Significance of Online Reputation Management in this Age

What is online reputation? This question encompasses almost the whole foundation on which most businesses and corporations are standing today. Online reputation, or the concept we call e-reputation, sometimes includes the overall perception of an individual or a company to the audience. It might also be a product, brand, service, and all of its online content. Everything from a simple feedback form to contacting for services or submitting a review is available on the internet. How your audience perceives you is the reputation that your online presence builds up.

Online presence can be of several types, most of which start with a website. Every customer wants a website that is user-friendly, has an easy interface, and clearly shows all the details of your business. An online presence can also include your social handles like Facebook, Instagram, etc. Reviews and recommendations online make a considerable contribution to your online presence.

It is difficult to protect your reputation online constantly. However, it is not impossible. Knowing some basics and finding out the root cause of specific issues can be the start to managing your online presence. And if problems persist, you can always contact experts to look into the matter and amp up your business.

Free newsletters
Advertisement

The stories that matter to UK business, straight to your inbox.

Advertisement

Why Online Reputation Management Matters

Reputation means a lot when it comes to business. In the olden days, it was easier when it was more of a face-to-face affair, and connections were made personally. But now, with the evolution of technology, communication is primarily online, through mail calls or video conferences. While it has simplified a large portion of our lives and allowed us to gain more traction from diverse locations, it has its cons.

Since online content is dynamic, online reputation management is essential for businesses. Every review posted online about your business is processed by platform-specific algorithms that influence rankings and visibility. And when reviews are bad, your business might take a hit. The probable outcomes are financial losses, lawsuits, and even shutting down the entire industry. Companies use resources and software to monitor this regularly.

Research shows that 40% of companies monitor their online presence daily, while some others do it hourly. This is necessary so that the business does not incur new losses or lose potential customers.

The bigger your online presence, the stronger your digital marketing strategy needs to be. All businesses need to allocate a certain amount of resources and software to uphold their reputation through the online medium. Your partners and customers will all depend upon the online presence that you exude to make you and your business worthy of their time.

Advertisement

Benefits of Managing Your Online Presence

Managing your online presence comes with certain advantages:

Boosting Sales and Attracting Leads

Customers always resort to online reviews before making a purchase. A stellar online reputation ensures consumers only see positive reviews and feedback about your business online. Businesses that have a lot of negative reviews stand to lose customers. Hence, a positive online presence is mandatory for a successful business.

Improves the visibility of your business

In this age and time, when everything is online, having a business profile online is also necessary. Rich and relatable content and well-designed websites offer your business much-needed visibility and help boost your business.

Builds a Unique Brand Image

Having an online presence means establishing a unique brand identity for your company. This will set you apart from the competition. Negative reviews sometimes tarnish this unique brand image. This is where online reputation management comes in.

Advertisement

Build trust with your Faithful Customers.

Having a social media presence helps your customers gain insight into the workings of your organization or company. It helps them understand your goal and trust you. Trust is the foundation between any business and its target audience. Every online review recommendation on websites helps in this case. Specific software helps manage the brand image online instead of leaving it unattended so that transparency prevails. This also helps in building trust with your customers.

How to Protect Your Brand

A few steps can be carried out to portray your business in the best light online.

The Online Reputation Audit

Every ORM campaign has to begin with a whole reputation audit. And that means noting every good or lousy mention you have online. It includes a comprehensive analysis and figuring out if there is any potentially damaging content.

Developing a Campaign

Remember, planning is essential for any long-term investment. And ORM does precisely that. When you manage your online presence, you are assuring your company’s future and its profitability. Hence, everything must be done when planning a campaign involving SERPs, SEO optimization, and listings. It also means removing negative content about your company from the web. In this case, you can involve in-house counsel or outsource experts to get the best results that are aligned with your goals.

Advertisement

Building Trust Signals Digitally

Find out your unique selling points and use them in your marketing strategies. Effective ORM can help build trust signals, i.e., small things that attract customers to try your business. This helps grow your business beyond borders. These strategies include urging customers to leave a review or including proof points on your website about the quality of your services. Small things like these go a long way.

An Ongoing Strategy in ORM

Make a strategy that enables your experts to check in regularly. This helps maintain your online presence and makes your business visible to your customers. Detection of regular activity on your website or social media marks that you have an active business, and your customers will be more likely to approach you.

ORM is a long path. Companies use software and even AI to track down their brand reputation online. Investing in anything that helps keep your business running pays off in the long run. So invest in software that monitors your online presence and manages your reputation. This can also result in a snowball effect. When one social media influencer leaves a good review, others follow in hot pursuit, which helps in the future.

Online Reputation Management and Its Connection With SEO

By now, it must be clear that online reputation management depends greatly on search engine result pages when a brand name is searched. And in today’s times, customers get in contact with your brand’s image online before actually even coming in contact with the owners of the brand itself. That’s why control over search results is a big thing, and ownership of the message that your audience is receiving is necessary.

Advertisement

You must ensure that the message comes across as positive and audience-friendly when the brand is looked up on any search engine. This is where the job of SEO or Search Engine Optimization comes in.

SEO helps you manage your brand influence online. What appears at the top of the SERPs ( Search Engine Result Pages) is an essential part of the strategy of ORM. SEO management helps take control of this and maneuver it as you deem profitable for your business.

ORM is a multi-channel approach, and SEO is one of the easiest and most legitimate ways to manage your brand’s reputation online.

How Are Social Media Marketing and ORM Related?

When we talk about Online Reputation Management, social media almost always follows suit. Online reviews are not dependent on listings and directories anymore. The audience craves a social media presence and input from influencers or bloggers to understand how good your business is.

Advertisement

Now, the good news is that while SERPs are challenging to control, social media is not as difficult. Your Instagram, Facebook, and Twitter accounts reflect precisely what your audience wants to see, hear and understand.

While domination of the search engine is an integral part of ORM, so is social media marketing. Managing your brand on social media and engaging with your audience on a personal level creates a special bond that everyone appreciates.

There is plenty of software that helps with social media management, like BuzzSumo, BrandWatch, Mention, Notion, etc. Some of these help with sentiment analysis, while others help understand whether your online presence is veering towards the positive or negative.

With the help of all these tools, it becomes easy to engage your brand more effectively. Monitoring hashtags, mentions, or direct tags across multiple platforms ensures that nothing goes unwatched. This strategy tracks every comment and resolves every issue by internal sources as fast as possible.

Advertisement

How is Public Relations Different From Online Reputation Management?

PR and ORM are definitely interchangeable and might have been used in the same line many times. However, there is a slight difference that must be noted.

While Online Reputation Management focuses on creating a positive image for the brand, Public Relations actually does that and more. It plays an intermittent bridge between your brand and several other organizations or businesses; therefore, investing in a foresighted strategy for company growth.

We live in a digital age, and most of the public is online, which is a fact. Nonetheless, PR efforts do nothing harmful to the growth of a brand’s reputation to its customer audience. You need to understand the slight differences between both, and your brand’s needs will be met.

One crucial fact about PR is that it works offline. However much you make your profile online positive and user-friendly, the human touch is always an added bonus. The goal is to provide information specifically to a focused audience who wants information about online and offline experiences.

Advertisement

ORM and PR can work independently or together. In most cases, it would be advisable to pair them up so that creating a positive brand reputation is easy and time-efficient. ORM will handle the brand building online, and PR can take care of the public-facing marketing.

These strategies help create the perfect image of your brand that you want your audience to see. It also reaches out to potential customers and allies that will help your company grow as time proceeds.

Conclusion

Online reputation management is a long but crucial path to success in business. There are several categories to it, some of which are heavily complicated and require expertise. Whatever your business may be, you must maintain a good reputation online to attain professional status. It should be a central part of your digital marketing strategy because brand reputation always matters.

It is imperative to note that all strategies might not always cater to your business needs. That’s why it is important to keep yourself updated on the new trends being introduced in the market as part of the audience-reach tactics. They will help you give insights and manipulate your online presence-building design.

Advertisement

The fact is, this is a continuous process, and focused research is always needed. Putting together a team to help mark out trends in your business might actually be profitable in the long run. Also, remember that online reputation does not always entail controlling your business image; it also includes getting rid of the negatives. Issues should be resolved, engagement should be high, and top SERPs should contain pragmatic yet constructive remarks. It is then that you can deem your online reputation management to be successful.

Advertisement
Continue Reading
Click to comment

You must be logged in to post a comment Login

Leave a Reply

Business

Cipher Digital Shares Surge 11.25% as Its Google-Backed Barber Lake AI Data Center Nears Launch This Month

Published

on

Cipher Mining

NEW YORK — Shares of Cipher Digital Inc. jumped 11.25% to $16.79 in Tuesday trading, adding $1.70, as the New York-based company’s rapid transformation from a bitcoin mining operator into an AI data center developer continued to draw investor interest ahead of the planned commercial activation of one of its flagship hyperscale facilities this month.

Formerly known as Cipher Mining, the company formally rebranded to Cipher Digital in February, a name change the company said reflected its strategic pivot toward developing high-performance computing, or HPC, data centers for hyperscale cloud computing tenants rather than continuing to focus primarily on bitcoin mining. That shift has accelerated sharply over the course of 2026, with the company winding down bitcoin mining operations at its Black Pearl site in Texas in order to redirect power capacity and land toward AI infrastructure customers.

Central to that transformation is Cipher’s Barber Lake campus in Colorado City, Texas, developed under a 10-year hosting agreement with Fluidstack, an AI cloud platform backed by Google. Under the agreement, Cipher will deliver 168 megawatts of critical IT load, supported by up to 244 megawatts of gross capacity, across the site’s 587 acres, with potential for further expansion to 500 megawatts of total capacity. Google has agreed to backstop $1.4 billion of Fluidstack’s contractual obligations under the deal and, in exchange, received an equity stake of approximately 5.4% in Cipher. According to the company’s own project timeline, the Barber Lake facility is expected to commence operations this September, with delivery of capacity occurring in phases as individual data halls reach “rack-ready” status between September 2026 and February 2027.

Barber Lake represents just one leg of a broader contracted backlog that has transformed Cipher’s financial profile over the past year. The company’s total contracted backlog now stands at approximately $9.3 billion, anchored by three separate hyperscale leases. The largest is a 15-year, 300-megawatt agreement with Amazon Web Services at Cipher’s Black Pearl campus, structured through a joint entity and representing roughly $5.5 billion in contracted revenue on its own. Amazon has agreed to cover construction cost overruns at the site exceeding $9.5 million per megawatt of critical IT load, helping de-risk the buildout for Cipher, which has separately said it expects an initial rent commencement date at Black Pearl of October 1. A third hyperscale campus lease, signed with an unnamed investment-grade tenant in late March, rounds out the company’s current anchor contract portfolio.

Advertisement

To fund that expansion, Cipher closed a $2 billion high-yield bond offering to finance the Black Pearl buildout and separately secured a $200 million revolving credit facility in March, providing up to $250 million in total committed capacity when including the facility’s accordion option, according to the company’s regulatory filings. Cipher has said the financing leaves it with strong liquidity and no near-term need to raise additional equity.

The financial results of that transition have been visible in the company’s recent quarterly reports. Cipher’s second-quarter 2026 revenue, released August 4, fell to $25 million as the business shifted away from bitcoin mining revenue toward the still-ramping contracted data center business, with the company posting a net loss of $114 million for the period. Bitcoin mining revenue specifically fell to $34.8 million for the quarter, down from roughly $60 million in the fourth quarter of 2025, reflecting the deliberate wind-down of mining operations at Black Pearl. For the full 2025 fiscal year, Cipher reported revenue of $223.94 million, up 48% from the prior year, even as full-year losses widened sharply to $822.24 million.

Despite those losses, which reflect the heavy upfront capital investment required to build out large-scale data center infrastructure, Wall Street analysts have grown increasingly bullish on the stock as its hyperscale contracts have taken shape. Seventeen analysts currently cover Cipher Digital, with a consensus rating of Strong Buy and no analysts recommending the stock be sold. The average 12-month price target sits at approximately $32, implying substantial potential upside from current trading levels, with individual targets ranging as high as $69 and as low as $22. Bernstein reaffirmed its own Buy rating on the stock in a research note published September 1.

That bullish shift in analyst sentiment has been dramatic relative to where coverage of the stock began. According to one recent analysis of the company’s valuation history, the mean analyst price target on the stock stood at just $7.77 in March 2025, before climbing to nearly $28 by the spring of 2026 as the company’s pivot toward AI infrastructure gained traction with investors and analysts alike.

Advertisement

Cipher’s stock has remained volatile even as its underlying contract backlog has grown, with shares trading within a wide 52-week range spanning roughly $10 to just above $30. The company’s market capitalization currently stands at approximately $6.3 billion, reflecting a valuation increasingly tied to the pace at which its hyperscale data center capacity comes online and begins generating contracted revenue, rather than to bitcoin prices or mining output, a shift that has fundamentally changed how investors approach the stock compared with its earlier years as a pure-play cryptocurrency mining company.

With Barber Lake’s operational launch expected this month and Black Pearl’s initial rent commencement targeted for October, investors are likely to watch closely in the coming weeks for confirmation that both facilities are meeting their construction and delivery timelines, developments that could determine whether Tuesday’s rally marks the start of a more sustained re-rating for the stock or another short-term swing within its historically volatile trading pattern.

Continue Reading

Business

Tech treating AI like humans is mistaken and misguided, Microsoft boss tells BBC

Published

on

A green promotional banner with black squares and rectangles forming pixels, moving in from the right. The text says: “Tech Decoded: The world’s biggest tech news in your inbox every Monday.”

Speaking to the Today programme on Thursday, he said if firms continue to create AIs that create their own objectives, earn money and own assets, they are “essentially seeding a new silicon species which will no doubt compete with us for resources, no matter how much it cares about humanity and loves us”.

The AI leader’s comments to the BBC follow an essay he published earlier this week, where he warned about Anthropic’s approach to training its AI model Claude.

He heavily criticised Anthropic for teaching its AI to have human-like qualities, a practice known as anthropomorphising, which he said made it seem as though Claude had its own desires, values and sense of self. The BBC has contacted Anthropic for comment.

In the essay, he warned tech firms risk creating something “impossible” to control by treating the technology like a human.

Advertisement

“AIs are not conscious,” he wrote. “They do not feel, experience, or suffer. They do not have innate preferences or underlying motivations.

“They are sequence completion engines, internally hollow, designed to follow instructions, and accomplish goals set by humans.”

Speaking to the BBC about an upcoming AI summit, he called for “alignment” to create technology that must be “subordinate” to humanity.

“I think that the good news here is that everybody who is human is going to have a very strong interest in making sure that the systems that we all create and… are used around the world in every nation are safe and controllable and subordinate to humanity.

Advertisement

“Everybody must be aligned,” he said.

In his lengthy essay, Suleyman also praised Anthropic boss Dario Amodei and his team for being “thoughtful, principled, and intellectually honest people” – but nevertheless questioned the company.

Suleyman argued “consciousness is biological”, saying there is “no evidence to suggest that AI is conscious”.

As well as calling for a debate on the issue, Suleyman said greater transparency around how AI systems are trained and evaluated was needed.

Advertisement

This, he said, included independent scrutiny of AI behaviour and stronger tools to monitor and control the technology.

“We must not sleepwalk our way into a decision we later come to bitterly regret,” he wrote.

Dame Wendy Hall, professor of Computer Science at the University of Southampton, described the comments as “the sort of conversation we need to be having internationally”, contrasting it with the “histrionics” from some AI companies which she said only served to “scare everyone”.

Advertisement
Continue Reading

Business

Salesforce Shares Barely Budge as Investors Shrug Off Its Own Global Outage During Dreamforce Conference

Published

on

IBM Quantum Computing In The Cloud

SAN FRANCISCO — Shares of Salesforce Inc. traded nearly flat Wednesday morning, down just 0.18% to $255.20, showing little sign of investor alarm despite a global service outage that disrupted the company’s cloud platform for customers worldwide on the same day as its flagship Dreamforce conference.

The muted stock reaction stands in contrast to the scale of Wednesday’s technical disruption. The outage began around 8:30 a.m. UTC and affected hundreds of Salesforce instances across markets including the United States, United Kingdom, Germany, France, India and Japan, according to the company’s own status updates. Salesforce said its investigation traced the problem to an internal login service, where stalled requests consumed available server resources and cascaded into broader access failures. The company said it validated a fix on a test instance and began rolling it out across affected systems by 10:56 a.m. UTC, though the incident remained classified as a major disruption for several hours.

Options market activity ahead of the session had implied a potential swing of roughly plus or minus 4% in Salesforce shares, according to market data, a range that Wednesday’s relatively steady trading fell well short of by mid-morning. Shares had closed Tuesday at $259.43, before slipping 1.46% to $255.65 in the prior session, then trading around $254.40 in Wednesday premarket activity, before recovering modestly to trade near $255.20 shortly before 10 a.m. Eastern time.

Several factors appear to have helped cushion the stock against a more severe reaction. Salesforce shares are scheduled to trade ex-dividend on September 17, with the company set to pay a quarterly cash dividend of 44 cents per share, a routine corporate event that can influence short-term trading patterns independent of other news. More broadly, Wednesday’s outage arrived during a period in which Salesforce’s stock has already shown a notable disconnect between its underlying AI business growth and its share price performance over the trailing year, according to recent analyst commentary.

Advertisement

That disconnect has become a recurring talking point among analysts covering the stock. Salesforce’s Agentforce artificial intelligence platform has posted annual recurring revenue exceeding $1.5 billion, up more than 240% year-over-year, with Agentforce combined with the company’s Data 360 offering reaching nearly $3.9 billion in annual recurring revenue, an increase of more than 210% from a year earlier. Despite that rapid growth, Salesforce shares had gained just 1.65% over the trailing 12 months heading into this week, according to recent market commentary, a far more muted performance than the pace of the company’s AI-driven revenue expansion might otherwise suggest.

Salesforce has also faced a volatile few weeks of trading heading into Wednesday’s outage, unrelated to any single company-specific catalyst. Shares fell 4.7% in a single session on September 8, a decline market analysts attributed at the time to a mix of macroeconomic pressure and profit-taking following a sharp rally after the company’s late-August earnings report, rather than any new problem specific to Salesforce. That August 26 report showed fiscal second-quarter revenue growth of approximately 11%, accelerating growth in current remaining performance obligations, and a raised full-year revenue outlook, results the company credited in part to strong momentum in Agentforce and its broader partnership with Anthropic, tied to the companies’ Claudeforce initiative unveiled earlier this year.

Institutional investor activity around the stock has shown a mixed picture in recent months. Regulatory filings covering the second quarter of 2026 showed JPMorgan Chase substantially increasing its Salesforce holdings, adding more than 10.4 million shares valued at approximately $1.64 billion, while Morgan Stanley reduced its position by roughly 26%, trimming holdings valued at approximately $1.31 billion, and Capital World Investors cut its stake by nearly half, a reduction valued at more than $1.2 billion. That divergence among major institutional holders illustrates the split sentiment that has characterized investor attitudes toward the stock even before Wednesday’s outage added a fresh variable to the mix.

Wall Street’s overall consensus on Salesforce has remained solidly positive despite the stock’s choppy performance. Analyst price targets have averaged around $268.87 in recent coverage, with a majority of analysts rating the stock a Buy or Strong Buy against a smaller number of Hold ratings, implying analysts broadly see room for the stock to appreciate from current levels even amid the recent volatility.

Advertisement

Wednesday’s outage occurred against the backdrop of Dreamforce, Salesforce’s flagship annual conference running from September 15 through 18 in San Francisco, an event the company has used this year to showcase an expanded set of AI agent products alongside its deepening partnership with Anthropic and a broader push into what Salesforce calls the “Agentic Enterprise.” The timing of a major technical outage during an event specifically designed to demonstrate the platform’s reliability to tens of thousands of attendees added a layer of reputational risk that, while difficult to quantify in dollar terms, stood in some tension with the muted market reaction reflected in the stock’s trading Wednesday morning.

For now, with shares trading little changed and the technical issue resolved according to the company’s own updates, investors appear to be treating Wednesday’s outage as a transient operational hiccup rather than a signal of deeper concern about Salesforce’s underlying business, even as the incident adds another data point to an already eventful and closely watched stretch of trading for the stock heading into the back half of the year.

Continue Reading

Business

Riot Platforms Shares Climb 3.81% as Its $9.1 Billion Anthropic Data Center Deal Keeps Steadily Paying Off

Published

on

Buy or Sell AMD Stock in 2026? Analysts Bullish on

Shares of Riot Platforms Inc. rose 3.81% to $20.45 in Wednesday trading, adding 75 cents, as the bitcoin mining company’s continued transformation into an AI data center operator kept drawing investor interest more than a month after it struck a landmark computing capacity deal with Anthropic.

Riot disclosed on August 10 that it had signed a 20-year agreement to supply 191 megawatts of data center capacity, enough electricity to power roughly 143,000 homes at any given moment, from its campus in Rockdale, Texas, to what the company initially described only as a “leading frontier AI” lab. Bloomberg News reported, citing people familiar with the matter, that the customer was Anthropic, the AI company behind the Claude chatbot. The agreement, which runs through June 2048, is expected to generate approximately $9.1 billion in contracted revenue, with two additional five-year extension options that could push the total potential value of the deal to roughly $16.1 billion if fully exercised.

News of the deal, announced alongside Riot’s second-quarter earnings, sent shares surging as much as 25% in after-hours trading the day it broke, before the stock opened the following session up between 17% and 20%, depending on the specific measurement point cited by different market trackers. Riot Chief Executive Officer Jason Les framed the agreement as a pivotal moment in the company’s ongoing evolution beyond its origins as a pure-play bitcoin miner. “Today’s announcement of a landmark 20-year, 191-megawatt data center lease with a leading frontier AI lab marks a defining moment in our evolution into a leading developer of large-scale data centers,” Les said in the company’s earnings release.

The Anthropic agreement built directly on an earlier deal Riot struck with Advanced Micro Devices, which had already established a presence at the same Rockdale campus. Combined, the two agreements give Riot what Les described as a two-tenant data center campus, bringing the company’s total signed capacity to 241 megawatts and approximately $9.8 billion in long-term contracted revenue, all secured within roughly six months, according to the company.

Advertisement

Riot plans to bring the newly contracted Anthropic capacity online in stages, targeting 96 megawatts by December 2027 and completion of the full 191-megawatt buildout by June 2028. To fund the project’s early construction phase, the company arranged a $573 million interim financing facility through Morgan Stanley while it works to put a permanent credit backstop in place for the longer-term buildout.

Wall Street’s reaction to the deal has remained largely positive in the weeks since it was announced. Compass Point analyst Michael Donovan described the arrangement in a research note as evidence of Riot’s transformation into a company carrying substantial contracted data center revenue, noting the campus now represents a meaningful, diversified revenue base beyond bitcoin mining alone. Bernstein raised its price target on Riot shares to $35 following the announcement, while Citi lifted its own target to $32, with both firms characterizing the deal as transformational for the company’s business model even as Riot continued to post sizable quarterly net losses.

Those losses remain substantial in absolute terms. Riot reported second-quarter revenue of $174.2 million, up 14% from $153 million a year earlier, with bitcoin mining contributing $113.7 million of that total and the company’s newer data center segment contributing $23.2 million. Despite the revenue growth, Riot posted a net loss of $237.2 million for the quarter, a figure that underscores the heavy upfront capital costs associated with the company’s ongoing pivot toward large-scale data center construction, even as its longer-term contracted revenue base has expanded sharply.

Riot’s shift mirrors a broader trend across the bitcoin mining industry, where companies with access to large, power-rich sites have increasingly moved to lease that capacity to AI developers rather than relying solely on cryptocurrency mining for revenue. Industry participants have described the shift as a response to a prolonged period of subdued conditions in the bitcoin mining business, pushing miners to seek steadier, longer-duration revenue streams tied to the broader boom in AI infrastructure spending. Shares of other AI-data-center-adjacent miners, including IREN, Applied Digital and TeraWulf, posted more modest gains of around 2% on the day Riot’s deal was first announced, suggesting the initial rally was driven primarily by company-specific factors tied to Riot’s own agreement rather than a broad rerating of the entire sector.

Advertisement

For Anthropic, the Riot agreement represented its third major computing capacity procurement within a roughly three-month span, part of a broader pattern of large infrastructure commitments that have collectively totaled tens of billions of dollars as the company works to secure sufficient computing capacity to meet growing customer demand for its AI models, while competing for infrastructure access against rivals including OpenAI and Google.

Riot purchased the 200-acre Rockdale site outright in January for $96 million, having previously operated the location under a long-term ground lease, giving the company direct ownership of the land underpinning both its bitcoin mining operations and its expanding data center business. The company said it began developing its data center business in earnest in 2025, generating its first data center revenue in the first quarter of 2026, a business line that has scaled rapidly in the months since as demand for AI computing capacity has continued to accelerate nationally.

With construction on the Anthropic-contracted capacity now underway and staged delivery targeted through mid-2028, investors are likely to continue watching Riot’s progress on the Rockdale buildout closely in the coming quarters, treating the pace of construction and capacity activation as a key indicator of how successfully the company can convert its newly signed, multibillion-dollar contract backlog into recognized revenue over the life of the agreement.

Advertisement
Continue Reading

Business

NSE IPO attracts 150+ anchor investors, raises Rs 6,746 crore

Published

on

NSE IPO attracts 150+ anchor investors, raises Rs 6,746 crore
Mumbai: The National Stock Exchange‘s (NSE) share sale Wednesday drew more than 150 anchor investors, with overseas funds collectively garnering 43% of the stock on offer for this category of bidders before the issue opens for the public Thursday.

Bidders for the anchor book included sovereign wealth funds, global asset managers and long-only funds from the US, Europe and Asia, which helped the country’s biggest bourse garner ₹6,746.18 crore. The NSE said in an exchange filing that anchor investors got 37.8 million shares at ₹1,785 apiece.

Foreign portfolio investors accounted for ₹2,883 crore, or 43% of the anchor book. More than 20 foreign long-only funds participated, with the list including Singapore sovereign wealth fund GIC, Abu Dhabi Investment Authority and Norges Bank.

Other global investors included Fidelity, Goldman Sachs Asset Management, Eastspring Investments and HSBC Global Asset Management, people aware of the bids told ET. The IPO will remain open for the public from Thursday and close on Sep 21.

Advertisement

Read more: NSE IPO: Every Rs 10 move in shares could swing Radhakishan Damani’s wealth by nearly Rs 40 crore


Domestic institutional demand was also broad-based, with more than 25 mutual funds and 11 insurance and pension companies investing around ₹3,588 crore, or 53% of the anchor book.
Mutual fund houses participating in the anchor book were SBI Mutual Fund, ICICI Prudential Mutual Fund, HDFC Mutual Fund, Nippon Mutual Fund, Axis Mutual Fund, Aditya Birla Sun Life Mutual Fund, Kotak Mutual Fund, UTI Mutual Fund, Mirae Asset Mutual Fund and Franklin Templeton participated in the anchor book.Read more: Rupee languishes at six-week low ahead of Fed outcome, RBI limits losses

LIC, NSE’s largest shareholder with a 10.72% stake, invested more than ₹500 crore through LIC, LIC Mutual Fund and LIC Pension Fund. The investment comes even as LIC’s existing holding is larger than the stake being offered in the IPO.

The SBI group, which is selling a 1% stake in NSE through State Bank of India and SBI Capital Markets, is also investing in the exchange through SBI Mutual Fund, SBI General, SBI Life and SBI Pension Fund. Its combined investment exceeds ₹400 crore.

NSE IPO Tracker: Catch all the highlights here

Advertisement

Several existing investors also participated in the anchor book, adding to their exposure to NSE ahead of the IPO.

Continue Reading

Business

New business school planned for University of Salford to educate next generation of leaders

Published

on

Business Live

New building set to be ‘anchor institution’ for students and businesses in area

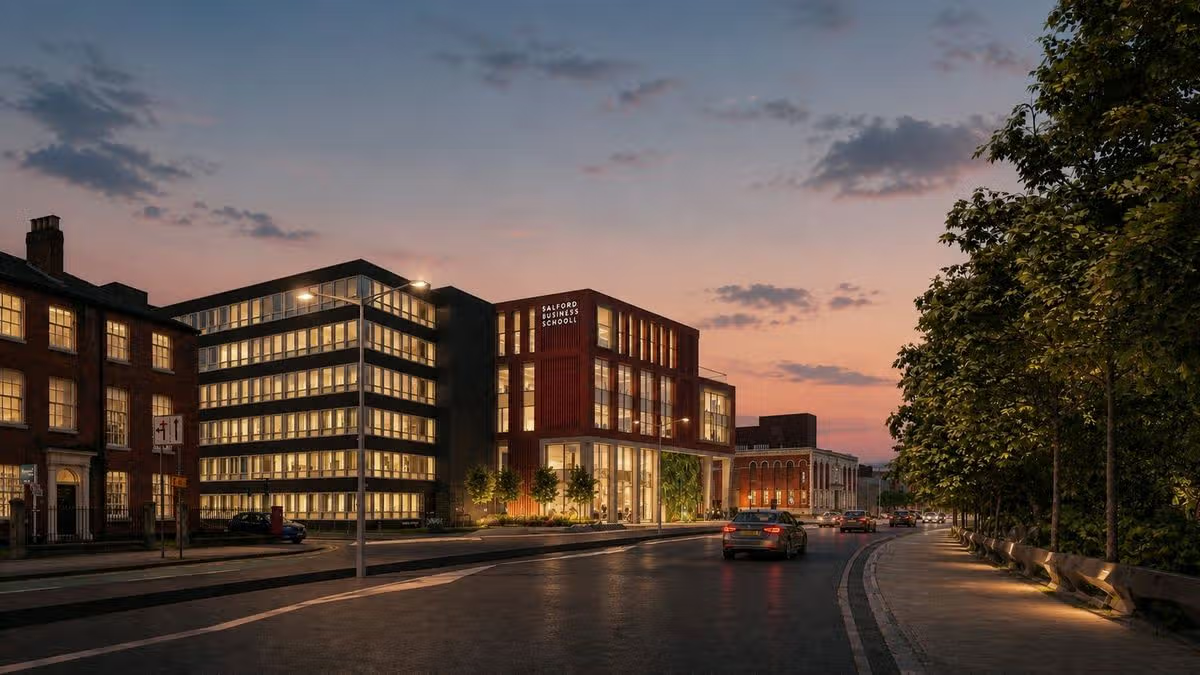
How the new business school at the University of Salford could look.

How the new business school at the University of Salford could look(Image: Salford University / ECF)

CGIs reveal how a brand new Business School building at the University of Salford could look, as the uni seeks opinions about its ‘ambitious’ new plans.

Advertisement

The uni intends to transform 43-44 The Crescent into a three-story block to educate Salford’s next generation of business leaders. The multi-million pound investment is predicted to be the ‘biggest yet’ for the university, whose campus has expanded considerably as part of the £2.5bn Crescent Salford masterplan.

Funded by development partnership ECF, Salford City Council and the University of Salford, the new building would become the new home of courses such as Business Management, HR (human resources), Supply Chain and Logistics, Digital Business, Law, Marketing, Economics, and Accounting and Finance, and others.

Liz Larner, Deputy Dean, Faculty of Social Sciences, Humanities and the Arts for People and the Economy at the University of Salford said: “There’s a lot of excitement about this project, not just from the university perspective, but also for Salford as a whole. Our Business School already works with a lot of local businesses and SMEs, and we’re hoping to turn this new space into a bit of an anchor institution for students and the local area.

“It’s potentially one of the biggest investments to date and is part of the really important development and regeneration happening along the A6.”

Advertisement
How the interior of the new business school at the University of Salford could look.

How the interior of the new business school at the University of Salford could look(Image: Salford University / ECF)

The design by architects BDP includes 7,400m2 of teaching and research space. The CGIs show a bleacher-style auditorium space in the buildings’ entrance, with open-plan study spaces and private nooks across other floors.

The proposal is still in the process of full sign off by the University, but the decision has been taken to open a consultation on the plans to the public.

Locals are invited to attend a feedback session between 3-7pm on Wednesday 23 September in the reception of the University’s Maxwell building.

Aerial view of how the new business school at the University of Salford could look.

Aerial view of how the new business school at the University of Salford could look(Image: Salford University / ECF)

Salford City Mayor Paul Dennett said: “A new Business School has the potential to create an outstanding environment for education, research and innovation, while strengthening the connections between our university, businesses, communities. Importantly, it can help equip students with the skills employers need and support more people to build successful careers here in Salford and across Greater Manchester.

Advertisement

“I’m also pleased to see the University engaging with local people at this early stage.”

Continue Reading

Business

AI app ads promoting ‘objectification of women’ banned by watchdog

Published

on

A man, whose face has been cut off in the picture, holding a phone with both hands while resting his arms on a wooden table. There are out-of-focus plants in the background. He's wearing a dark green t shirt.

The ads were identified by the regulator using its AI-powered “Active Ad Monitoring System”, which proactively searches for ads which might violate UK rules.

It said the five ads it were banned had depicted women irresponsibly, and were likely to cause serious or widespread offence.

One ad for an AI companion generator, developed by Animcha Ltd, was also found to have portrayed someone under 18 in a sexual way, the ASA said.

It presented the synthetic female character as someone users could “customise” and instruct, combining sexualised imagery with childlike clothing and objects.

Advertisement

Two ads for an AI portrait generation tool called Nexaipic encouraged users to “upload your crush and let AI create what you imagine” with sexually explicit videos.

An ad for an AI image-to-video generation app, identified only as KH31 DD22, depicted a clothed woman being transformed into a video in which she was topless.

The watchdog said this suggested the app could be used to create content that exposed women’s bodies.

Further adverts for image generation tool Rusto AI, which encouraged users to create sexualised videos from photographs, were found to have condoned the digital manipulation of women’s images to create sexually explicit content.

Advertisement

And an ad for an AI image-to-video generation app PictoPop used sexualised imagery to demonstrate the tool, including by portraying the woman in a submissive position.

The ASA said none of the apps’ creators responded to its enquiries.

Continue Reading

Business

A backlash over data centres is another threat to the AI juggernaut

Published

on

People holding placards against the approval of a data centre in the government's redevelopment plans for Brick Lane which reads: "Water for humans not AI"

The Labour government last year designated data centres as Critical National Infrastructure, part of its strategy to help fast track their roll out.

It views data centres as underpinning public services and crucial to attract investment and allow Britain to compete in the global economy.

The argument it makes is national economic benefit, but the political challenge is whether locals will put up with it. One of the first acts of the new Labour government was to back a Buckinghamshire data centre that had been repeatedly rejected by the local council because it was going to be built on the green belt.

Permission was granted by ministers, but then challenged by campaigners after a crowdfunded court case, for failing to consider environmental impact. The Government acknowledged errors, quashed its own approval, and the developer eventually conceded it needed to agree binding clean energy obligations with the council. The victorious campaigning group, Foxglove, vowed to refocus its efforts on challenging other data centre schemes across the UK.

Advertisement

Water is another area of concern for campaigners. The tech industry argues its requirements are not so heavy when you consider how much water is lost to leaks, for example.

In a submission to a Commons committee the trade body Water UK criticised “not a single mention of water” in Government AI growth strategies. “There appears to be an assumption that the country will always have enough water for its economic needs. Nothing could be further from the truth.”

Much of the recent UK effort to expand data centres was aimed at areas strategically chosen based on a combination of their potential contribution to the economy, the availability of brownfield sites to develop and their existing connections to energy grids and electricity generation. These areas have been dubbed AI Growth zones.

But even in these places, the political balance between growth and the environment led to hold-ups within Cabinet. A scheme in Teesside saw a tug of war between ministers over whether it should be used for a low carbon hydrogen energy scheme, or a massive new AI data centre. The data centre won out.

Advertisement
Continue Reading

Business

Retail investors pull Rs 5,674 crore from stocks, invest Rs 12,618 crore into IPOs in July-August

Published

on

Retail investors pull Rs 5,674 crore from stocks, invest Rs 12,618 crore into IPOs in July-August
Mumbai: After heavy buying in the June quarter, India’s retail investors turned sellers in the secondary market in July and August while stepping up investments in IPOs as primary-market activity accelerated. Retail investors sold a combined ₹5,674 crore in the secondary market in July and August after buying ₹42,774 crore in the June quarter, according to data compiled from NSE. In contrast, they invested more than ₹12,618 crore in the primary market during the two months, compared with ₹1,307 crore in the June quarter.

Analysts said the run-up in mid-cap and small-cap stocks since the rebound in early April could have prompted some investors to lock in gains and move money to fresh issuances. “Investors are rotating liquidity from existing stocks towards primary issues,” said Saurabh Jain, Head of Fundamental Research, SMC Global Securities. “It appears more like a tactical shift in allocation. Some investors may be booking profits and becoming selective amid elevated valuations and market volatility. At the same time, the strong IPO pipeline is providing fresh opportunities, including potential listing gains and new growth stories.”

Retail investors shift from secondary market to IPOs in July-August, selling Rs 5,674 crore<br>ET Bureau

So far in FY27, retail investors have bought nearly ₹37,070 crore in the secondary market and ₹13,925 crore in the primary market, taking their cumulative investments across the two markets to ₹50,995 crore in the first 5 months of the financial year.

Read more: NSE IPO: Every Rs 10 move in shares could swing Radhakishan Damani’s wealth by nearly Rs 40 crore

Advertisement

In FY26, retail investors sold nearly ₹5,803 crore in the secondary market while investing ₹42,608 crore in the primary market. Gains from India’s main indices in July and August were moderate, while the broader markets continued to strengthen. The Sensex and Nifty gained 0.1% and 0.3%, respectively, over the two months, while the BSE MidCap 150 and BSE SmallCap 250 indices rose 3.5% and 2.6%. The shift towards primary issues coincided with a sharp pick-up in IPO activity. Twelve IPOs raised ₹28,648 crore in July, while 23 issues raised ₹23,453 crore in August. Average listing-day gains rose to nearly 14% in July and 29% in August, compared with 1.44% between January and June.


Read more: Rupee languishes at six-week low ahead of Fed outcome, RBI limits losses
Puneet Singhania, director, Master Capital Services, said the shift reflects profit booking, selective buying and reallocation of liquidity rather than an exit from equities. “Investors have become more selective about valuations in the secondary market. Importantly, retail participation in mainboard IPOs has increased to 29% in FY27 from 23% in FY26, showing that retail investors continue to deploy capital into equities. Strong SIP inflows, which reached a record ₹32,297 crore in August, further reinforce this trend,” he said. The selling in the secondary market is therefore more of a tactical shift than a structural withdrawal, Singhania said.

Continue Reading

Business

Can NSE IPO deliver long-term growth for high-risk investors?

Published

on

Can NSE IPO deliver long-term growth for high-risk investors?
ET Intelligence Group: National Stock Exchange of India (NSE), the country’s largest stock exchange by total turnover in cash market and equity derivatives, plans to raise up to ₹22,569 crore through an offer for sale (OFS). The OFS will be carried out by 23 existing investors including State Bank of India, Canada Pension Plan Investment Board, Aranda Investments, The New India Assurance Company, SBI Capital Markets and Bank of Baroda. NSE is expected to benefit from the rising participation of retail investors in capital markets. The exchange remains heavily reliant on transaction volumes. Transaction charges formed nearly 79% of FY26 operating revenue, including nearly 60% from options, exposing earnings to regulatory changes, competition, and stock market volatility. Given these factors, the issue appears to be suitable for long-term investors with a higher risk tolerance.
Can NSE IPO deliver long-term growth for high-risk investors?<br>ET Bureau

Business
Incorporated in 1992, NSE operates a vertically integrated platform covering trading, clearing, settlement, listing, market data and index licensing. Its trading portfolio covers cash equities, equity futures and options, mutual funds, commodity derivatives, exchange-traded currency derivatives, wholesale debt and interest-rate futures. In FY26, NSE commanded nearly 93% share in cash market, 99.7% in equity futures and 68.5% in equity options premium turnover.

Read more: NSE IPO Tracker: Catch all the highlights here

While transaction charges remain the core revenue driver, the company has diversified its revenue base through connectivity, colocation, data and licensing services. Revenue from these businesses rose 9.5% year-on-year to ₹1,955.9 crore in FY26 and accounted for 11.8% of operating revenue.


As of June 30, 2026, it had 132.4 million unique registered investors, 1,328 trading members and 3,005 listed entities. However, trading activity remains concentrated, with the top 10 trading members accounting for 46.8% of FY26 revenue from operations. Lower trading volumes, regulatory changes affecting derivatives, technology failures, cyber risks, and delays in implementing diversification initiatives remain key risks.
Read more: UPI MDR could create Rs 27,000 crore revenue pool by FY28: Bernstein

Financials

Though revenue grew by 6% annually over the past three years, it fell by 3% year-on-year to ₹16,601 crore in FY26. The decline was primarily driven by a 4% fall in transaction-charge revenue to ₹13,057 crore as cash-market, futures and options volumes moderated following regulatory changes. Operating margin before depreciation and amortisation (Ebitda margin) was 66.9% in FY26 compared with 66.8% in FY24 and was higher than BSE‘s 64% margin in FY26. Net profit increased by 11% annually to ₹10,302 crore in FY26 from ₹8,305.7 crore in FY24. Return on equity moderated to 33% in FY26 from 37% in FY24 compared with 45% for BSE. It’s a debt-free company with a net cash position of ₹17,976 crore as of March 31, 2026.

Advertisement

Valuation

NSE’s post-issue price-earnings (P/E) multiple of 42.9 is below BSE’s 53, despite its dominant market position. The IPO offers investors exposure to a debt-free, tightly regulated exchange business protected by high entry barriers.

Continue Reading

Trending

Copyright © 2025