
Crypto World
A Solana oracle’s support ends today. Who still relies on its prices?

Switchboard’s September 25 support deadline has turned a six-day migration warning into a test of Solana’s price feeds. Current public documentation shows where its data remains part of an application’s design, but those pages cannot prove that a live market is still using the feed. Jito and marginfi provide two sharply different views of the exposure.
Summary
- Switchboard said technical support would end on September 25, 2026, after its September 19 wind-down announcement.
- Jito’s Tip Router documentation still names Switchboard as a pricing source for vault weights, although the overview is 9 months old.
- Marginfi’s September upgrade describes 9 new oracle setups that do not depend on Switchboard.
- A stale price feed can affect collateral checks, while Jito documents a separate fallback for reward-weight pricing.
- No live protocol-wide count of unmigrated Switchboard feeds was verified for the September 25 deadline.
Switchboard has reached its stated September 25 end of technical support, leaving Solana applications to verify the price sources configured in their live programs.
The oracle project’s September 19 statement, as reproduced in coverage of the announcement, said its core development contributor Switchboard Technology Labs would wind down and all implementations were deprecated immediately. The team urged integrators to migrate to other providers, naming Pyth and RedStone. September 25 was described as the last day for existing support. A company ending support is a real operational milestone. It does not, by itself, prove that every onchain feed stopped updating at midnight or that every application once associated with Switchboard remained dependent on it.
Switchboard’s own documentation has named Kamino, Jito, marginfi and Drift as users. Those are historical integration claims from a provider that was selling an oracle service, not a real-time inventory of active feeds on September 25. Checking each project’s current documentation reveals a more complicated picture. Jito’s Tip Router pages still describe Switchboard in their pricing flow; marginfi’s September technical upgrade adds paths designed to avoid that dependency. One document can be stale while another anticipates a migration. Neither substitutes for an inspection of live account configuration.
The earlier Switchboard funding round was $7.5 million in May 2024. The amount is useful background on the venture’s history, but it gives no measure of today’s protocol exposure. The relevant count is the number and value of live markets whose risk calculations still take data from a feed that cannot be reliably updated, and that count cannot be inferred from a customer logo.
A listed integration is not an active feed
Switchboard’s public introduction describes on-demand feeds: applications create or call the data they need, and a price is made available through Solana accounts. Documentation can identify where a protocol knows how to read a Switchboard feed. It may not identify which option a particular market currently selects. A software development kit may support an oracle type long after the last bank switches away from it. Conversely, a website may change while a live reserve retains its older oracle account.
Three levels of evidence need to be kept apart. First is a marketing or integration page, which shows a relationship existed. Second is a program’s supported configuration, visible in technical documentation or code. Third is the live configuration and recent update history of the actual market. Only the third can support a claim that a named market still relied on Switchboard at a given time. Even then, a backup source may be configured, so the impact of a stopped primary feed must be checked against the relevant fallback and freshness rule.
Consider marginfi’s protocol documentation. Its oracle table retains SwitchboardPull and venue variants among available setups. It says a caller must crank a Switchboard pull feed just before use. The same table lists Pyth push feeds and Scope accounts as other setups. A reader could mistake the continued Switchboard row for proof that every marginfi bank still uses it. The table describes supported types, not a complete list of which bank uses which feed today.
Marginfi’s separate Program 0.1.11 note is more current and more specific. It instructed developers to upgrade the SDK to at least version 2.8.0 before September 4, saying banks would begin moving to new oracle setups from that date. The release added nine variants that do not depend on Switchboard, including Kamino Scope feeds and exchange-rate based pricing for certain liquid staking and principal tokens. The note does not say every bank had migrated by September 25. It does show that a project publicly documented a route away from the threatened dependency before the shutdown announcement.
The migration carries a surprising second failure mode. Marginfi says older SDKs cannot decode a bank configured with one of the new oracle enum values. A single bank with an unsupported value can prevent Project0Client.initialize and bank reads, not merely an action involving that bank. In other words, changing an oracle can fix one infrastructure dependency while breaking an integrator that has not updated its software. Marginfi’s document tells integrators how to avoid the SDK problem; it is not evidence that any particular user suffered it.
Project 0 has described unified margin across Solana venues, including Kamino and Drift. Cross-protocol interfaces create another layer at which an oracle migration must be read correctly. The note about older SDK versions is concrete evidence of an integration hazard, without proving a failure in Project 0 or any other named app. A responsible audit would check software versions and live lending-bank configurations before claiming an outage.
Jito’s Tip Router still documents Switchboard
Jito Foundation’s Tip Router overview says Switchboard determines the relative weight of assets such as JitoSOL and JTO held in vaults linked to the Tip Router. The overview identifies an onchain Tip Router program, a node-operator client and a permissionless cranker. Its pricing documentation names Switchboard as the current oracle feed and describes backup weights when feeds are unavailable.
The documents place Switchboard in a specific job: pricing vault assets for weight calculations in a tip distribution and restaking system. They do not say that an unavailable Switchboard feed would automatically liquidate a Solana lending position. Jito’s pricing page describes a fallback mechanism, which weakens the simplistic claim that a support sunset necessarily makes all Tip Router operations stop. The exact fallback values, activation conditions and current live oracle accounts still need a current program-state check.
The Tip Router overview showed a last-updated marker of nine months ago when checked on September 25. That age changes how it can be used. It establishes a documented design and identifies where to ask a technical question. It cannot establish that the present program has the same feed configuration. Jito may have updated onchain accounts without revising the page, or it may still use Switchboard with a fallback. Without a recent transaction inspection or a current statement from Jito, a named live dependency remains unverified.
Jito’s public GitHub release notes for Tip Router refer to retrying Switchboard oracle gateways in keeper operations. A codebase containing such logic likewise demonstrates technical integration, not necessarily a dependency of every vault at the time of publication. Code can preserve a compatibility path for months. The live question is whether recent price update transactions target a Switchboard account used by a vault still carrying value, and whether that account advances after the support deadline.
The distinction is often lost when all oracle users are placed in a single list. Jito’s described calculation affects relative asset weights in a distribution system. A lending market’s described calculation determines collateral value and borrower health. Both consume price data, but their failure paths differ. An audit that counts logos would assign the same severity to fundamentally different uses.
Kamino’s Scope is an aggregator, not a provider label
Kamino Finance’s public Scope repository describes an onchain aggregator that copies values from multiple oracle accounts into one price feed and validates updates under preset rules. Its README says a feed supports up to 512 prices and that the association between an index and a token pair is not wholly stored onchain. A downstream program may point to Scope while Scope itself relies on other feeds for the selected asset. Seeing Scope in a bank configuration is thus a starting point for tracing the actual data source, not the end.
The September marginfi note lists Scope as an option that does not depend on Switchboard for the new setup it describes. That does not imply every deployment of Scope on every date excludes every Switchboard source. An aggregator can change its underlying inputs. A complete dependency check needs both the consumer’s selected Scope account and the source mapping used to populate its entry. Kamino’s repository supplies the architecture, not a timestamped inventory of current mainnet sources for every application.
Kamino has continued bringing institutions into its lending ecosystem. Galaxy opened two stablecoin vaults on the platform in September. The existence of new vaults shows why naming a whole protocol as exposed without checking its individual assets would be unsound. A USDC vault, a liquid staking token reserve and a tokenized equity market can use different oracle paths. We have not verified that Galaxy’s vaults use Switchboard, so they are not included in a count of affected positions.
Similarly, the older list of Kamino, Jito, marginfi and Drift in Switchboard’s introductory material does not tell us the distribution of exposure among them. A project may use an oracle only for one market, use it as a fallback, or retain code after switching live feeds. The only defensible unit of analysis is a specific market or vault and its configured feed at a specified time. Without that unit, claims about funds at risk are marketing arithmetic run backward.
A stale feed has more than one possible effect
The technical consequence of a feed falling behind depends on the consuming protocol. A lending program generally needs a price to determine collateral value and borrowing capacity. If it rejects an old value, an action may fail or a market may pause under its rules. If it accepts stale data, a borrower might transact against a price that no longer matches the market. A fallback source may keep the market operating but introduce a new update rhythm or confidence rule. The protocol’s documentation and onchain configuration decide which path applies.
Marginfi explicitly says Switchboard pull feeds need to be cranked before use. An integrator must therefore supply a fresh update as part of its transaction path. Pyth push feeds, by contrast, are described as being kept fresh through Pyth’s infrastructure. Scope uses an aggregated account value selected by a configured entry index. Moving between these types changes the accounts a transaction needs and the code that checks them. The September SDK warning is one visible example of those changes reaching application software.
For Jito Tip Router, the public docs describe backup weights for unavailable feeds. Whether those backups preserve accurate reward allocation through a sustained outage is a question for live configuration and Jito’s operators, not something a documentation sentence resolves. If a feed keeps updating through independent node operators after the company stops support, no fallback may be triggered immediately. If updates cease but the backup is active, operations may continue with a different pricing method. These are conditional paths, not a prediction of the system’s present state.
An unrelated oracle incident led to liquidations on Vesu earlier in September. It illustrates that incorrect pricing can have economic effects, but it is not evidence of an incident at Switchboard, Jito or marginfi. A shutdown notice should not be turned into a liquidation claim by analogy. The sign of an actual event would be stale account timestamps, failed transactions, a protocol pause or identified losses, none of which has been shown here for the September 25 deadline.
Solana’s move to 250 millisecond slots changed the pace at which blocks are produced, but it did not guarantee that an external price source updates. Faster slots can carry a new price sooner when one exists. They cannot manufacture a price when the node supplying it stops. A protocol’s freshness test may be measured by slot, time or another rule, so a change in the network clock may alter how developers interpret old feed configurations.
Who bears the migration work?
The oracle operator publishes or coordinates data, but the consuming protocol chooses the account its program reads and the limits it places on that price. A lending protocol can require governance or an administrator to change oracle addresses for its markets. Its front end and third-party integrators then have to construct transactions with the right additional accounts. Users may only notice a rejected borrow or a paused market, long after the operator and protocol have made their technical decisions.
An operator ending support does not necessarily have the power to rewrite a customer’s program configuration. The Switchboard notice urged users to migrate because integration owners must act. Projects should be assessed by the addresses and account updates they control. If an application already moved to Pyth before September 19, the later support deadline has no direct effect on that market. If it still selects a Switchboard feed and has no working backup, the feed’s behavior after September 25 is the concrete issue.
The strongest opposing reading of the shutdown alarm follows from marginfi’s own September note and Jito’s documented backup. Applications can design redundancy or move ahead of a vendor exit; the code and documents show mechanisms for doing so. Switchboard’s on-demand model can leave some feed infrastructure running independently even if the core contributor has stopped support. The notice did not publish a verified schedule at which every account would halt, and we found no primary evidence establishing such a universal cutoff.
There is a different kind of continuity question for a protocol that made its own fallback. A backup price can prevent a total stop while pricing an asset less frequently or with a different source set. For a reward distribution process, a temporary backup weight may keep epoch accounting moving, although the allocation may then rely on the backup’s assumptions. For a lending market, the fallback could change the price used in a health check. These are not claims about current Jito or marginfi settings. They show what a maintainer must disclose before users can judge whether a migration is complete in operational terms, not merely whether transactions still execute.
A provider wind-down can have delayed effects as well. Code written to request on-demand prices may succeed while an independent gateway answers, then fail when that gateway is retired or its operators stop updating a specific asset. An observer needs several post-deadline timestamps, not a single successful transaction, to infer continued service. The same discipline applies to a failed transaction: one user’s error may arise from a stale SDK or insufficient account input instead of an unavailable oracle. Marginfi’s migration document supplies an explicit example of a software decoding failure that could otherwise be mislabeled as an oracle outage.
There is a limit to that reassurance. A fallback described nine months earlier needs validation against current state, and a migration option described in September is not proof every bank took it. The two documents supply credible reasons not to assume catastrophe, while leaving a measurable gap. The fair conclusion is narrower than both the promotional and alarmist versions: public documents identify candidate dependencies and escape routes; a current market-by-market configuration audit is needed to establish any remaining exposure.
The live inventory is still the missing document
The original reporting here compares Switchboard’s list of four prominent integrators with current primary documents from Jito, marginfi and Kamino. It yields two verified documentary findings. Jito’s older Tip Router documentation names Switchboard for vault pricing and a fallback for unavailable feeds. Marginfi’s September 0.1.11 note describes nine new setups independent of Switchboard and warns of a separate SDK break if integrators do not upgrade. Kamino’s Scope repository explains why an aggregator label alone cannot identify every upstream data source.
The work does not produce a count of live unmigrated feeds, user funds exposed or an outage at any named protocol. The available public pages do not contain a synchronized September 25 snapshot of all oracle accounts, latest successful updates, fallback settings and amounts supported by each market. Claiming a specific dollar total from protocol TVL would be indefensible, because the whole protocol’s assets do not necessarily share the same oracle. The precise headline question remains open at the live-account level.
A proper count would use the market as the row, not the protocol. For each active lending bank, derivative market or reward vault, the auditor would record its program address, selected oracle type, oracle account, backup source if any, latest successful price update, maximum permitted age and the value of positions actually dependent on that particular price. Duplicate markets that share one oracle account should not be counted as distinct feeds; one market using two independent oracles should not be counted as wholly dependent on either without reading its fallback logic. The timestamp of the market configuration matters because an administrator could change a feed after the observation.
This method explains why even a true statement such as a protocol supported 550 feeds in the past is insufficient for the present question. A feed can exist without an active borrower, can have a price update without a consuming market, or can be referenced only in dormant code. A count of feed accounts measures infrastructure. A count of configured markets measures dependency. A count of positions and collateral actually touching those markets measures economic exposure. None is interchangeable with total assets deposited in all products run by a project.
There is a further verification step when a source is an aggregator. The consumer may identify a Scope account and entry index, while the Scope mapping points onward to one or more providers. An update in the Scope account after September 25 proves an aggregator produced a value, but it does not by itself prove Switchboard continued to supply the underlying price. The investigator needs the selected entry and source configuration for that update. Kamino’s repository notes that token-pair labels are not entirely stored onchain, so external configuration or maintainer documentation may be needed to map an index to its asset. Where that mapping is unavailable, the result should be recorded as unknown, not silently attributed to Pyth or Switchboard.
What to watch
- Market oracle addresses: Compare each active bank or vault’s configured feed with the documented Switchboard accounts.
- Price update timestamps: Check whether an identified feed continues publishing fresh values after September 25.
- Fallback configuration: Look for the source and freshness limit used if a primary feed falls behind.
- Recent program transactions: Check whether borrowing, settlement or tip distribution still completes for the affected market.
- Dated maintainer updates: Look for a named migration, market pause or remaining dependency, supported by an account or program address.
Record the observation time for each check; a screenshot without a block or timestamp can quickly become stale.
Marginfi’s upgrade note states that a bank using a new oracle enum value can make an older SDK fail to initialize its client, even if a user does not interact with that particular bank. The instruction to use SDK version 2.8.0 or later was published ahead of September 4’s migration start, three weeks before Switchboard’s support deadline.
FAQ
When did Switchboard say support would end?
The shutdown announcement was made on September 19, 2026, and identified September 25 as the end of existing technical support. The notice deprecated implementations immediately.
Did all Switchboard oracle feeds stop on September 25?
The support deadline alone does not establish that every onchain account stopped updating. Current transaction and feed timestamps are needed to make that claim.
Does Jito still use Switchboard?
Jito’s Tip Router documentation still names Switchboard in vault pricing, but its overview is marked as last updated nine months earlier. The pages do not prove the live September 25 configuration.
Did marginfi migrate off Switchboard?
Marginfi’s September upgrade documents nine new oracle setups that do not depend on Switchboard and says banks began moving from September 4. It does not state that every bank completed a migration.
Why can an oracle migration break an SDK?
Marginfi says older SDKs do not recognize the enum values used by its nine new setups. A bank configured with one can make an old client’s initialization fail; version 2.8.0 or later supports the variants.
Is Kamino Scope independent of every external oracle?
Scope aggregates values from other oracle accounts. Its presence in a consumer’s configuration does not identify every upstream source without examining the specific entry mapping.
How can users check whether a market is affected?
The market’s configured oracle account, latest update and fallback settings provide a stronger answer than a historical provider list. Protocol announcements can confirm whether a specific market has migrated.
Have losses been verified from this shutdown?
No losses at a named protocol were verified for this feature. An earlier incident at another protocol cannot prove one occurred here. This is educational analysis, not investment advice.
Disclaimer: This article is for information and educational purposes only and does not constitute financial or investment advice. Figures reflect regulatory filings and reporting available at the time of writing and change with each disclosure. Nothing here is a recommendation to buy, sell, or hold any security or asset. Always do your own research. Information is accurate as of September 25, 2026.

A wallet linked to Hyperliquid Strategies has purchased 494,200 Hyperliquid (HYPE) tokens, worth $45.8 million.
The latest buy extends a month-long run. The token behind that treasury has also sharply outpaced Bitcoin (BTC) and Ethereum (ETH) this year.
HYPE Did the Heavy Lifting in Fiscal 2026
According to Lookonchain, the wallet has bought 5.51 million HYPE, worth $476 million, over the past month. That averages 183,574 tokens, or $15.86 million, a day.
The firm now holds 35.1 million HYPE worth about $3.2 billion. That is up from roughly 29.3 million tokens when its fiscal year closed on June 30.
Hyperliquid Strategies booked $305.5 million in net income for the fiscal year, largely from HYPE price gains, its full-year profit report showed. Unrealized gains on its holdings came to $709.9 million, per the company’s results.
Follow us on X to get the latest news as it happens
HYPE Outruns Bitcoin and Ethereum
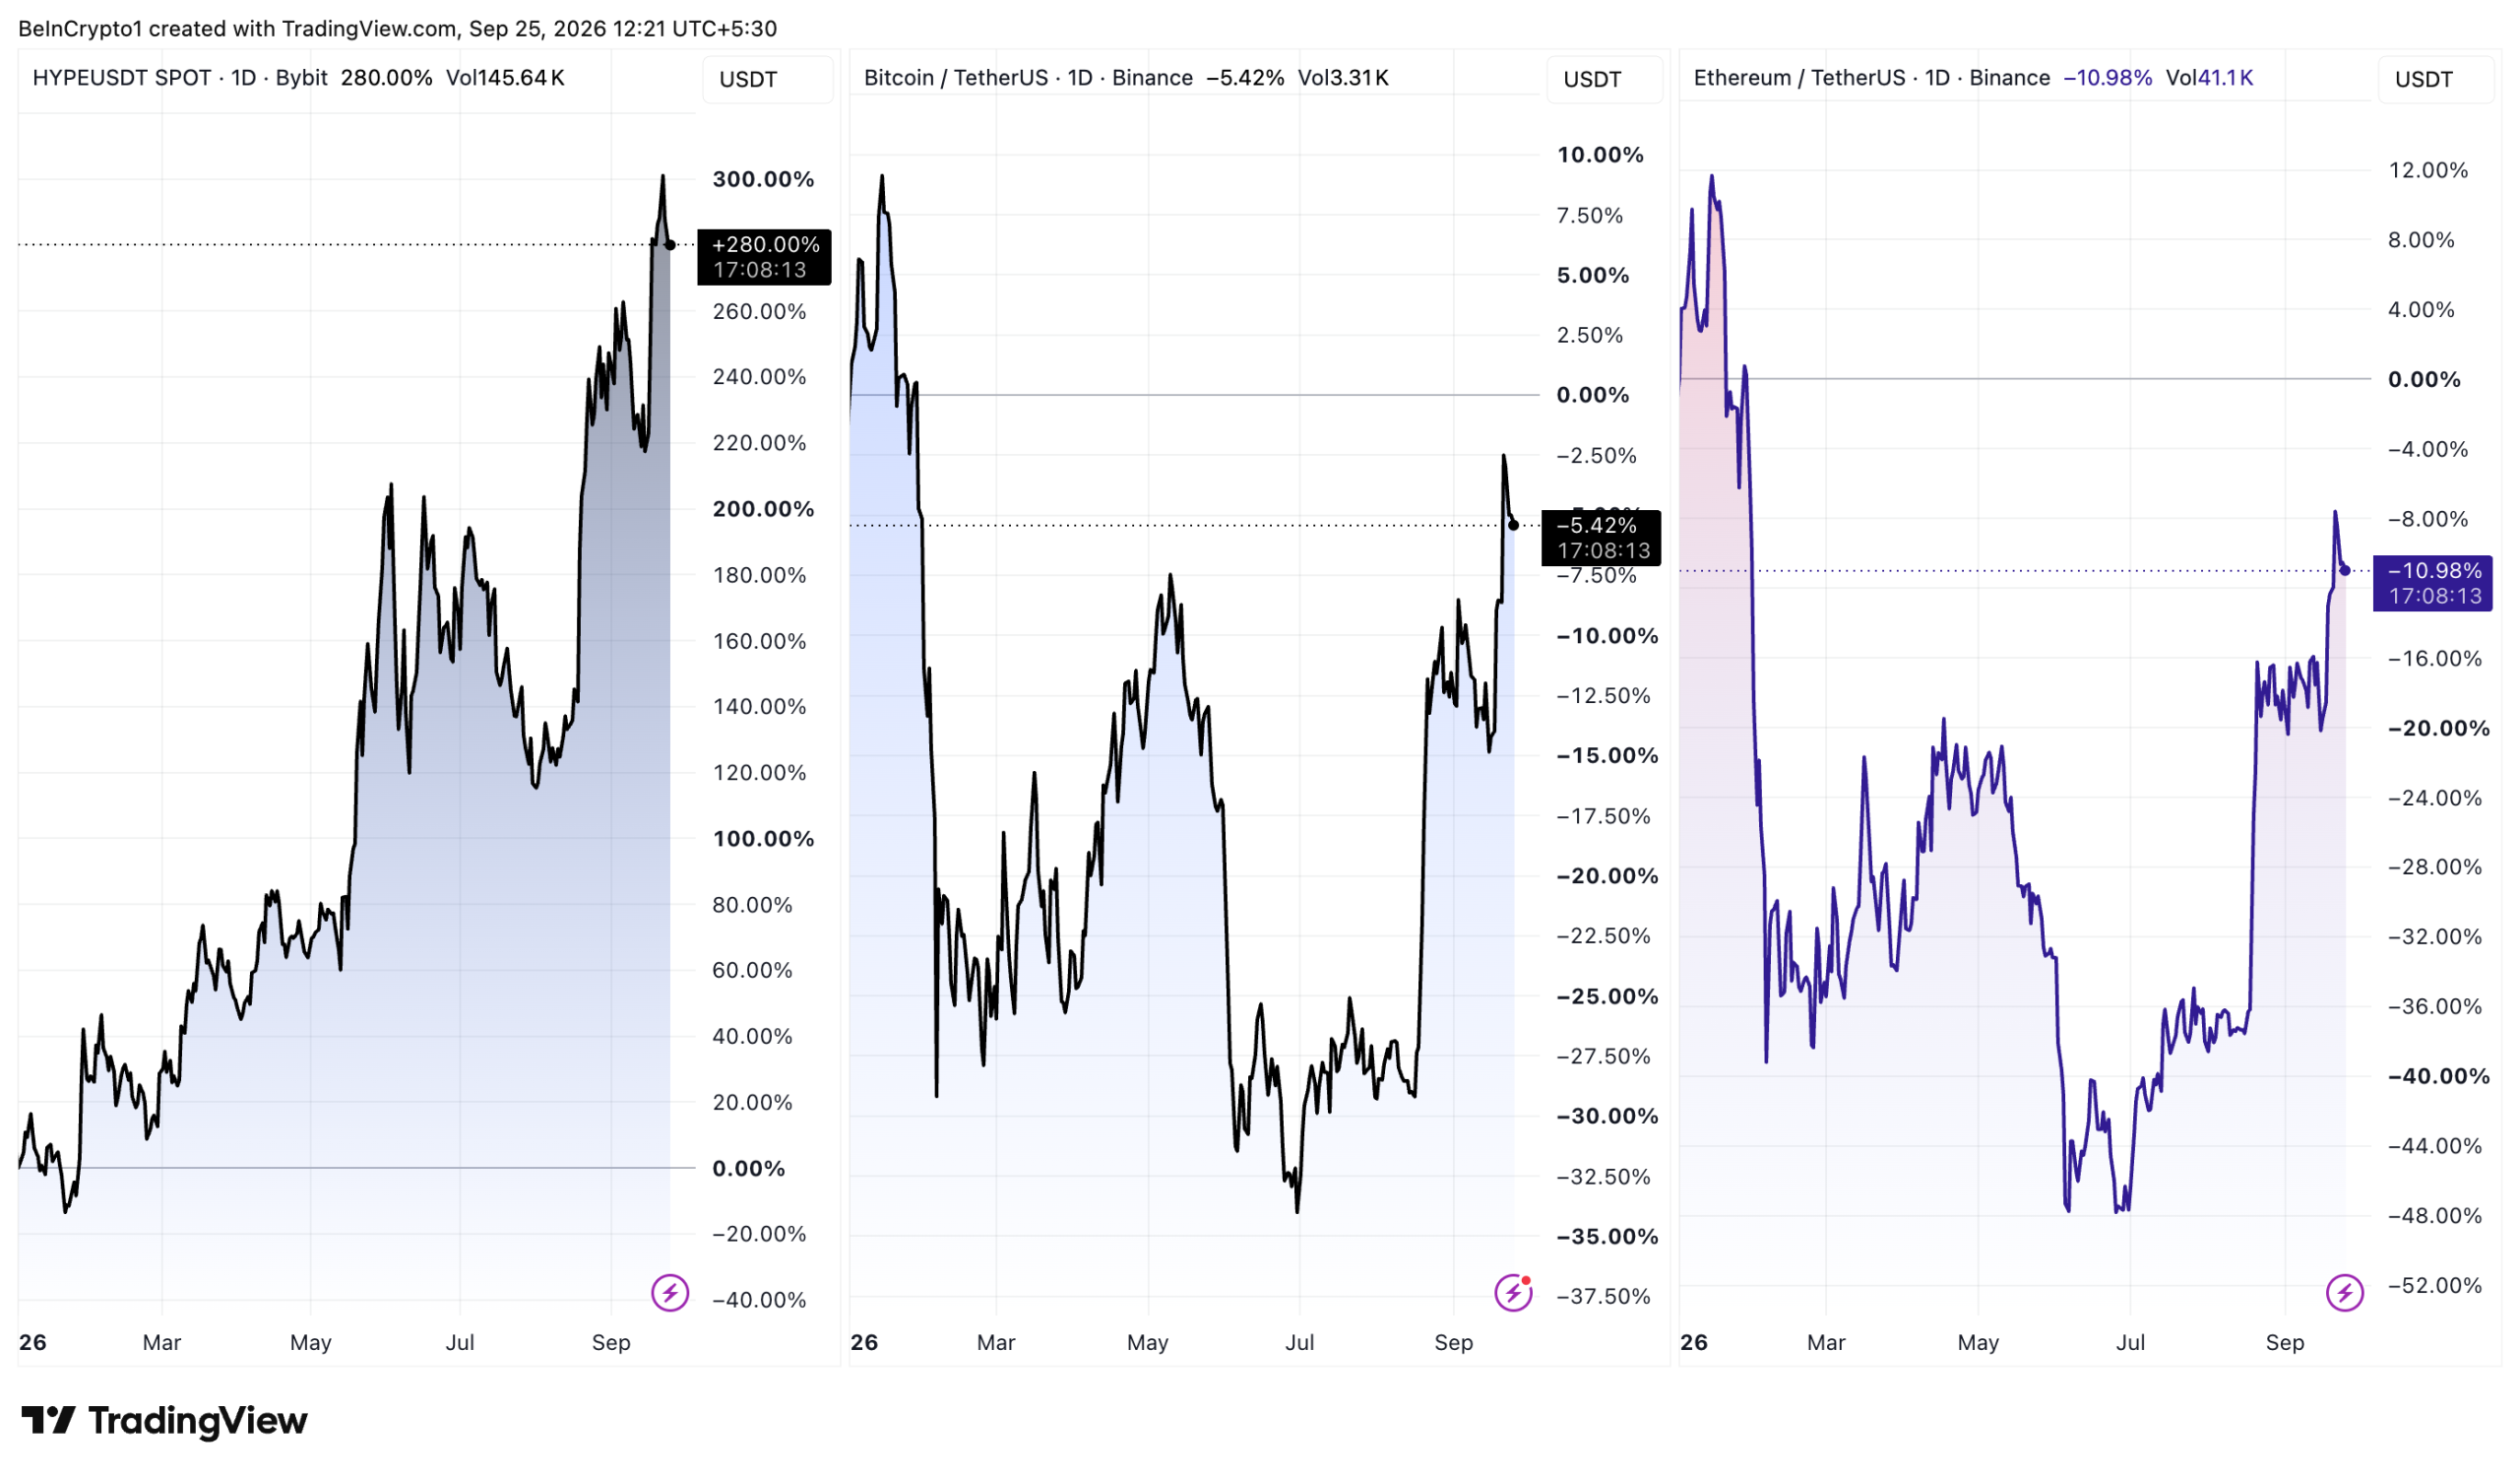
The accumulation has come during a strong year for the token. HYPE has climbed 280% so far in 2026, according to market data.
In contrast, Bitcoin has lost 5.42% this year, while Ethereum is down 10.98%.

Artemis data shows how that split has played out for treasury firms. Hyperliquid Strategies holds $2.7 billion in unrealized gains, second only to Strategy. Ethereum-focused BitMine sits at the other end with the largest unrealized loss.

Shareholders are also paying a premium for that exposure. DWF Ventures’ latest report places Hyperliquid Strategies among 4 of the top 20 treasury stocks trading above their holdings.
Its market-value-to-net-asset-value ratio stood at 1.17x on DWF’s count. Since July, the stock has outperformed HYPE by 31%. However, DWF found the token stayed the better bet over periods longer than 3 months.
Subscribe to our YouTube channel to watch leaders and journalists provide expert insights
The post Hyperliquid Strategies Keeps Buying the Token That Drove Its $305.5 Million Profit appeared first on BeInCrypto.
DoubleZero has launched a dedicated market data feed for Hyperliquid, aiming to give professional trading firms a more reliable and complete view of the decentralized exchange’s order book. The service delivers Hyperliquid’s market data over fiber, rather than relying on the exchange’s public APIs.
According to DoubleZero, the feed provides an ordered, continuous stream of order book data for market makers, quantitative traders, and proprietary trading firms that depend on consistent update frequency and depth.
Key takeaways
- DoubleZero’s Hyperliquid feed distributes full order book data via a dedicated fiber network instead of public APIs.
- The service supports Hyperliquid’s native perpetual futures and also markets run through trade[XYZ], a venue using Hyperliquid infrastructure for asset-linked perpetuals.
- DoubleZero says public API changes have reduced both the frequency and the depth of order book updates available to external consumers.
- The initiative broadens DoubleZero’s “Edge” market-data offering, which already includes Solana and the prediction market Kalshi.
A fiber-based order book for professional traders
For firms that need a full and timely order book, pulling liquidity data from a public interface can introduce inconsistency. DoubleZero’s new feed is designed to address that by providing market data as a continuous stream, with ordering guarantees intended to help automated systems interpret changes quickly and predictably.
DoubleZero positioned the launch around a practical problem: before this release, companies seeking a complete view of Hyperliquid’s order book typically had to reconstruct it themselves from public API responses or run their own Hyperliquid nodes. DoubleZero now offers a third path—an outsourced, purpose-built distribution layer.
The company also attributes the need for a dedicated feed to changes in Hyperliquid’s public APIs. DoubleZero said those updates have lowered the cadence and reduced the depth of information available through the public routes, making it harder for data consumers that require more frequent, comprehensive updates.
What’s included: native perps and Hyperliquid-powered markets
DoubleZero said the feed covers Hyperliquid’s native perpetual futures markets, alongside markets operated by trade[XYZ]. In this structure, trade[XYZ] provides perpetual contracts linked to assets including oil, gold, and silver, using Hyperliquid’s underlying infrastructure.
DoubleZero added that the feed was developed in collaboration with validator operators and ecosystem partners, including Hyperion DeFi, MAVAN, and Kinetiq. That matters because fiber-based delivery depends not just on software integration but also on reliable distribution pathways across network participants.
Why this matters: convergence with traditional exchange data workflows
The launch also highlights a broader trend in onchain market infrastructure: professional trading firms are increasingly looking for data distribution patterns similar to those used by large traditional exchanges.
Hyperion DeFi CEO Hyunsu Jung told Cointelegraph that major exchanges such as CME and Nasdaq distribute professional market data over dedicated networks. The point is to deliver a consistent stream of ordered information at high speeds to automated trading systems.
Jung argued that Hyperliquid’s market data can now be consumed through a similar model. In his words, the approach is effectively “publish once, distribute simultaneously over dedicated fiber,” echoing the logic behind how institutional infrastructure treats market data as a specialized distribution problem.
That said, Jung emphasized there are meaningful differences. Traditional exchanges allow firms to reduce latency further by placing trading infrastructure close to the venue’s execution systems. Hyperliquid, by contrast, executes trades onchain, which changes where latency is incurred and how it can be optimized.
He also noted that physical geography still matters. A firm based in Tokyo, for example, will maintain a speed advantage over one in New York regardless of how the data is delivered—an important reminder that fiber distribution can improve consistency and reduce certain bottlenecks, but it does not eliminate real-world network and distance effects.
Jung summarized the relationship as not a claim that Hyperliquid is becoming “CME,” but rather that onchain markets are borrowing the market-data infrastructure layer that professional firms already rely on in conventional finance.
Expanding “Edge” market data beyond crypto venues
DoubleZero’s Hyperliquid feed is the third venue available through its Edge market-data service. The company previously deployed similar services for Solana and for Kalshi, a prediction market. With this expansion, DoubleZero is effectively positioning Edge as a cross-venue distribution platform aimed at professional-grade data consumption.
For market makers and quantitative firms, the practical value of an Edge-style service is straightforward: fewer gaps in update streams, less reliance on reconstructing order books from partial public feeds, and a single distribution layer designed for automation.
For the broader Hyperliquid ecosystem, it may also signal a shift toward treating market data as critical infrastructure in its own right. Instead of forcing each data-heavy firm to build bespoke ingestion and normalization systems, venues can increasingly support dedicated distribution pipelines that align with how trading desks already operate.
Investors and traders will likely watch next how widely institutions adopt the feed and whether other onchain venues respond with similar dedicated distribution layers, particularly as more market participants push for predictable, ordered depth updates beyond what public APIs can provide.
Cointelegraph is committed to providing independent, high-quality journalism across the crypto, blockchain, AI, and fintech industries.
All news, reviews, and analyses are produced with full journalistic independence and integrity. For more details on our standards and processes, please read our Editorial Policy.
Crypto World
Mahershala Ali Balances Tenderness and Swagger in ‘Your Mother Your Mother Your Mother’
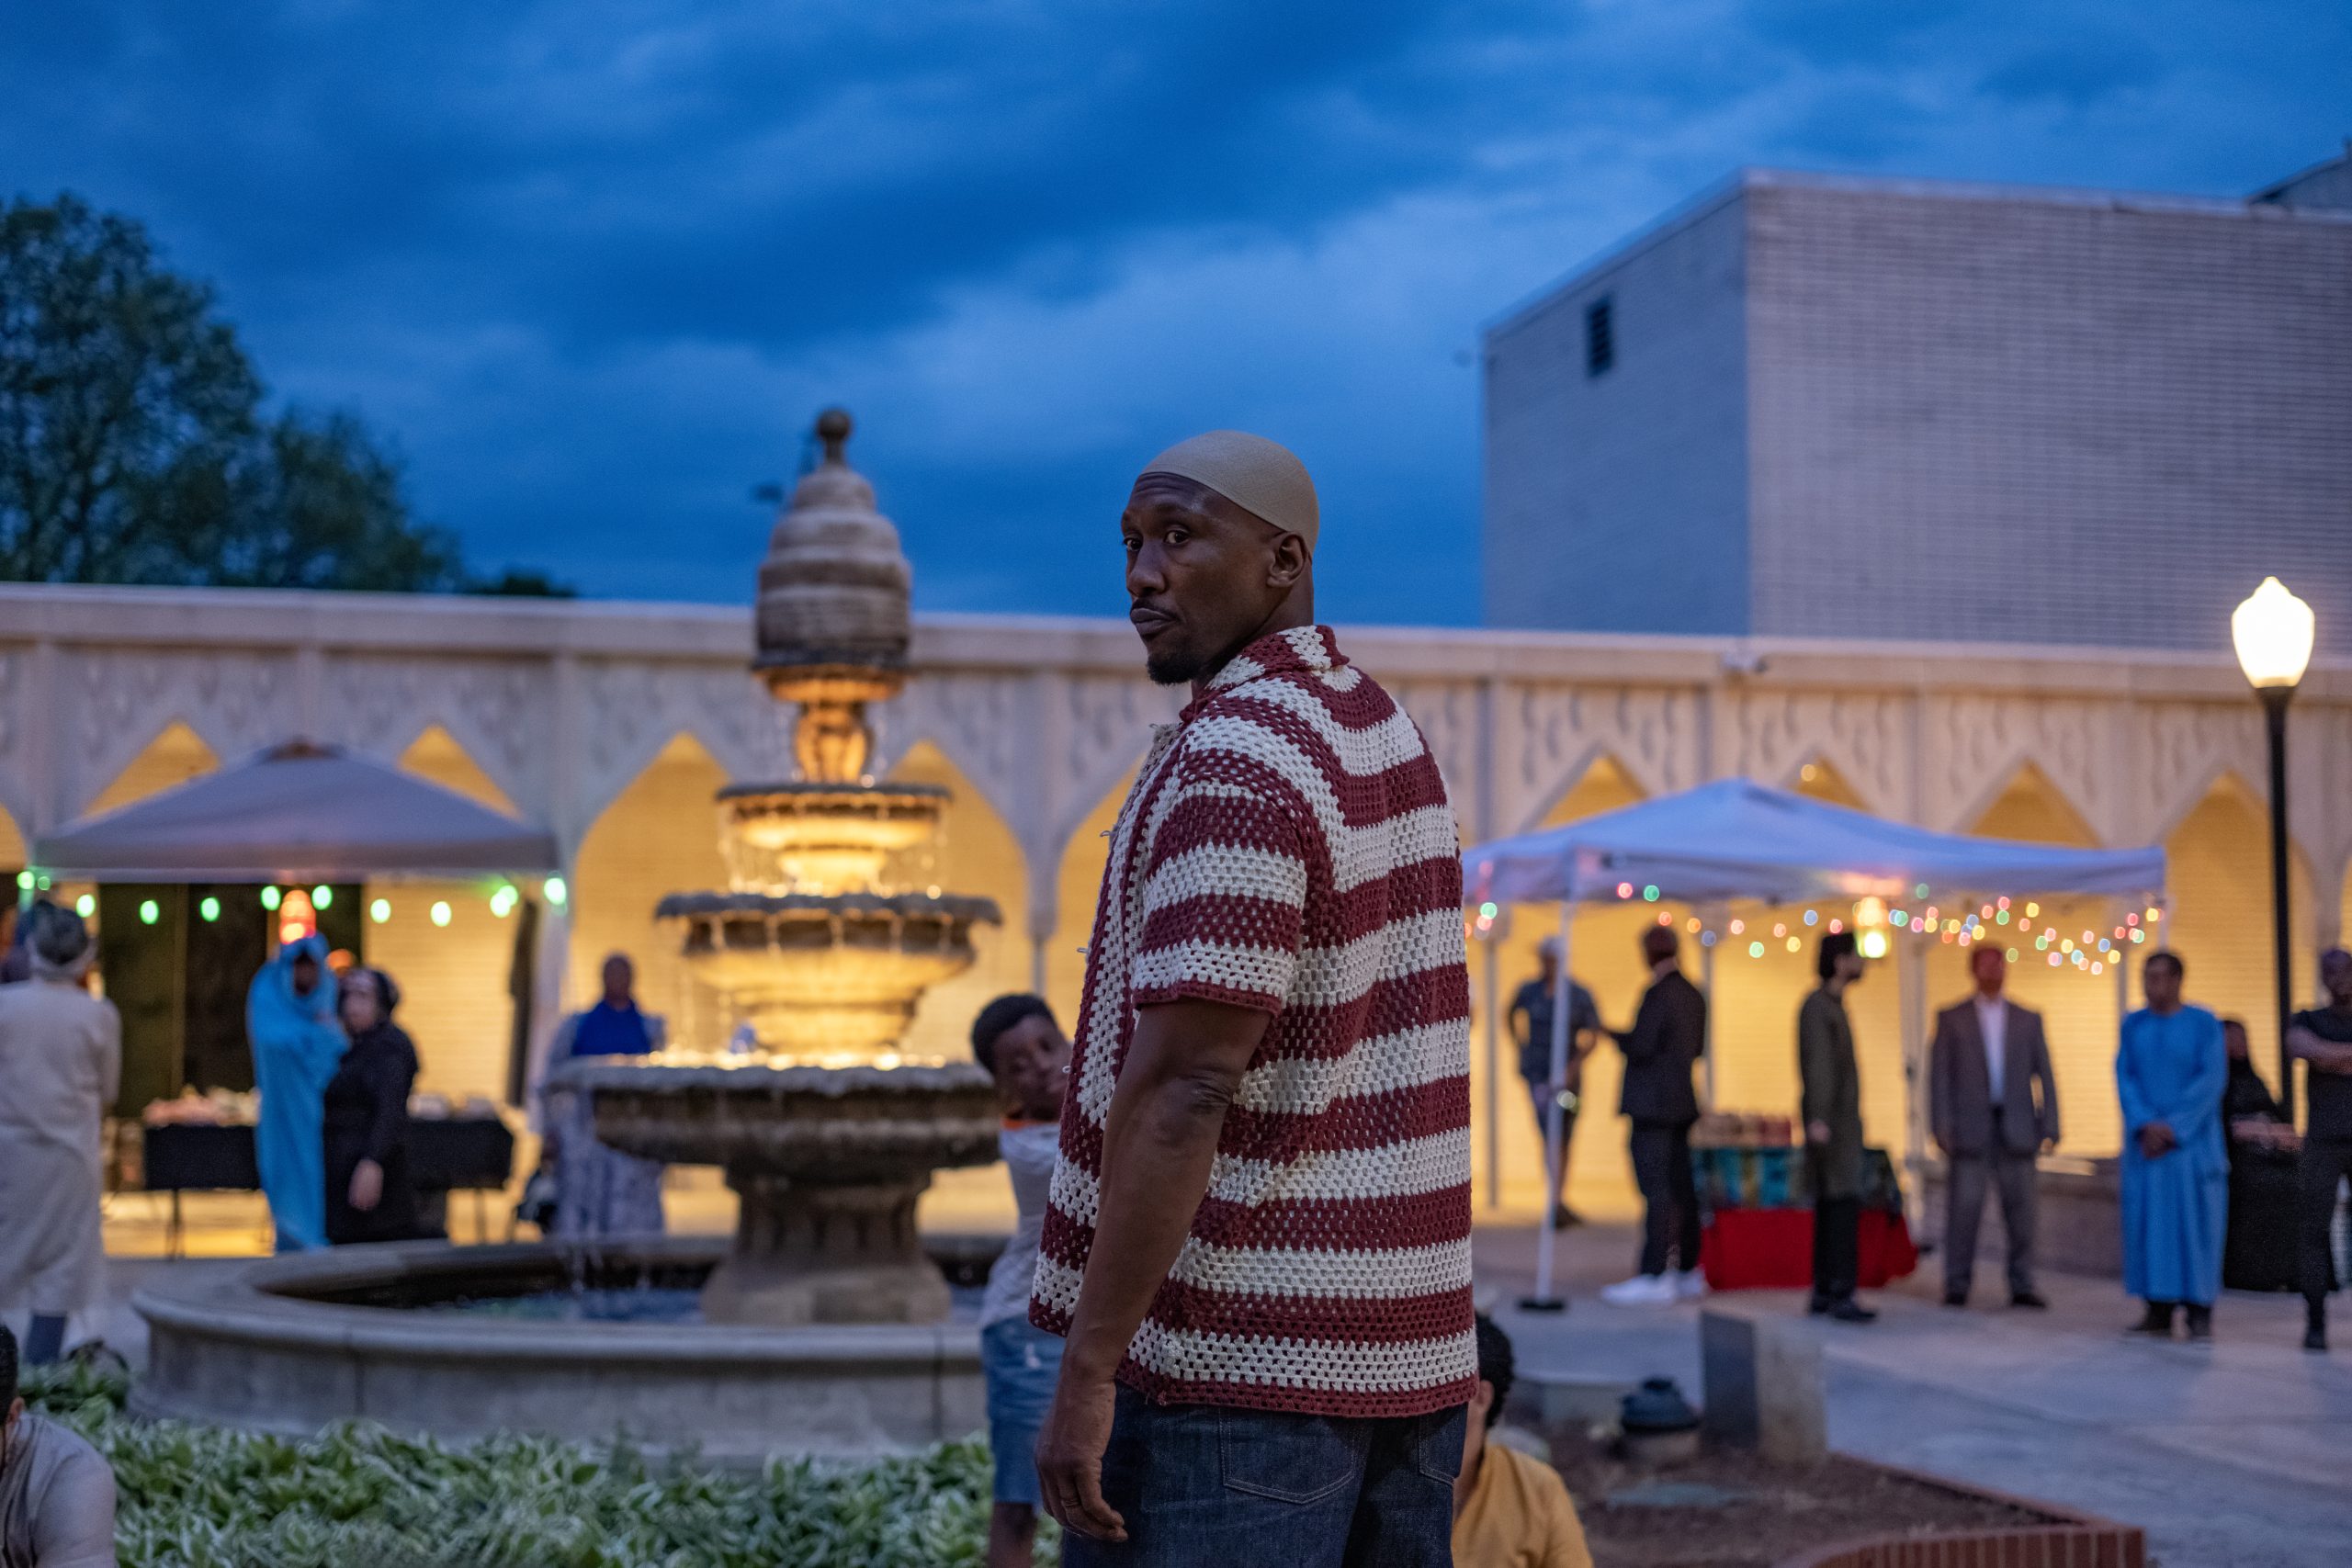
No one really wants to talk about religious rage, the complex resentment when you feel your God has abandoned you: We like our faith to be tidy and count-your-blessings clean, not clouded with doubt and fury. In writer-director Bassam Tariq’s action thriller Your Mother Your Mother Your Mother, Mahershala Ali plays Latif, a Houston, Texas, hit man who’s also, ostensibly, a devout Muslim: He strives to be a man of faith even as he’s breaking bones (and more) in the name of Allah. Then his wife dies suddenly, making him a single dad with three kids to care for, teenager Fatiha (Adia), her younger brother Qadir (Jahleel Kamara), and an infant, Aziza, who can’t tolerate baby formula; only her mother’s breast milk will do, and supplies are quickly running out. That’s a workaday problem Latif has got to solve, and prayer takes a backseat to his feelings of betrayal. “You take her from me,” he rages in voiceover, “and you expect me to bow down to you?”
A crisis of faith and a desperate search for breast milk: As plot drivers go, that’s a pretty novel combination, but Tariq and Ali pull it off here. The tone is equal parts sacred, profane, and comical. Tariq opens the film with a skull-crushing action sequence in which Latif, dressed in swirling robes, beats the heck out of a baddie in a public bathroom; the sequence is exhilarating and brutal, not least because Ali, wrapped in quasi-Samurai warrior garb and wielding a menacing knife, makes such a dashing, beguiling figure. When his wife dies, he realizes his priorities must shift toward his family, but he can’t free himself from his longtime boss Mike (Laith Nakli), who has a special job for him: Mike’s porn-king nephew Hatty (Abubakr Ali) is being harassed by a (Christian) religious fanatic, Pastor Hwan Yoon (John Cho). Can Tariq take care of that? He can—but meanwhile, baby Aziza is yowling with hunger, and it turns out that a sex worker formerly in Hatty’s stable, Tiffany Boone’s Fugazi, is lactating and has a bountiful supply of what baby needs. If Latif’s life of spirituality mingled with bloody violence seemed complicated before, it has now entered the realm of the surreal.
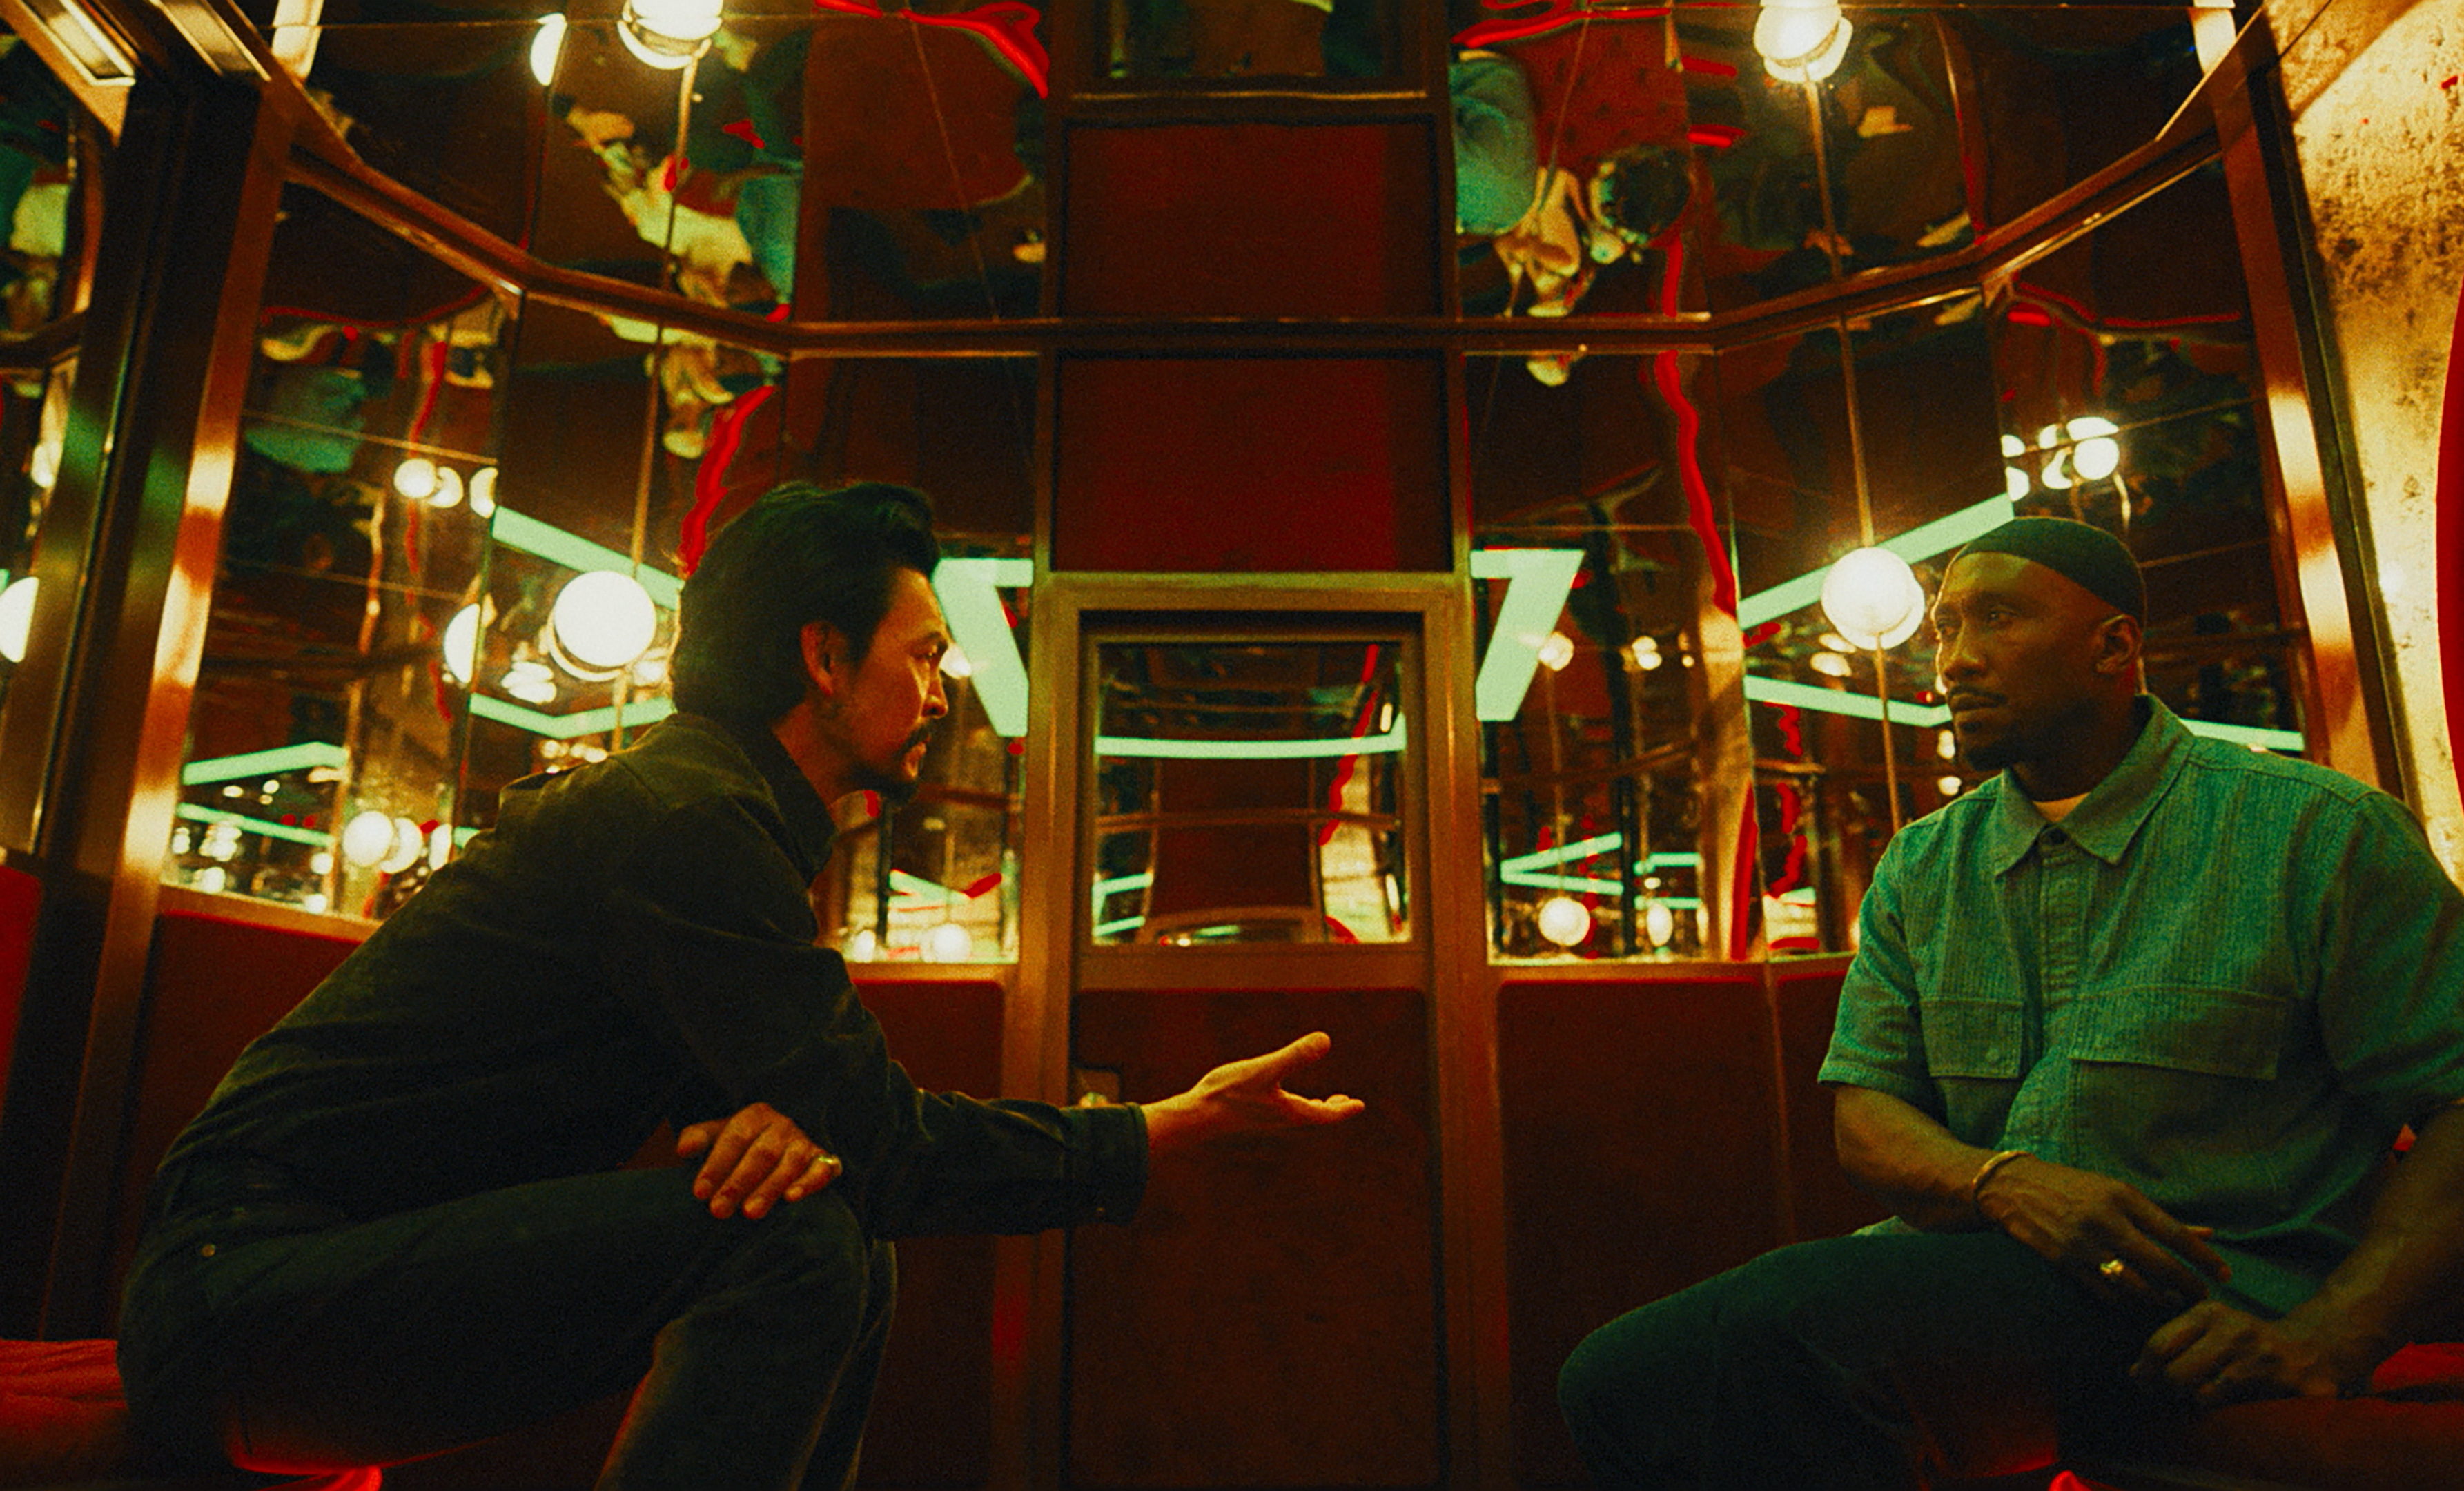
Your Mother Your Mother Your Mother is most entertaining when it indulges its tawdry side. Hatty, with his tacky sex mansion and bevy of “halal-certified” cuties, is a particularly clever invention, and Cho, decked out in spangled western shirts and sporting a row of gold teeth, appears to be having a blast as a sleazy operator who’s more interested in power than in Jesus. The action sequences are sharp and swift. In his quest for milk, his tiny daughter strapped snugly to his chest, Ali’s Latif is a new kind of action hero. (Some of the movie’s visuals echo the climactic baby-rescue scene of John Woo’s magnificent Hard Boiled, in which Chow Yun Fat descends the wall of a multi-story hospital building while fending off a hail of bullets, even as he cradles a gurgling mite with one arm.)
But Your Mother Your Mother Your Mother also tangles with complex issues of faith. It’s clear that Latif’s daughter Fatiha, who breaks fast when she shouldn’t and has a crush on one of the family’s young Mormon neighbors, is straying from the path. But the movie doesn’t judge her for it. The suggestion is that doubt is part of faith—you can’t have the second without the occasional tension of the first—and even Latif will have to face that crisis.
The Pakistani-born Tariq previously co-directed (with Omar Mullick) the 2013 documentary These Birds Walk, and he was one of the filmmakers in talks to direct the ill-fated Marvel reboot of Blade, with Ali set to star. In a world where blessings, even mixed ones, are sparse, it’s not a terrible thing that Ali was saved from potentially being chewed up by a Marvel vehicle; he’s a superb actor who deserves better, and Your Mother Your Mother Your Mother gives him plenty to work with. The movie’s title refers to a hadith in which a man approaches the Prophet Muhammad and asks, “To whom should I give the best of me?” The prophet’s answer, so emphatic he repeats it three times, is “Your mother”; only when the man asks the question for a fourth time does the prophet respond, “Your father.” As Latif, Ali captures the spirit of the movie’s title: he seems powered by a contradictory blend of male privilege and humility. Early on, he sees, as if for the first time, the little notes his wife had left all over the house, reminders for herself and the kids of all the minuscule things that need to be taken care of in a household. She had handled all these tasks quietly, and seemingly with ease. Now those things—essentially women’s work—are left to him, including sustaining an infant who needs something he can’t provide.
As Latif, always spoiling for a fight, Ali swaggers through the film. But there’s another man inside, a gentle, God-fearing one, and that’s the one you see in the somber beauty of Ali’s eyes. Out of necessity, Latif needs to reconcile with his feminine side. Suddenly, he’s both father and mother, and he finds that filling the role of the latter is the greater challenge. It’s the tenderness he carries within that makes Your Mother Your Mother Your Mother both distinctive and thought provoking. The thrills are just a fringe benefit.
Bitcoin price is hovering around $86,500 with a sharp 13.90% run over the past week, which keeps its bullish prediction intact. The rebound is tied directly to a reversal in institutional demand that few saw coming just two months ago. There’s a second data point buried in the flow numbers, though, that changes how traders should read this rally.
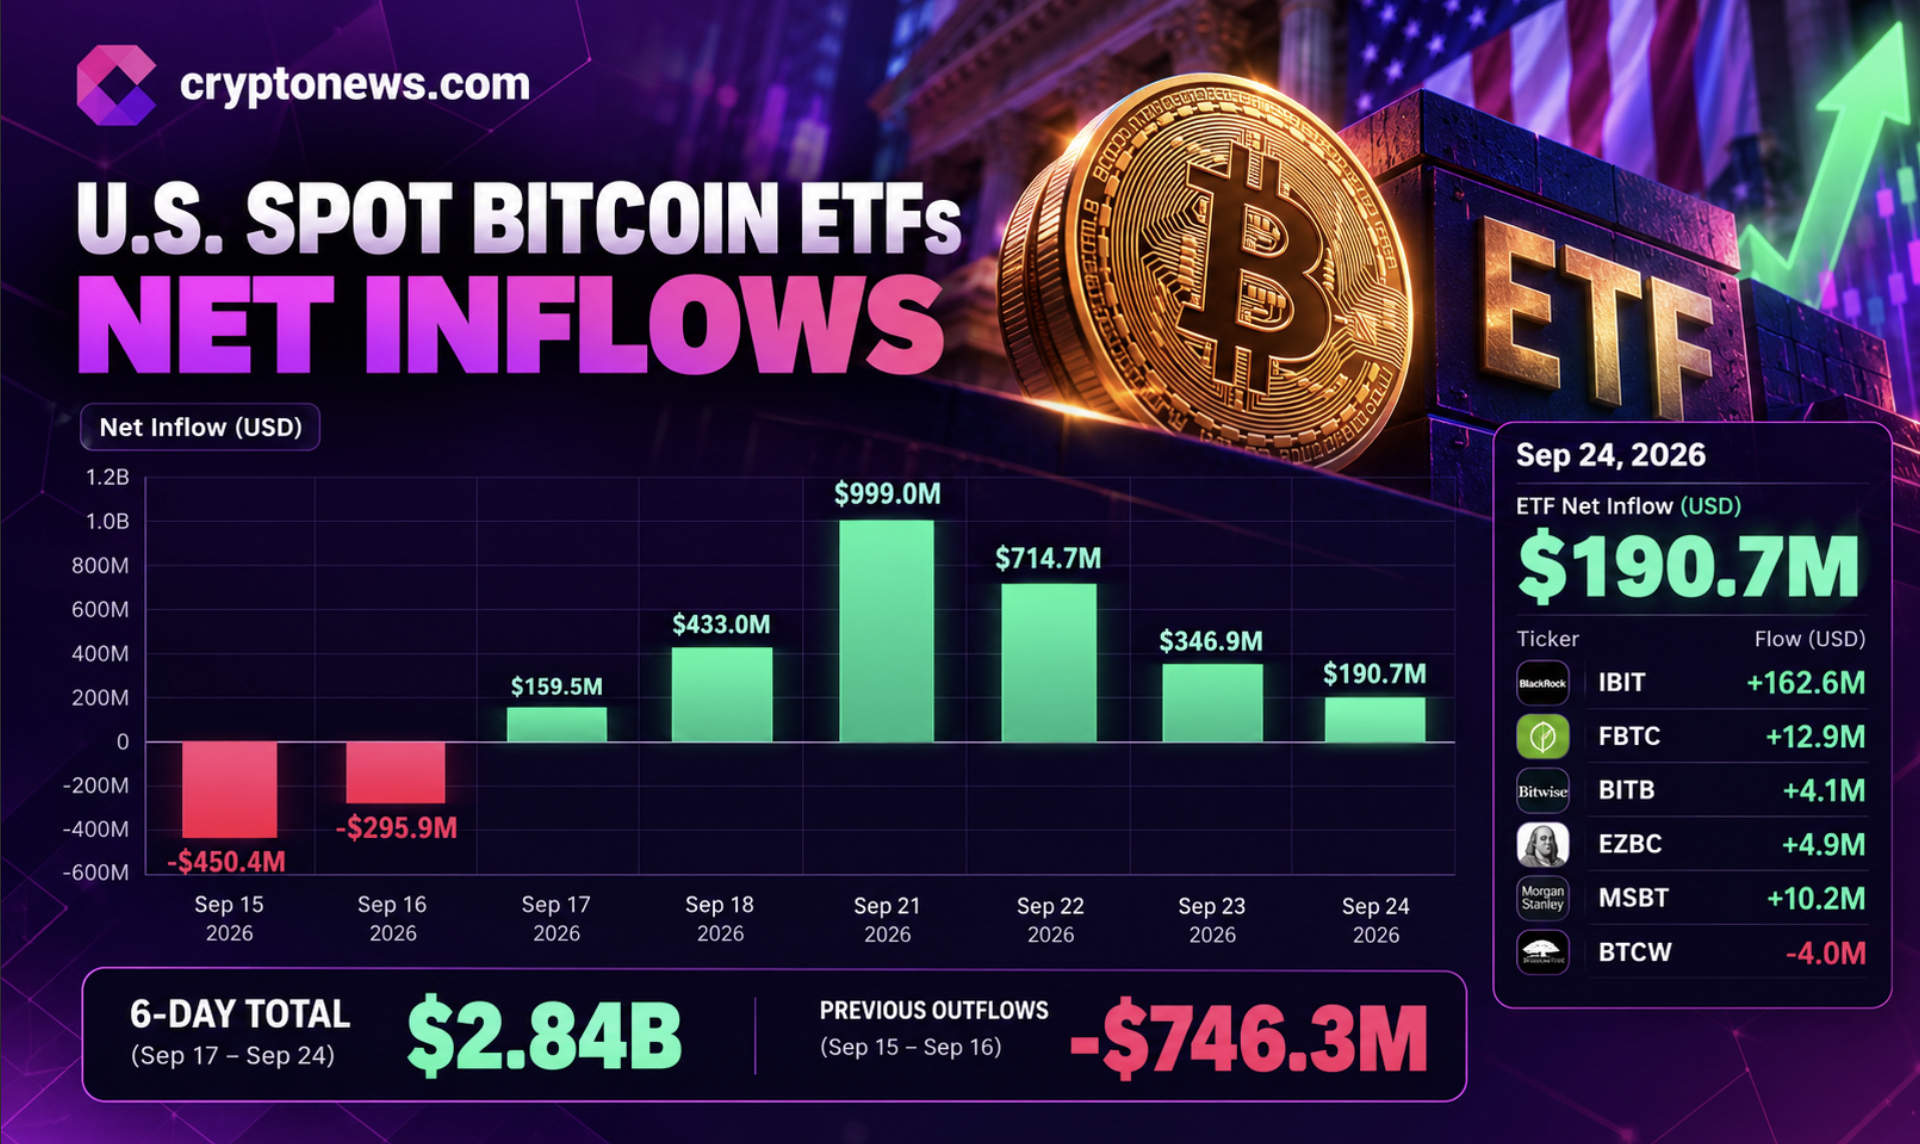
U.S. spot Bitcoin ETFs recorded $190.7 million in net inflows on September 24, extending their winning streak to six consecutive trading sessions. BlackRock’s IBIT led with $162.6 million, while Fidelity’s FBTC added $12.9 million and Morgan Stanley’s MSBT brought in $10.2 million. Bitwise’s BITB added $4.1 million, and Franklin Templeton’s EZBC gained $4.9 million, partly offset by a $4 million outflow from WisdomTree’s BTCW.
The latest inflow brought the six-session total to roughly $2.84 billion, following $159.5 million on September 17, $433 million on September 18, $999 million on September 21, $714.7 million on September 22, and $346.9 million on September 23. That marks a sharp reversal from the $450.4 million and $295.9 million outflows recorded on September 15 and 16.
Cumulative flows for the year have swung from a $5.8 billion deficit in mid-July to $800 million net positive today. This is a $6.6 billion turnaround in just over two months. The shift forces short-term traders to rethink positioning, and it sets up the technical picture worth breaking down.
Discover: The Best Token Presales
Bitcoin Price Prediction: Can BTC Hit $90,000 This Week?
Bitcoin is consolidating in the mid-$80,000s after last week’s sharp move, with price action bouncing between $84,000 and $86,500 depending on the session. Volume has stayed elevated, with the $3.74 billion ETF turnover on September 23 alone signaling this isn’t a low-liquidity drift.
Bitcoin is also trading above both its 20-day and 50-day moving averages, and the MACD remains bullish, which on-chain accumulation data suggests is being reinforced by whale buying rather than pure ETF flow.

For now, the immediate battle is at the $85,000–$86,000 resistance. Clear that, and $87,300–$88,000 opens up, with $90,000 the next magnet if momentum holds. Some technicians point to an inverse head-and-shoulders pattern with a neckline near $84,045, projecting as high as $117,247 if Bitcoin sustains above $86,93.
However, failing to hold $83,500–$84,000, though, the setup weakens fast, with $82,000 and eventually $77,000 back in play. Worth tracking against the Bitcoin price prediction covering these same levels in more depth.
Earn $50 and Enter $300K Prize Draw on EdgeX
Bitcoin Hyper Targets Early Mover Upside as Bitcoin Tests Key Levels
A 13.9% weekly gain feels good if already positioned. For anyone buying Bitcoin fresh at $86,000, the math is less exciting. A move to $100,000 from here is just around 16% upside, not the kind of asymmetric return that built early crypto fortunes.
Now, the same reasoning pushed capital toward earlier-stage infrastructure plays, and Bitcoin’s own scaling limitations (still slow, still expensive for anything beyond simple transfers) are exactly the gap projects like Bitcoin Hyper are built to fill.
The city sleeps. $HYPER stays charged. — Bitcoin Hyper (@BTC_Hyper2) September 22, 2026
 pic.twitter.com/LKBUzZLH39
Bitcoin Hyper ($HYPER) is positioning as the first Bitcoin Layer 2 with native SVM integration, aiming for execution speeds faster than Solana while settling back to Bitcoin’s base layer. The presale has raised $33.1 million at a current token price of $0.0136867, with staking APY available for early participants.
Its decentralized canonical bridge handles BTC transfers without relying on custodial intermediaries, and traders can research Bitcoin Hyper directly through the presale page.
Trade Bitcoin on Bybit and Get a Chance to Win Our $1,000 USDT Airdrop
The post Bitcoin Price Prediction: ETF Flows Turned Green After $5.8 Billion Outflow appeared first on Cryptonews.
Crypto World
Bitcoin holders are cashing out, just not the way they did at prior market tops : Crypto Daily
Bitcoin’s recent surge has some traders liquidating the coins to take profits on their holdings. But the pace of this operation is far slower than at prior market peaks, a positive sign for the market.
BTC has rallied by 44% to nearly $85,000 this quarter, its best performance since the final three months of 2024, according to CoinDesk data. The strong rise comes after three straight quarters of red ink.
Naturally, some are taking profits, as evidenced by the net realized profit/loss metric. It records the dollar gains locked in when coins actually move on-chain at a price above the last price at which they changed hands.
Analysts treat that prior transfer as a cost basis: if a coin bought or last spent at $40,000 is later sent or sold at $84,000, the $44,000 difference is booked as realized profit.
Investors have recently realized $2.4 billion in profits after the price surge, according to data tracked by Bitfinex.
“BTC holders just realised $2.4bn in profits. At prior market tops, daily realized profits ran between $7bn and $10bn,” Bitfinex said on X.
Ethena has added tokenized U.S. equities and equity perpetual futures to the basis trading strategy used for part of USDe’s backing, taking a funding model previously centered on crypto markets into listed stocks.
Summary
- Ethena will use Binance bStocks as tokenized spot collateral and equity perpetual futures as the hedge for part of USDe’s backing strategy.
- The move takes Ethena’s delta neutral basis trade beyond crypto assets after its Risk Committee approved a framework for tokenized equities.
- Binance has more than $2.9 billion in equity perpetual open interest, while the equity basis has averaged 3.56% annualized over the past six months.
- Ethena expects the opportunity in equity perpetual markets to eventually become significantly larger than the crypto perpetual market.
According to a statement shared with crypto.media, Ethena will use Binance’s bStocks as the spot side of the trade while taking offsetting positions through equity perpetual futures on the exchange.
The structure follows a framework previously approved by the Ethena Risk Committee for adding tokenized equity basis trades to the protocol’s allocation strategy. Ethena has historically used a delta neutral approach in crypto markets, pairing asset exposure with derivatives positions intended to hedge movements in the underlying asset.
Under the new setup, bStocks will provide tokenized equity exposure while Binance’s corresponding perpetual contracts will provide the hedge. The strategy seeks to capture the difference between the spot and perpetual markets without relying primarily on the direction of the underlying stock.
“This is the most significant expansion of USDe’s funding mechanism since we started,” Ethena Labs founder Guy Young said.
“Equities trade in the hundreds of trillions of dollars globally, and as more of that market moves onchain, we see a substantial opportunity to continue diversifying our backing strategy,” Young added.
How will Ethena use tokenized stocks for USDe?
Binance’s bStocks represent interests in securities held by issuer BTech Holdings Limited. Eligible users can convert the tokens into the corresponding securities through Binance where permitted by applicable laws.
The exchange launched its first bStocks in June with tokenized versions of Nvidia, Tesla, Circle, Micron and Sandisk. The assets are backed 1:1 by corresponding securities and can be converted between stock and tokenized form without conversion fees for eligible users.
Unlike direct share ownership, bStocks provide economic exposure to the linked securities without giving token holders the voting rights associated with owning the shares themselves.
Demand for the product grew quickly after its launch. By August, the value of Binance bStocks had reached roughly $610.6 million, putting the product ahead of xStocks as the second largest tokenized stock issuer in the dataset tracked by Token Terminal. Ondo Finance remained the largest issuer at the time.
Ethena plans to pair the tokenized assets with short positions in Binance equity perpetual futures. Gains or losses in the spot position can therefore be offset by movements in the derivatives position, leaving the funding or basis between the two markets as the main source of return.
Binance had more than $2.9 billion of open interest across equity perpetual futures based on figures provided by Ethena. Open interest in the products has grown at a compound monthly rate of 105% this year, while the equity basis averaged an annualized 3.56% during the past six months.
Ethena USDe backing moves beyond crypto basis trades
USDe’s backing model has already changed considerably as Ethena has added lending, stablecoin liquidity and tokenized real world assets alongside its original crypto basis positions.
Crypto.news previously reported that crypto basis positions accounted for roughly $39 million, or 1%, of USDe’s backing portfolio in early July. DeFi lending represented around 46%, while liquid stablecoins made up 35% and tokenized real world assets accounted for another 11.2%.
Institutional lending has become another part of the allocation. Ethena and FalconX launched a $1 billion facility in August that allows assets backing USDe to finance overcollateralized loans to institutional borrowers. FalconX originates and services the loans through a special purpose vehicle, while qualified custodians hold collateral worth more than the outstanding loans.
Institutional lending represented roughly $310 million, or 6.9%, of USDe backing in early July, according to Ethena governance data cited at the time.
Adding equities gives the protocol another market in which it can run the basis strategy that formed the original foundation of USDe. Ethena expects the opportunity in equity perpetuals to eventually become significantly larger than the corresponding crypto perpetual market.
Binance Head of Exchange and Trading Shunyet Jan said growing liquidity around bStocks and equity perpetuals was creating more use cases for both products.
“Ethena runs one of the largest systematic strategies in digital assets, and their expansion into tokenized securities and equity perps is a clear sign of how the convergence of crypto and traditional assets will surface new opportunities,” Jan said.
Binance equity markets provide the other side of the trade
Binance has spent much of 2026 building stock products alongside its crypto trading business, giving Ethena both tokenized spot instruments and derivatives within the same trading ecosystem.
The exchange opened access to more than 7,000 U.S. stocks and ETFs for eligible users outside the United States in June. Fractional purchases start at $5, while users can fund positions with USDT, USDC, BNB and selected cryptocurrencies.
bStocks followed later that month as the tokenized layer of the equity offering. Eligible holders can trade the assets around the clock and withdraw supported tokens to compatible self custody wallets.
Activity in Binance’s traditional finance derivatives business has grown alongside the spot offering. The exchange’s TradFi perpetual futures generated roughly $433.4 billion of trading volume during August, according to figures previously reported by The Block. Equity linked contracts accounted for approximately $342.9 billion of the total.
The exchange has continued building products around the same market. Binance recently said its Direct Stocks service crossed $1 billion in user held U.S. equities within 30 days of launch, while trading volume approached $3 billion over the period.
Equity perpetuals give traders leveraged exposure without requiring ownership of the underlying securities, while bStocks create tokenized representations tied to securities held by BTech Holdings. Ethena’s strategy uses the two sides together instead of treating them as separate directional trades.
Tokenized equities have grown across crypto platforms
Ethena’s allocation arrives as tokenized stocks have become one of the faster growing parts of the real world asset market.
Token Terminal data cited in August put the tokenized stock market it tracked at around $2.7 billion, compared with roughly $80 million a year earlier. Binance’s bStocks accounted for more than $600 million at the time, while Ondo Finance and xStocks represented other major issuers in the dataset.
Binance Research previously estimated that tokenized stocks had grown 422% as the wider tokenized real world asset market expanded during 2026. The firm said adoption would continue to depend on factors including regulation, custody, market depth and exchange support.
Traditional market products have meanwhile become a larger part of activity on crypto exchanges. Binance Research said TradFi linked perpetual contracts already represented roughly 10% of stablecoin trading volume earlier this year, with stablecoin settlement providing a route for users to trade traditional assets through existing crypto accounts.
Ethena’s equity allocation will operate within the risk framework approved by its Risk Committee, using tokenized spot positions and corresponding perpetual hedges as the protocol begins deploying its basis strategy outside crypto assets.
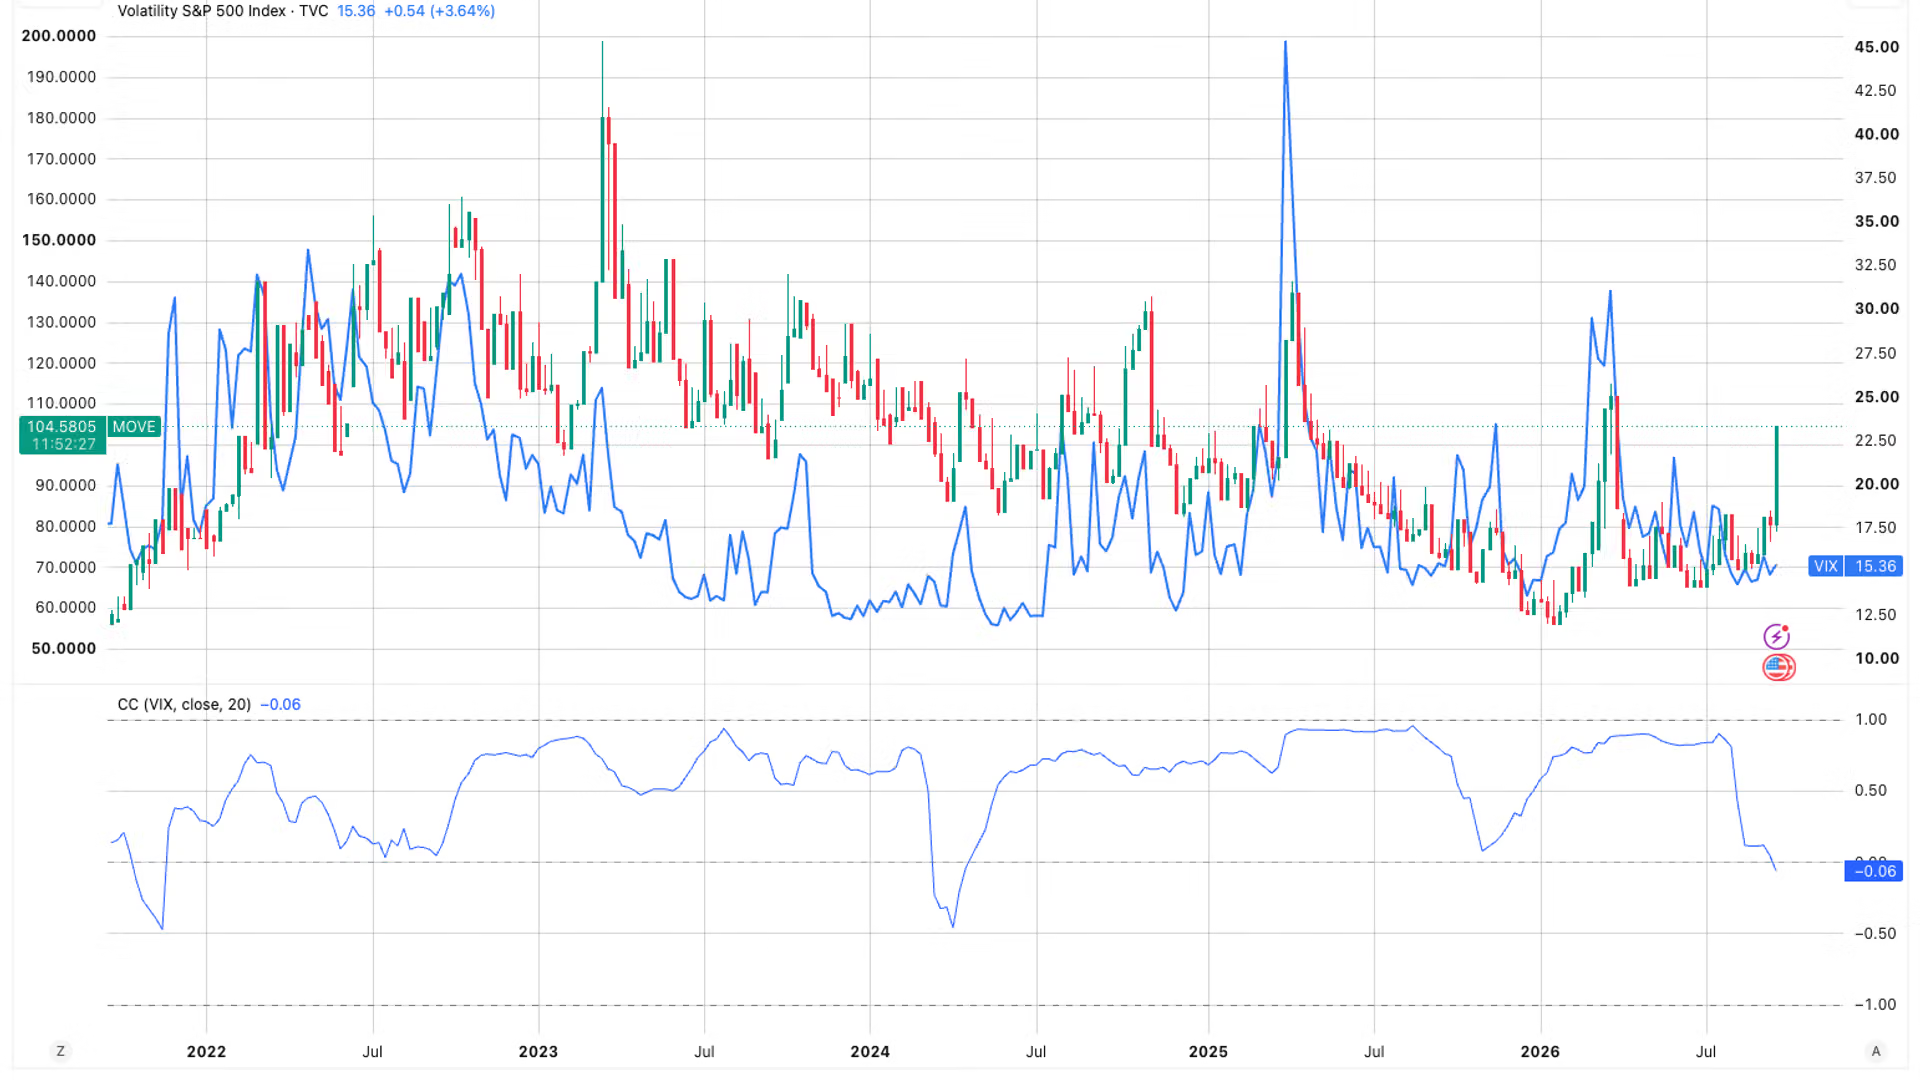
The divergence comes as government bond yields climb globally. The war in the Middle East has driven oil and diesel prices higher, complicating the inflation outlook and raising questions about how much further central banks may need to tighten policy. The U.S. 10-year Treasury yield briefly hit 5.2% on Thursday before easing to 5.163%.
When MOVE was last around this level in March, the S&P 500 stood near 6,350. It has since risen to 7,704, up roughly 21%. However, bond traders are now paying considerably more for protection against swings in interest rates.
Over a 20-day window, the correlation between VIX and MOVE has slipped to −0.06, turning negative for the first time since April 2024, though that reading is close to zero. The correlation between BVIV and MOVE is more clearly negative at −0.37, one of its lowest readings in years. As bond volatility has risen, bitcoin’s expected volatility has remained near its yearly low.
As CoinDesk reported this week, rising yields alone have shown little consistent relationship with bitcoin’s returns.

The popular cross-border token continues with its highly volatile trading sessions, but today it’s in the right direction. After yesterday’s slump to under $1.50, the asset has rebounded swiftly and now sits over 6.5% higher than it was 24 hours ago.
Here are some of the possible reasons why and what’s next.
ETF Inflows Keep Rocking
Although the entire market tanked yesterday, XRP’s nosedive was quite painful on its own, as the asset was violently rejected at $1.65 and slumped to under $1.50 within 24 hours. Today’s situation is rather similar in terms of more profound price moves, but in the opposite direction. BTC is up by 1.6% today, similar to BNB, while ETH has gained under 2.5%. XRP stands out with a daily surge of 6.6% as of press time and now sits at $1.55 after rebounding from the key $1.50 support.
This rather notable volatility has not deterred investors gaining exposure to the asset through the spot Ripple ETFs. Despite the sluggish start with $0.00 in reportable data on Monday, the funds went on a roll in the following three days, attracting $20.02 million on Tuesday, $18.04 million on Wednesday, and another $14.89 million on Thursday, which is our first possible reason behind the impressive rebound.
The cumulative net inflows have skyrocketed to yet another all-time high of over $1.76 billion. Other notable developments in XRP’s recent performance that could have pushed the asset’s price higher include whale activity, as these large market participants acquired over 1.5 billion tokens in 96 hours last week.
Short Squeeze?
Data shared by popular crypto commentator on X, Xaif Crypto, outlined the third possible reason behind today’s remarkable comeback. He noted that the XRP/USD trading pair printed a substantial surge in short liquidations of over 45% on the 4-hour chart. Such developments could lead to a deeper short squeeze as traders have to close their positions and buy tokens to cover their losses. Xaif added that longs followed with a “brutal +16.11% swing right after.”
Meanwhile, fellow XRP Army member Bird speculated that the token has just flashed a “green light” and predicted that the next move higher has begun after a “perfect leveraged long flush and backtest.” His first target sits at $1.80 by the end of the week, which is rather optimistic as of now.
Green light

The next move up for XRP has begun after a perfect leveraged. long flush and backtest.
$1.80 by EOW
pic.twitter.com/lT67PxFVa7
— Bird (@Bird_XRPL) September 24, 2026
The post Why Is Ripple’s (XRP) Price Up Today: September 25 appeared first on CryptoPotato.
KelpDAO has escalated its legal fight over a major cross-chain bridge exploit by filing a lawsuit against LayerZero, alleging that shortcomings in LayerZero’s security infrastructure helped enable the theft of roughly $292 million worth of rsETH earlier this year.
The filing, first reported by KelpDAO and reported in related coverage of the incident, targets LayerZero as well as its co-founder and CEO, Bryan Pellegrino. KelpDAO says LayerZero did not adequately disclose risks and failed to stop attackers from compromising its infrastructure, while it also alleges LayerZero reviewed and endorsed KelpDAO’s bridge deployment and configuration in writing.
Key takeaways
- KelpDAO claims LayerZero’s technology and security infrastructure contributed to the April rsETH bridge exploit that stole 116,500 rsETH.
- The lawsuit alleges LayerZero failed to disclose relevant risks and did not prevent attackers from compromising its internal systems.
- KelpDAO also alleges LayerZero reviewed and endorsed KelpDAO’s bridge configuration and deployment in writing before the incident.
- LayerZero previously attributed the loss to attackers compromising its internal nodes and approval process, while arguing KelpDAO’s setup relied too heavily on a single verification path.
- Pellegrino rejected the allegations as “meritless” and said he plans to defend the case in Vancouver.
From exploit to courtroom dispute
The legal move follows the April 18 attack, which resulted in the theft of 116,500 rsETH from Kelp’s LayerZero-powered bridge. According to earlier reporting from Cointelegraph, the haul was valued at about $292 million at the time.
In its account of the incident, LayerZero said attackers compromised its internal nodes and manipulated the verifier into approving a forged cross-chain message. LayerZero argued that the theft was possible because the bridge design relied on a single decentralized verifier network (DVN) as the only verification path.
LayerZero also said it recommended using multiple DVNs and later stopped acting as the sole required verifier for applications, an important detail because it suggests the protocol changed its posture after the incident. KelpDAO, however, disputes that narrative and argues that the core failure lies with LayerZero’s security practices.
KelpDAO’s accusations against LayerZero
KelpDAO said LayerZero failed to disclose risks in its technology and did not prevent attackers from compromising LayerZero’s infrastructure. The lawsuit further alleges that LayerZero reviewed and endorsed KelpDAO’s deployment and configuration in writing before the exploit.
KelpDAO framed the case as both a security response and an effort to correct what it sees as an inaccurate public record about responsibility for the breach. In a statement shared via KelpDAO’s account, the group emphasized that protecting users’ assets remains its top priority, while it seeks to hold LayerZero and Pellegrino accountable for the harm it says was caused to KelpDAO and the broader DeFi ecosystem.
Separately, KelpDAO also targeted the question of disclosure—essentially arguing that even if a bridge design includes certain dependencies, users and operators must be clearly informed about risks and threat models associated with those dependencies.
LayerZero’s stance: internal compromise and verifier design
LayerZero’s position, as described in prior coverage, focused on what happened inside its own system and why the message verification pathway worked the way it did. In its final incident report cited by Cointelegraph, LayerZero said internal nodes were compromised and that a forged cross-chain message was approved by its verifier.
LayerZero argued that the bridge released rsETH after receiving approval for the forged message—pointing to the fact that there was no requirement for a second independent verifier in the setup used for that deployment.
That distinction matters because it frames the dispute as more than a question of whether something went wrong; it becomes a debate over whether the dominant failure mode was inside LayerZero’s infrastructure, inside KelpDAO’s configuration choices, or a combination of both.
LayerZero also said it recommended the use of multiple DVNs and later stopped acting as the sole required verifier for applications—implying that the system design risk was mitigated after the exploit. The lawsuit, by contrast, suggests KelpDAO believes these controls and warnings should have been in place earlier.
Pellegrino rejects the claims; responsibility remains contested
LayerZero co-founder and CEO Bryan Pellegrino responded by calling KelpDAO’s claims “meritless,” according to a post shared on X. He also said he would defend the case in Vancouver.
The lawsuit therefore intensifies a dispute that had been brewing for months after the April incident. As Cointelegraph previously reported, the arguments have repeatedly returned to the same central fault line: whether the loss was caused primarily by compromise of LayerZero’s infrastructure, weaknesses or decisions in KelpDAO’s bridge configuration, or both.
In May, KelpDAO publicly disputed LayerZero’s account of responsibility. KelpDAO said that its DVN configuration had been previously discussed with LayerZero and “confirmed as secure,” while it accused LayerZero of failing to adequately warn it about the risks. In that period, KelpDAO also announced plans to migrate the rsETH bridge to Chainlink’s Cross-Chain Interoperability Protocol.
That migration plan is relevant to investors and users because it shows that KelpDAO did not wait for legal clarity to alter its operational posture. Still, legal filings aim to determine accountability—how the incident is ultimately characterized and who is held responsible for losses.
Cointelegraph attempted to obtain additional comment from LayerZero but did not receive a response before publication, according to the earlier reporting included in the source material.
For now, the key thing to watch is how the court frames the alleged “shared failure” described by each side—especially the claims around risk disclosure and whether LayerZero’s alleged written endorsement of KelpDAO’s configuration becomes central evidence. As the case develops, the most important unanswered question remains whether the evidence supports KelpDAO’s view that LayerZero’s security infrastructure and communications were the decisive factors, or whether LayerZero can persuade the court that the exploit was driven mainly by configuration choices at the application layer.
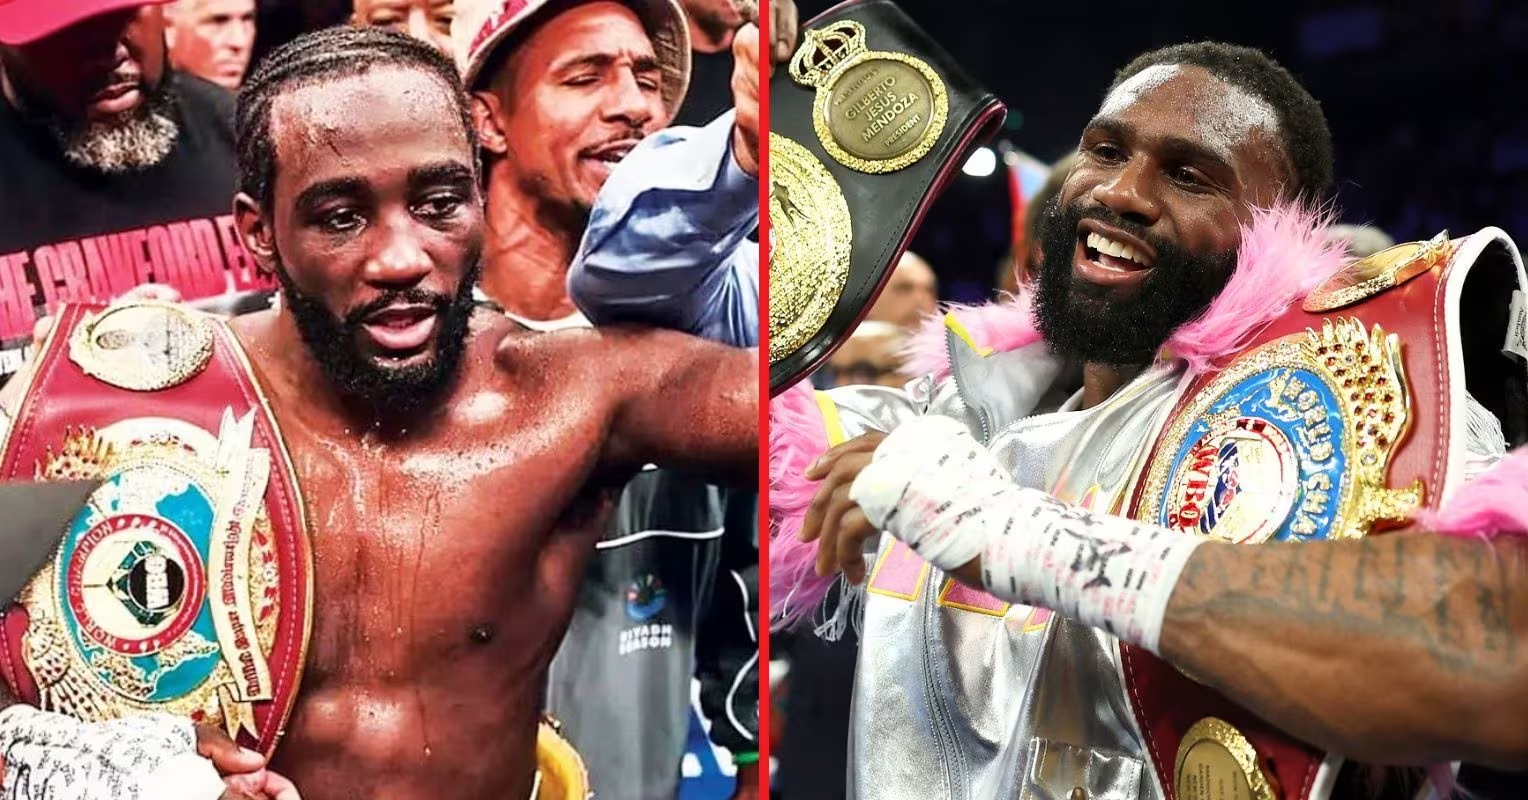
Teofimo Lopez sums up Jaron Ennis’ chances of beating Terence Crawford in comeback fight

Noah Woods died after leaving park through gap in fence, inquest hears

Immigration cut could decimate aged care, panellist says




-

 Fashion7 days ago
Weekend Open Thread: Talbots – Corporette.com
-

 Crypto World3 days ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-

 Tech5 days ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Fashion1 day ago
8 iPhone Accessories That Add Personality
-

 Crypto World5 days ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-

 Crypto World6 days ago
Circle launches Arc Studio AI agent for building onchain apps
-

 Crypto World7 days ago
Trading Bitcoin on Robinhood? Why 2% Spread Has Traders Worried
-
 NewsBeat7 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Tech6 days ago
Trump suggests rebranding AI with a new name, says he’s also creating an AI Force
-

 Crypto World7 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Business5 days ago
Analog Devices (ADI) Bets $1.35 Billion on Chips that Let Machines Think for Themselves
-

 Tech4 days ago
Google’s $899 Googlebook is a bet that you’ll buy a new laptop for Gemini
-

 Crypto World5 days ago
Coinbase, Robinhood, Circle Seen as Tokenized-Stock Winners
-

 Crypto World2 days ago
This Bearish Netflix Stock Trade Can Cash In On Video Streaming Giant’s Woes
-
 Business2 days ago
Oil Price Today (September 23): Crude oil below $100 on hopes of US-Iran talks. What did Trump say?
-

 Entertainment2 days ago
These 17 Fall Amazon Dresses Seriously Look Like Anthropologie
-

 Crypto World2 days ago
Crude Oil Prices Pressured by Diplomatic Hopes in the Middle East
-

 Crypto World6 days ago
World Money launches in 150+ countries with Stripe
-

 Crypto World3 days ago
Trump-Xi Polymarket Odds for Handshake Hit 50%
-

 Crypto World2 days ago
Bitcoin Threatens Sub-$84,000 Breakdown as Long Liquidations Spike
You must be logged in to post a comment Login