BlackRock and Ondo Finance have launched tokenized model portfolios on blockchain networks, expanding access to traditional assets. The partnership introduces three digital portfolios that combine stocks, bonds, and Bitcoin ETFs based on different strategies. The move strengthens the growing connection between traditional finance products and blockchain-based markets.
BlackRock And Ondo Finance Expand Tokenized Portfolios
BlackRock has partnered with Ondo Finance to introduce three tokenized model portfolios through the blockchain platform. The portfolios focus on high growth, diversified growth, and high income strategies. Each product tracks a different mix of traditional assets and digital market exposure.
The launch forms part of Ondo Finance’s rollout of seven tokenized model portfolios across its platform. The company will issue digital tokens that represent the performance of each portfolio. Furthermore, automated software will purchase underlying assets when users acquire the digital tokens.
The tokenized portfolios will initially serve markets outside the United States, while enabling round-the-clock trading access. The products allow blockchain users to gain exposure to traditional financial assets through digital representations. However, the portfolios remain linked to the performance of their underlying investments.
Advertisement
BlackRock has expanded its tokenization strategy as financial firms explore blockchain-based infrastructure. The asset manager previously launched tokenized money market funds to support digital finance applications. Therefore, the latest partnership adds another step in BlackRock’s broader blockchain expansion.
Ondo Finance also recently partnered with Near Protocol to launch tokenized stocks and exchange-traded products. The collaboration introduced 20 assets, including Tesla, NVIDIA, Apple, and QQQ products. Consequently, Ondo continues expanding its role in tokenized financial markets.
The partnership highlights the increasing demand for blockchain-based versions of traditional investment products. Financial institutions are using tokenization to create digital access points for existing assets. Meanwhile, platforms like Ondo Finance continue building infrastructure for these products.
OnD O Token Gains After Tokenization Plans
The ONDO token recorded double-digit gains following news of the BlackRock partnership and portfolio launch. The token traded near $0.48, representing a rise of more than 16% based on TradingView data. The increase came despite weakness across the wider cryptocurrency market.
Advertisement
Bitcoin declined toward $83,000 during the same period, creating mixed conditions across digital assets. However, ONDO maintained positive momentum after gaining more than 37% during the week. The token also moved into yearly gains, rising over 33% year-to-date.
The price movement followed increased attention around Ondo Finance’s tokenization activities. The platform has positioned itself as a major provider of blockchain-based financial products. Furthermore, new partnerships have expanded its presence across multiple blockchain ecosystems.
Ondo Finance has also faced internal challenges following the death of founder Nathan Allman. Family members and an early investor have sought control of the company. The dispute has created legal challenges surrounding the platform’s leadership structure.
Despite the leadership issues, Ondo Finance continues advancing its tokenization plans through new partnerships. The company remains focused on connecting traditional assets with blockchain networks. Therefore, the BlackRock collaboration represents a significant development for its product expansion.
Advertisement
The launch reflects a wider shift toward digital versions of financial instruments. Asset managers and blockchain companies are developing systems that combine traditional markets with decentralized technology. As a result, tokenized portfolios are becoming a growing segment within digital finance.
Risk & affiliate notice: Crypto assets are volatile and capital is at risk. This article may contain affiliate links. Read full disclosure
Join Our Telegram channel to stay up to date on breaking news coverage
The Commodity Futures Trading Commission is reviewing nearly one million ether perpetual futures trades on Kalshi that occurred in almost identical amounts and accounted for more than $5 billion in volume over the past month.
A $5,500 cluster
An analysis of public data reportedly found that more than one third of trades in the market in recent weeks were clustered around $5,500.
The cluster prompted allegations of wash trading, meaning trades without genuine economic purpose that can create a misleading impression of market activity. Kalshi denies the allegations. The company said hundreds of distinct traders participated and that the repeated trade sizes came from market makers keeping fixed resting orders in the book, which faster traders repeatedly hit. Kalshi said self trading is mechanically blocked and coordinated wash trading is prohibited and monitored.
Advertisement
The CFTC is weighing the activity before deciding whether to open an enforcement investigation, a person familiar with the matter reportedly said. The agency said it could not comment on whether an investigation is underway.
Jump Trading and Wintermute were reportedly among the firms involved in the rapid transactions. Jump said it trades for profit, uses self match prevention tools and does not coordinate its activity with other traders. Wintermute’s response was not known.
Stakes for Kalshi’s expansion
Kalshi launched crypto perpetual futures, contracts with no expiry date, in May and has since sought regulatory approval to offer similar contracts tied to individual US stocks. The review lands with that application pending, and with more than a third of the market’s recent trades tied to a single price level, it raises questions about how much of the young market’s volume is organic.
Join Our Telegram channel to stay up to date on breaking news coverage
RWA perpetual DEX trading volume has reached $365 billion in Q3 2026, rising 32% from the previous quarter as public equities generated nearly half of the activity.
Summary
RWA perpetual DEX volume reached $365 billion in Q3 2026, rising 32% quarter over quarter.
Public equities generated $175 billion, accounting for nearly 48% of quarterly RWA perpetual DEX volume.
August RWA perpetual volume fell 13.5% to $122 billion after July’s record $141 billion level.
Perpetual DEX open interest reached $19 billion, while RWA markets exceeded 1,000 listings across venues.
Tokenized stock market capitalization reached $3.5 billion, with BNB Chain holding approximately $1 billion alone.
CryptoRank reported the quarterly figures on Sept. 24, placing public-equity perpetual volume at approximately $175 billion, or close to 48% of the total. The quarter still produced growth despite monthly volumes declining during August and September.
The figures refer specifically to real-world asset perpetual contracts traded through decentralized venues. RWA perpetuals provide derivative exposure to assets such as stocks, commodities and indexes without requiring traders to own the referenced assets directly.
Advertisement
📈 RWA Perp DEX Volume Reaches $365B in Q3#RWA trading volume across perpetual DEXs reached $365B in Q3 2026, up 32% QoQ, despite monthly volumes declining in August and September.
Public equities dominated activity with $175B, accounting for nearly 48% of total Perp Dex RWA… pic.twitter.com/mPuNVSOzsT
RWA perp DEX volume grew despite two monthly declines
Trading activity entered Q3 from a strong base. CryptoRank said July RWA perpetual volume reached a record $141 billion, following a rise from only $23.1 billion at the start of 2026.
Advertisement
August then became the first monthly contraction since January. Volume fell 13.5% to $122 billion, ending the uninterrupted expansion seen during the preceding months. CryptoRank attributed the pullback to renewed demand for crypto assets after Bitcoin and other major tokens posted stronger price moves during August.
September volume declined again, according to CryptoRank’s Sept. 24 update, yet the full quarterly total still reached $365 billion. The 32% quarter-over-quarter increase shows that July’s record activity was large enough to keep Q3 above the prior three-month period despite the later slowdown.
CryptoRank’s monthly series had already shown how quickly the market expanded during the first seven months of 2026. Its earlier research put July activity 513% above the level at the start of the year, with RWA contracts becoming a larger component of decentralized perpetual trading.
Public equities captured nearly half of Q3 volume
Stocks represented the largest RWA perpetual category during the quarter. CryptoRank placed public-equity volume at $175 billion, giving the category nearly 48% of the $365 billion Q3 total.
Advertisement
The concentration in equities follows a change already visible in August. CryptoRank’s monthly report said public equities had become the largest category in its RWA perpetual dataset. On Hyperliquid, stock-linked contracts accounted for 67% of HIP-3 volume during August, moving ahead of commodity contracts.
Available markets have expanded alongside trading activity. CryptoRank reported on Sept. 22 that decentralized perpetual venues now offer more than 1,000 RWA markets, with public equities representing roughly 75% of listings.
The same report placed tokenized stock market capitalization at $3.5 billion. BNB Chain hosted around $1 billion, while Ethereum and Solana followed. Combined, the three networks represented roughly 70% of the market measured by CryptoRank.
RWA perpetuals differ from tokenized stocks themselves. Perpetual contracts generally track the price of an underlying asset through derivatives and do not give holders ownership rights, dividends or voting claims attached to the referenced stock. Crypto.news explained the distinction in its guide to RWA perpetuals covering stocks and commodities.
Advertisement
Perpetual DEX open interest has reached a record
Trading volume has grown alongside outstanding positions. CryptoRank’s Sept. 22 research put total perpetual DEX open interest at a record $19 billion, with overall perpetual open interest across the measured market near $25 billion.
RWA contracts represented roughly 24% of total open interest, up from around 6% at the beginning of 2026. CryptoRank calculated an 18-percentage-point increase during the year as exchanges introduced more markets tied to stocks, commodities and indexes.
Hyperliquid has remained a major venue in the decentralized derivatives market. Current CryptoRank rankings place Hyperliquid Futures at the top of the DEX table by open interest, with billions of dollars in outstanding perpetual positions and hundreds of listed markets.
One day before CryptoRank published the Q3 RWA figures, Hyperliquid’s open interest reached a reported record of $18 billion. As crypto.news reported in its Hyperliquid open-interest record coverage, BTC, ETH and HYPE accounted for roughly $9.33 billion, while HIP-3 continued hosting contracts linked to stocks, commodities and indexes.
Advertisement
Equity markets are expanding through HIP-3 and tokenization
Hyperliquid’s HIP-3 infrastructure has contributed to stock-linked perpetual activity by letting independent teams deploy perpetual markets. Crypto.news previously reported that TradeXYZ processed $202.36 billion during Q2, based on an independent Hyperliquid Research Collective report.
Equity perpetuals generated $58.9 billion across 55 markets on TradeXYZ during Q2, a 377% quarter-over-quarter increase, according to that report. TradeXYZ’s share of HIP-3 volume increased from 84.5% to 95.1% during the quarter.
On-chain stock activity is developing outside perpetual contracts as well. In June, Ondo Finance extended tokenized U.S. stocks to Hyperliquid’s HyperEVM, initially supporting 35 names including Nvidia, Tesla, Alphabet and several ETFs, as crypto.news reported in its HyperEVM coverage.
Base has recorded another source of tokenized-equity activity. Token Terminal data cited by crypto.news put 30-day tokenized-stock DEX volume on Base at $730.9 million by Sept. 12, after daily volume reached $100 million. Aerodrome processed $557.1 million of the measured monthly activity.
Advertisement
U.S. access to many tokenized equity products remains restricted. Crypto.news reported Sept. 21 that TD Cowen expects limited domestic demand even as the regulatory framework develops, noting that U.S. investors already have established access to conventional listed equities.
Separately, Coinbase’s Base-native stock tokens remain unavailable to U.S. persons under the company’s current Regulation S structure. Coinbase expanded its lineup in September after its first group of tokenized equities produced $227.7 million in decentralized exchange volume over roughly 30 days, according to Token Terminal data cited by crypto.news.
Pudgy Penguins (PENGU) has fallen nearly 10% in 24 hours to around $0.0098 on Sept. 24, even as the token remains roughly 38% higher over the past seven days.
Summary
PENGU fell nearly 10% in 24 hours while remaining roughly 38% higher over seven days.
CoinGlass showed open interest near $156 million as derivatives activity cooled during the latest pullback.
RSI at 67.15 remained below overbought territory while the Aroon Oscillator stayed positive near 57.
Ali Charts identified weekly buy signals, while his $0.025 and $0.045 targets remain projections only.
Spot netflow was slightly positive near $88,550, showing limited imbalance between exchange inflows and outflows.
CoinGecko data shows PENGU trading around $0.0098 during the latest check, with a 24-hour range between $0.009478 and $0.01111. Its market capitalization stood near $619 million, while 24-hour trading volume was approximately $376 million.
The token had climbed from $0.00685 on Sept. 15 to above $0.010 earlier this week, CoinGecko historical data shows. PENGU reached the $0.011 area before sellers pushed the price back under the psychologically watched $0.010 level.
Advertisement
PENGU price has slipped below $0.01 after its rally
The latest decline follows several days of strong gains. CoinGecko recorded PENGU at $0.00726 on Sept. 17 and $0.01003 by Sept. 22, showing how quickly the token advanced before the latest pullback.
CoinGecko still placed PENGU’s seven-day return near 38.2% during the Sept. 24 check. The token remained approximately 85% below its $0.06845 all-time high despite the weekly recovery, while its circulating supply stood at roughly 62.86 billion tokens.
No single verified project-specific event reviewed for this report established the cause of Thursday’s drop. Market data instead shows the decline occurring after PENGU reached its highest price in several months and after derivatives participation began cooling.
Advertisement
PENGU open interest has fallen as traders reduce exposure
A Sept. 24 CoinGlass snapshot showed derivatives volume down 12.68% at approximately $536.67 million, while open interest declined 11.66% to roughly $154.03 million. A later live reading placed open interest near $156.47 million and 24-hour futures volume around $576.31 million, showing how quickly the figures can change intraday.
CoinGlass recorded nearly $1.94 million in PENGU futures liquidations over 24 hours during that later reading. Falling open interest means fewer futures positions remain outstanding, although CoinGlass notes that position closures can result from voluntary exits or forced liquidations and do not identify a single directional cause.
Pengu spot netflows, source: CoinGlass
Spot flows looked less decisive. The Sept. 24 CoinGlass netflow reading supplied with the market data stood near +$88,550, meaning exchange inflows were only slightly above outflows at that point. The recent flow series contained both positive and negative readings without a sustained run of large positive inflows.
Technical indicators remain positive but momentum is stretched
PENGU’s 14-period RSI stood at 67.15 in the chart data provided for Sept. 24. The reading remains above the neutral 50 level and below the conventional 70 overbought threshold, showing strong momentum without formally entering the usual overbought zone. The RSI moving average sat near 50.56.
The Aroon Oscillator was approximately +57.14, indicating that recent highs have occurred more prominently than recent lows over its 14-period window. Both measures remained positive despite the price rejection above $0.010.
Advertisement
PENGU price chart, source: TradingView
The $0.0095 region therefore sits close to the token’s Sept. 24 intraday low of $0.009478 recorded by CoinGecko. A loss of that area would place PENGU below the short-term support identified by CoinLore, while a recovery above $0.0105 would move price back toward its recent highs.
Analysts are watching $0.011 before higher PENGU targets
Crypto analyst Ali Charts has pointed to several weekly indicators that he views as constructive. His Sept. 22 analysis identified contracting Bollinger Bands, consecutive Tom DeMark Sequential buy signals, a bullish Parabolic SAR flip and a SuperTrend buy signal.
Ali wrote “PENGU BULL RUN IS ABOUT TO START” while placing the midpoint of a parallel channel around $0.025 and its upper boundary close to $0.045. Both levels are analyst projections, not confirmed price outcomes. Independent coverage of his chart documented the same Bollinger Band, TD Sequential, Parabolic SAR and SuperTrend readings.
Two days later, Ali compared PENGU’s structure with an earlier PEPE cycle and wrote “PENGU ABOUT TO EXPLODE.” His comparison relies on a historical price fractal, so a similar past pattern does not establish that PENGU will follow PEPE’s previous trajectory.
Crypto Patel presented a different set of levels, identifying approximately $0.009 as a confirmed breakout zone and $0.0055 as higher-timeframe support. His projected levels were $0.015, $0.028, $0.043 and $0.060 if PENGU confirms a break and retest of its descending higher-timeframe trendline.
Advertisement
Patel stressed the need for confirmation, writing, “I don’t want to chase a candle. I want to see a clean break.” His $0.060 scenario represents a forecast based on technical structure and is not a verified future price.
Pudgy Penguins has fresh product activity behind the token
Pudgy Penguins has continued expanding its consumer products while PENGU trades through the current volatility. The project’s official store lists new fall products including stationery, water bottles, stickers and stress-ball sets, while a Sept. 23 report described a 12-product Pudgy Essentials release.
A separate corporate filing provided another verified ecosystem update. Mint Incorporation filed a Form 6-K on Sept. 15 stating that subsidiary Rice AI had entered a licensing agreement with Pudgy Penguins to develop and commercialize a limited-edition Blue Pengu Minibot. The filing describes the product as an AI-powered companion robot using Pudgy Penguins intellectual property.
Rice AI received a non-exclusive worldwide license for the product, according to the filing. The company will cover production, marketing, product compliance, warranty and after-sales support costs, while sales are planned through Rice AI-controlled e-commerce and physical retail channels.
Advertisement
Disclosure: This article does not represent investment advice. The content and materials featured on this page are for educational purposes only.
The Senate stopped short of debating a federal crypto market structure bill. A week later, the CFTC chair was still laying out plans for tokenized collateral and round-the-clock markets. The agencies can act under existing law, but their records show how far each action actually reaches.
Summary
The Sept. 15 Senate cloture vote on the CLARITY Act ended 49 to 50, with one senator absent.
The SEC’s March 17 crypto interpretation describes five asset categories but creates no new spot market regulator.
An Aug. 18 SEC proposal includes offering exemptions of $5 million and $75 million, subject to public comment.
The SEC’s Sept. 17 stock trading exemption expires in 2031 and covers a defined venue model.
A CFTC crypto markets measure entered White House review on Sept. 17 at the prerule stage.
The Commodity Futures Trading Commission wants markets ready for tokenized collateral and 24-hour trading. Its chair, Michael Selig, said as much at a Treasury market conference on Sept. 22, one week after the Senate blocked debate on the CLARITY Act. He described work on stablecoins as derivatives collateral and said some products, including crypto, may suit continuous trading. The agency had already sent a crypto market measure to White House review. Selig’s remarks were a statement of direction, not the publication of that measure.
UST IN: CFTC Chair Michael Selig says the agency is ready to build crypto market rules if CLARITY remains stalled
Selig says the CFTC will use its existing authority to develop a crypto asset market structure, including rules for exchanges and leveraged or margined trading, as… pic.twitter.com/OFxRW5Dvx5
The order of events matters. The Securities and Exchange Commission had proposed crypto offering rules before the Senate vote. It issued a limited exemption for tokenized stock trading two days afterward. The CFTC filed a separate measure for preliminary review the same day, as crypto.news reported when the CFTC submission appeared. Washington is writing parts of a rulebook while the bill that would set its statutory foundation remains stalled.
How much of a market can those parts govern? The public documents give a more useful answer than the shorthand that regulators have replaced Congress. One action interprets existing securities law. Another proposes exemptions for raising money. A third permits a specific way to trade tokenized stocks. The CFTC’s next rule has not yet been released for public inspection. None is the spot digital commodity market law contemplated by CLARITY.
The Senate rejected debate, not a final crypto law
On Sept. 15, the Senate voted on cloture on a motion to proceed to H.R. 3633. The official roll call records 49 votes for cloture, 50 against and one senator not voting. Sixty votes were required. Senators did not vote on final passage or settle the bill’s provisions through floor amendments.
Advertisement
Some accounts inverted the numbers, describing 50 votes in favor and 49 against. The Senate record says the reverse. Either count falls short of 60, but a feature about who can write law should get the legislature’s own vote right. The 49 supporting senators were 11 votes short of the threshold. Four Republicans voted against the motion, including Thom Tillis, whose procedural switch left a route to seek reconsideration. The bill remained available for further negotiation; its Sept. 15 path to debate was blocked.
JUST IN: White House crypto adviser Patrick Witt defends Trump’s crypto ties after CLARITY Act fail
Witt said Trump agreed to “unprecedented” ethics restrictions, including limits on federal officials issuing or sponsoring digital assets, in an effort to get the bill passed. pic.twitter.com/3BjfkxQldf
CLARITY aimed to divide oversight of digital assets and their markets between the SEC and CFTC, including a registration structure for digital commodity intermediaries. Congress had been considering a more complete answer to questions that agencies now confront through rules, interpretations and orders. The House passed its version in July 2025. Its later Senate text changed during negotiations, so an account of a disputed September provision must specify which version it describes. The Senate-reported version remains a public reference, but it should not be mistaken for every late negotiating draft.
Advertisement
The disagreement was political and substantive. Senate Banking Chair Tim Scott said after the vote that the SEC and CFTC should set rules until Congress legislates. Democratic Senator Mark Warner said he wanted digital asset legislation, but would not advance this version without stronger restrictions on senior officials profiting from policies affecting their crypto holdings. Banking organizations separately pressed for tighter restrictions on rewards associated with holding stablecoins, saying deposit competition could affect lending. Those groups made a policy argument; no projected deposit loss should be treated as an observed outcome.
Seven Democratic senators who opposed the motion said the following day that they remained committed to bipartisan legislation. Calling the bill law would be false. Calling it permanently dead would go beyond the vote.
The SEC can interpret a transaction without licensing its market
The regulatory work did not begin on Sept. 15. On March 11, the SEC and CFTC signed a coordination agreement covering shared definitions, examinations and enforcement. Six days later, the SEC issued interpretive release Nos. 33-11412 and 34-105020, with accompanying CFTC guidance. It described digital commodities, collectibles, tools, stablecoins and digital securities. It addressed staking, mining, airdrops and wrapping, as well as when a nonsecurity crypto asset can be sold as part of an investment contract. The agencies’ March interpretation was an exercise of their existing authority.
Advertisement
The distinction between an asset and a transaction is central. A token need not itself be a security for a promoter’s offer of it to involve an investment contract. The SEC’s description of an asset does not remove the securities laws from every transaction in that asset. Nor does calling an asset a digital commodity hand the CFTC full supervision of every spot exchange that lists it. An earlier crypto.news examination of the SEC’s classification of XRP addresses the separate question of how long an agency interpretation may last.
Consider a platform that lists a digital commodity for ordinary purchase and another platform that offers leveraged positions in the same asset. The asset label may be the same. The activity and applicable jurisdiction are different. The CFTC regulates derivatives and certain leveraged retail commodity transactions under existing law. For ordinary spot digital commodities, it has described its federal role principally as enforcement against fraud and manipulation, without general day-to-day supervision of spot exchanges. Its own account of the distinction is unusually clear.
That is the gap CLARITY was designed to address. The SEC and CFTC can coordinate their interpretations. They cannot create an unrestricted federal spot market mandate merely by agreeing which tokens count as commodities. An agency can regulate conduct within the perimeter Congress gave it. It cannot vote itself the rest of the perimeter.
There is still practical value in the interpretation. An issuer deciding whether a proposed token sale needs securities registration now has a published view from the SEC. A derivatives venue knows the CFTC says it will administer the Commodity Exchange Act consistently with that view. The treatment could shape business decisions immediately. It is still different from a new statute governing intermediaries across the spot market. A court or later commission can test or revisit an agency’s reading of existing law.
Advertisement
Four records show why the ‘new rulebook’ is still uneven
The primary documents can be sorted by two questions: has the action taken effect, and does it govern ordinary crypto spot trading? The answer changes in every row.
Record as of Sept. 23
Legal stage
Market activity it addresses
What it does not do
SEC-CFTC interpretation, March 17
Issued interpretation
Securities treatment of specified crypto assets and transactions
Create a new spot digital commodity exchange regime
SEC Regulation Crypto Assets, Aug. 18
Proposed rule, comments due Oct. 20
Certain offerings involving crypto asset investment contracts
Give all token sellers a live exemption today
SEC tokenized stock order, Sept. 17
Effective conditional exemption through Sept. 17, 2031
A defined model for trading tokenized listed stocks
License ordinary crypto spot exchanges
CFTC crypto markets filing, Sept. 17
Prerule submission in executive review
Details have not been made public
Put a final crypto market rule into effect
One of these measures is an effective exemption. One remains a proposal. Another is a public interpretation, and the fourth is a filing title and review status. Describing all four as ‘rules now in force’ would turn a process into a result. More tellingly, the effective exemption concerns shares, which remain securities, while the largest proposed jurisdictional change in CLARITY concerned digital commodity markets. The most visible new trading permission sits on a different side of the SEC-CFTC divide.
The CFTC review record names ‘Regulation Crypto Asset Transactions and Regulation Crypto Asset Markets,’ identifies the agency, and labels its stage ‘Prerule.’ It gives a Sept. 17 receipt date. It does not disclose draft provisions or show a commission vote on a proposed or final rule. That small entry proves that a measure entered review. It does not prove what legal powers the eventual text will claim.
Selig offered a possible route in August. He said staff were examining whether existing registrants and unregistered crypto exchanges could be designated as a type of CFTC designated contract market, with leveraged or margined crypto trading under tailored rules. His remarks also described working with onchain software developers. They are evidence of his intended approach, not a substitute for the unreleased CFTC text. Whether the agency’s eventual proposal fits its existing authority depends on its actual provisions.
Advertisement
The narrower route may still change a great deal for firms that want to offer margined crypto trading in the United States. It would not automatically cover every app where a customer buys and withdraws an unleveraged token. That missing customer, venue and transaction sit at the center of the congressional question.
The SEC’s $75 million route is a proposal with an expiry problem
The SEC’s Aug. 18 proposal would give eligible projects two tailored ways to offer investment contracts involving crypto assets without registering the offering. One would allow up to $5 million over a four-year period. Another would permit up to $75 million in each 12-month period, with financial statements and ongoing reporting alongside required disclosures. It proposes a conditional safe harbor concerning when the related investment contract no longer applies. The published proposal sets an Oct. 20 comment deadline. A crypto.news account of the offering proposal examines those routes in more detail.
The proposal does not say that every token becomes exempt from securities law after four years. Its application depends on the facts of an issuer’s commitments and compliance with its conditions. It does not license an exchange to ignore laws governing securities activity. Antifraud provisions remain relevant. And none of the proposed fundraising routes can be used merely because the SEC has announced them; a final rule would have to follow the comment process.
The policy choice is significant. Projects often raise money while a team is still promising to build the network on which a token’s value might depend. The SEC is trying to specify how that fundraising stage might be conducted and, under stated conditions, how the associated investment contract could end. The proposal answers a question about capital raising. It does not supply a federal registration system for the entire digital commodity spot market.
Advertisement
BREAKING: Senator Cynthia Lummis says Democrats must pass the CLARITY Act
Lummis warned that if the bill fails, consumers could be left without federal protections, disclosure rules or delisting requirements for bad actors, saying Democrats “must pass” the fix they wrote. pic.twitter.com/AtMf2DVlCf
That distinction has an institutional consequence. A company can plan a token offering around a published proposal only provisionally. It can plan around an effective rule more confidently, while still accounting for future changes and court review. A national law fixing the agencies’ mandates would require another institution to change it. Industry advocates want the agency work to advance precisely because waiting for that institution has not produced a bill. The staged process creates rules sooner in some corners and leaves others open.
A five-year stock exemption has a narrower address
The SEC’s Sept. 17 order, release No. 34-106402, is the most concrete post-vote action. It temporarily exempts qualifying Tokenized Securities Venues from the Exchange Act definition of ‘exchange’ for a particular model of permissioned automated market maker trading in tokenized National Market System stocks. It grants separate conditional relief to certain liquidity providers from the definition of ‘dealer.’ The 60-page order states that the exemptions run until Sept. 17, 2031, unless the commission changes them under its authority.
Advertisement
Stockholders must have the same rights and privileges as holders of an equivalent traditional share. The venue faces limits on symbols and trading volume, must stop trading when the underlying stock is halted, and must allow an issuer to object when an unaffiliated third party tokenizes its shares. The smart contracts used for the trading model must be public and auditable on a public, permissionless ledger, while access to the venue is restricted to approved participants. The order does not exempt fraud or manipulation.
Those conditions illustrate both the potential and the boundary of agency action. An SEC exemption can open a defined route for trading securities without waiting for Congress to rewrite every exchange rule. It does not make all decentralized trading lawful or designate the CFTC as supervisor of every crypto asset. SEC Chair Paul Atkins called the measure a bridge and said durable rulemaking would need to follow. A crypto.news report on the tokenized stock exemption looks at the possible commercial users. A bridge is useful. It is not the destination.
The order deserves scrutiny on its own merits, too. Its volume caps are meant to limit disruptions if prices in an automated pool diverge from shares trading in conventional markets. Disclosure and records conditions give the SEC a way to see how the model operates. Whether actual venues satisfy the conditions, attract activity and preserve shareholder rights is an observable question, not an assumption to be filled in by the agency announcement.
Supporters of agency action have a strong practical case
Scott’s call for regulators to act did not require the claim that legislation was unnecessary. Selig himself said in August that a statute was the strongest way to fix the SEC-CFTC jurisdictional line and set principles for spot crypto markets. He nonetheless directed CFTC staff to examine rules under current authority. Those positions can coexist: a firm needs to know what rules apply to a proposed product now, even when Congress might later change the governing law.
Advertisement
Atkins made a related case for using a temporary SEC exemption while the commission studies tokenized stock trading. The Sept. 17 order imposes participant screening, trading limits, disclosure, records, issuer rights and the ordinary securities law bans on fraud and manipulation. It is an intervention with conditions, not an unregulated free pass. His argument is that an observed market can inform permanent rules better than a market that cannot start.
Coin Center, a crypto policy organization, made a different case within the same debate. Its March submission urged broad prospective rulemaking over individual relief, arguing that selective exemptions can favor applicants with the resources to seek them and leave decentralized projects outside. That criticism does not show the SEC order is improper. It identifies a question the order cannot settle: whether other workable models get an equivalent path.
Warner’s opposition to the Senate bill is another constraint on a simple ‘Congress failed, agencies solved it’ account. He said the dispute over ethics requirements involving elected officials prevented his support despite progress on national security issues. Rules from financial regulators about trading venues do not resolve the elected-official ethics issue that helped stop the vote. Banking groups’ concerns about rewards tied to stablecoin balances likewise involve a separate dispute over the boundary between payments and deposit competition. The missing legislation is missing for reasons the agencies’ crypto rulemaking cannot erase.
The decisive test is an ordinary spot trade
Take a customer who deposits dollars on an exchange, buys an unleveraged digital commodity and withdraws it to a wallet. The March interpretation helps describe the asset and the legal treatment of a particular sale. The SEC’s offering proposal could matter to an earlier fundraising transaction involving that asset. The tokenized stock order is irrelevant to this trade. The CFTC’s unpublished measure cannot yet be applied to it, and Selig’s public example centers on leveraged or margined trading.
Advertisement
What federally supervises that ordinary spot exchange’s routine operations? Existing anti-fraud powers, applicable state regimes and other federal obligations do not amount to the dedicated CFTC spot-market registration and supervision framework CLARITY sought to create. This is the part of the rulebook agencies cannot simply announce into existence. The difference is more than durability: it is the scope of the legal authority available in the first place.
That customer example is also a way to judge the feature’s claim. If Congress passes a law assigning broad spot digital commodity oversight, the gap narrows by statute. A crypto.news look at Bitcoin after the Senate vote addresses the asset’s current classification. If the CFTC publishes a measure that identifies an existing legal basis covering more of the ordinary spot transaction than Selig’s August remarks suggested, its precise terms will need to be examined. The Sept. 17 review listing alone does not answer either point.
The limits run in both directions. The failure of CLARITY did not repeal securities or commodities law, undo the SEC’s March interpretation, or stop agencies from proposing and issuing measures within their authority. The SEC stock exemption is real. So are its boundaries. The CFTC may yet publish a consequential proposal. Until it does, a filed title should not be asked to carry the weight of a completed rule.
What to watch
The CFTC proposal: Watch for publication of the text tied to RIN 3038-AF80 after executive review. Its treatment of unleveraged spot trading is the most direct test of its reach.
Advertisement
The SEC comment deadline: Comments on Regulation Crypto Assets are due Oct. 20, 2026, under the published proposal. Any subsequent final text could change the $5 million and $75 million routes.
The tokenized stock venues: Public venue notices, trading volume and issuer objections will show whether the SEC’s five-year exemption becomes a used market or remains an available permission.
The Senate’s next motion: A renewed effort to proceed to H.R. 3633, revised bill text or a new bipartisan agreement would change the legislative outlook. The Sept. 15 cloture vote did not decide final passage.
The spot exchange question: Any proposed CFTC registration requirements should be read for the products and transactions they cover, not only the number of exchanges that might apply.
Advertisement
FAQ
Did the CLARITY Act fail in the Senate?
The Senate rejected a motion to end debate on whether to proceed to H.R. 3633 on Sept. 15, 2026. Senators did not take a final passage vote. The legislation remains unresolved.
What was the actual CLARITY Act vote count?
The Senate’s official roll call records 49 yeas, 50 nays and one senator not voting. The motion needed 60 votes to advance.
Did the SEC and CFTC replace the CLARITY Act?
No. They have interpreted existing law, proposed rules and issued a limited exemption. Those actions do not enact the spot digital commodity framework that Congress considered.
Are the SEC’s $5 million and $75 million crypto exemptions available now?
They were proposed on Aug. 18, 2026. The published proposal calls for comments through Oct. 20; the new exemptions would need a final rule before taking effect.
Advertisement
What did the SEC allow for tokenized stocks?
Its Sept. 17 order temporarily permits qualifying venues to trade tokenized listed stocks through a defined permissioned model under conditions. The exemption runs to Sept. 17, 2031, unless modified.
Has the CFTC published its new crypto market rules?
The public Sept. 17 record identifies a CFTC measure at the prerule stage of White House review. It does not make a rule final or disclose the measure’s operative text.
Does the CFTC regulate all spot Bitcoin exchanges?
The CFTC has fraud and manipulation authority over spot digital commodities, but its general regulatory remit centers on derivatives and certain leveraged transactions. The proposed comprehensive spot exchange framework was part of CLARITY.
What happens if Congress never passes CLARITY?
The SEC and CFTC can continue acting under their existing statutes, and their measures can still matter to specific products. Whether they cover the wider spot market depends on the reach of those statutes and the text of future rules. This is educational analysis, not investment advice.
Advertisement
Disclaimer: This article is for information and educational purposes only and does not constitute financial or investment advice. Figures reflect regulatory filings and reporting available at the time of writing and change with each disclosure. Nothing here is a recommendation to buy, sell, or hold any security or asset. Always do your own research. Information is accurate as of September 24, 2025.
NYSE and Blockchain.com have agreed to explore distributing tokenized U.S. shares to a global crypto audience. The deal leaves the harder questions for the platform’s launch: whose record proves ownership, who decides who can trade, and how the new market stays tied to the shares beneath it.
Summary
NYSE and Blockchain.com signed a Sept. 23 memorandum covering access to tokenized shares and ETFs, subject to approvals.
Blockchain.com reported more than 44 million confirmed accounts, a distribution figure that is not a count of eligible investors.
The SEC’s separate Sept. 17 exemption caps qualifying venues at 75 Tier 1 and 250 Tier 2 stock symbols.
Third-party stocks under that SEC exemption require 30 days’ issuer notice and cannot trade if the issuer objects.
DTCC’s July 15 production trades used tokens representing securities held at DTC; its wider service targets October.
The New York Stock Exchange and Blockchain.com signed a memorandum of understanding on Sept. 23 to explore giving Blockchain.com customers access to tokenized U.S. stocks and exchange-traded funds. The route would run through NYSE’s planned digital alternative trading system, subject to required regulatory approvals. It is a plan for distribution, not a launch of stock trading to the company’s more than 44 million confirmed accounts.
NYSE is building a market that could operate at all hours and settle trades onchain. Blockchain.com brings a customer network already accustomed to digital assets. The announcement does not identify the final custody chain for each share, say which customers will qualify, or publish the terms under which a token could be converted back into a conventional holding. Those details decide what a buyer owns.
Advertisement
The answer will differ by product. A token can be the security recorded on a company’s shareholder file. It can represent an entitlement to a share held through an intermediary. It can instead be a contract that tracks a share’s price. All three can display a ticker on a phone. Only the first two can potentially carry the underlying shareholder interest, and even there the legal path to voting or dividends needs to be specified. The Securities and Exchange Commission drew those distinctions in a January staff statement on tokenized securities.
BREAKING: SEC grants temporary relief for venues trading tokenized U.S. stocks onchain.
The exemption allows eligible platforms to use permissioned automated market makers and liquidity pools for tokenized NMS stocks, creating a regulatory path for blockchain-based equity… pic.twitter.com/8fGYnNDZNT
The new agreement makes an old stock market question visible in a new format. A blockchain can record a transfer. It does not, on its own, determine which entity owes the holder a dividend, who can correct a mistaken transfer, or whose ledger a company treats as its shareholder record.
Advertisement
The Sept. 23 deal is a distribution agreement, not an open market
The parties called their agreement a memorandum of understanding. Their joint announcement says Blockchain.com’s user base would gain access to tokenized listed equities and ETFs through NYSE’s previously announced digital ATS after necessary approvals. The agreement covers a second business line: ICE Data Services plans to distribute Blockchain.com’s crypto data, while Blockchain.com plans to bring ICE and NYSE exchange data into its app.
That data arrangement could start informing users before they can buy any tokenized stock through the proposed venue. The announcement offers no launch date, approved securities list, country-by-country access rules or account-level eligibility figures. Forty-four million confirmed accounts measure an existing customer base. They do not measure approved brokerage accounts, funded investors, stock orders or future onchain volume.
The distinction matters because earlier ICE announcements already described several pieces of the same developing platform. In January, NYSE parent Intercontinental Exchange outlined a digital trading platform combining its Pillar matching engine with blockchain-based systems for custody and settlement. In March, NYSE named Securitize as its first prospective digital transfer agent able to mint blockchain-native securities for corporate and ETF issuers. The Sept. 23 deal adds a distributor and market data connection to that proposed structure. It does not say Blockchain.com becomes the transfer agent, the securities issuer or the operator of NYSE’s ATS.
NYSE Group President Lynn Martin told lawmakers on Sept. 2 that the planned platform would link digital equities directly to underlying shares and preserve voting rights, dividends and corporate actions. That is NYSE’s stated design. The signed customer terms, transfer records and regulatory approvals would show how it operates for a buyer. It is too early to treat the design statement as evidence that a particular token or distribution channel has gone live.
Advertisement
A crypto.news report on the new NYSE agreement covered the announcement and noted that the companies had not said their arrangement was approved under the SEC’s separate innovation exemption. The useful question now sits underneath the partnership: which existing institutions will keep authority over the shares when trading moves across a blockchain?
A wallet balance is not always the shareholder record
The SEC’s January staff taxonomy provides a route through the claims made for stock tokens. If an issuer or its agent places the security on a blockchain as part of its master shareholder file, moving the token can move the security in that official record. A company could maintain other records alongside the chain, including the holder’s legal name and address. The chain need not publish every detail of the register to be part of it.
There is a second issuer model. A share remains on an offchain master file, while an onchain token acts as an instruction that prompts the issuer or its agent to update that file. The token transfer and the legal ownership update are connected, but they are not literally the same database event. If the offchain update fails or is delayed, the reconciliation process matters more than the timestamp printed by a block explorer.
When a third party tokenizes a share held in custody, the token can represent a security entitlement instead of direct registration on the issuing company’s books. The company’s register may show a nominee or custodian. The customer has a legally defined interest through an intermediary chain, with the right to instruct or receive distributions according to that structure. Ordinary brokerage accounts already use forms of intermediated ownership. A blockchain token can change the transfer method without removing the intermediary.
Advertisement
The third-party synthetic model is different. A firm can issue its own security or contract that follows another company’s share price but gives the buyer no ownership claim against the company whose ticker is displayed. Dividends may be reflected through a contractual adjustment. Voting rights can be absent. The SEC says a buyer in that model may face the third party’s bankruptcy risk without holding the underlying company’s security.
These categories give a practical test for any token a consumer is shown. Find the document stating what the token represents. Identify who holds the underlying share, if anyone. Check whose records are legally authoritative when the token moves. Find the entity obliged to send a dividend or process a proxy vote. The ticker and the blockchain address cannot answer those questions alone.
The distinction has already caused friction. AMC Entertainment’s chief executive objected to an AMC-linked product offered offshore because, he said, the company had not issued or authorized it. Crypto.news examined the AMC and Robinhood dispute, including the difference between a tokenized exposure contract and a claim to the underlying share. That product should not be conflated with what NYSE has proposed. The episode shows why the phrase ‘tokenized AMC stock’ can conceal two different legal relationships.
Advertisement
DTC’s pilot keeps the original share inside the old system
The Depository Trust Company offers another way to locate control. On July 15, its parent DTCC announced production trades involving tokenized representations of assets held at DTC. More than 30 firms participated. The digital conversions ran on a private network and a public network. DTCC said the activity prepared for a tokenization service planned for October.
JUST IN: Ondo launches first tokenized stock representations on DTCC service
The initiative includes CRCLon and SPYon as digital twins of DTC-held securities pic.twitter.com/lx0QmlCYUu
Under that service, DTC participants can convert eligible DTC-held securities between conventional and tokenized forms and receive the digital representations in approved wallets. The underlying assets do not disappear from DTC because a token is issued. The token is a new representation within the securities custody and recordkeeping arrangement. DTC’s account records remain central to the structure.
Advertisement
That is a control choice. If DTC’s official books determine the participant’s interest, the blockchain is a transfer surface integrated with those books. Rules for wallet eligibility, reversals, corporate actions and reconciliation sit around it. The exact design can differ from an issuer keeping its master shareholder file directly onchain, even though both may advertise onchain settlement. A crypto.news report on a proposed regulated custody chain describes how the final customer can hold an entitlement while the official register still names a nominee.
NYSE’s eventual platform could connect to existing depository arrangements and to new digital transfer agents in different ways. Its January outline names multiple blockchains for custody and settlement. Its March Securitize agreement describes minting securities for issuers. The Sept. 23 Blockchain.com memorandum describes distribution. None of those announcements, taken alone, proves that every stock available on the eventual platform will use one identical registration and custody model.
There is a reason to keep the options open. A company that wants its agent to issue a token as the share itself has a different task from a broker seeking a transferable representation of stock already held at DTC. One starts at the corporate register. The other starts with an existing custodial position. Each can produce a tradable digital asset, but an investor’s claim passes through different hands.
The SEC’s statement on tokenized securities says the technology used to record the position does not by itself settle the legal characterization. For the buyer, that is the useful rule. Before asking how fast the token settles, ask where the share is.
Advertisement
The SEC’s new exemption governs a different kind of venue
On Sept. 17, the SEC issued release No. 34-106402, a five-year conditional exemption for certain Tokenized Securities Venues, or TSVs, using permissioned automated market makers and liquidity pools. It also grants conditional dealer-definition relief to specified liquidity providers. The 60-page SEC order is effective through Sept. 17, 2031, subject to modification.
The order does not say all tokenized securities venues are now exempt from exchange regulation. A TSV must meet the order’s particular conditions. It must verify that each eligible tokenized National Market System stock gives holders the same interest and the same dividend, voting and liquidation rights as a traditional share of the same class. It cannot host the primary issuance of the security under this exemption. Access must be permissioned, while the smart contracts used for the model must be public and auditable on a permissionless ledger. Crypto.news previously examined the holder-rights test in the order.
For a third-party tokenization unaffiliated with the company, the venue must give the company written notice and wait at least 30 calendar days before trading starts. A timely objection prevents trading that tokenized stock on that TSV. The requirement does not mean every stock-linked product everywhere needs the issuer’s consent. It is a condition of this specific exemption, which concerns securities carrying rights in the underlying share.
The NYSE agreement points to a planned digital ATS, a regulated venue category named by the partners. The SEC’s September order describes an exempt TSV model built around automated liquidity pools. No public statement in the Sept. 23 memorandum says the NYSE and Blockchain.com arrangement will rely on that order. Treating the exemption as the agreement’s approval would join two different records without evidence.
Advertisement
That separation is the feature’s central finding. The headlines describe a single arrival of stocks onchain. The documents describe at least three routes: an exchange-linked ATS under development, a conditional exemption for a particular pool-based venue, and DTC-backed tokenized entitlements. Each moves an equity claim through a different set of gatekeepers. A buyer needs the specific route, not the umbrella label.
The SEC order contains an unusually plain disclosure requirement. An exempt TSV cannot claim to be SEC-registered or imply the agency endorsed it. Its public notice must state that the venue is not registered as an exchange. Securities law bans on fraud and manipulation remain in force, but the venue does not acquire the full obligations of a registered exchange by being permitted to operate under an exemption. That is a meaningful distinction for a buyer weighing the safeguards attached to the trading venue.
The cap is 325 symbols, but volume is the tighter gate
The SEC divided eligible stocks under its TSV exemption into two tiers. A venue can trade no more than 75 Tier 1 symbols and 250 Tier 2 symbols. Add them and the maximum is 325 different symbols per TSV, subject to the rest of the order. The aggregate says nothing about how many stocks NYSE’s future ATS could list because NYSE has not said it will operate as an exempt TSV.
Each eligible stock also has a cap tied to trading in the conventional market. For Tier 1, a TSV’s average daily share volume cannot exceed 0.25% of the underlying stock’s average daily share volume in the prior month. For Tier 2, the limit is 2.5%. The figures in the SEC’s order are percentages of shares traded, not percentages of a company’s outstanding shares or market value.
Advertisement
Put both percentages against the same example of one million shares traded per day on the conventional market. A Tier 1 token would have room for 2,500 shares of average daily TSV volume. A Tier 2 token would have room for 25,000. The tenfold difference comes from the SEC’s tier treatment, not a forecast of investor demand. Real caps move with each stock’s prior-month volume, and affiliated TSVs must aggregate their activity under the order’s conditions.
If a venue exceeds a stock’s threshold after its first instance, it must stop trading that tokenized stock for three months. A venue may stop earlier to avoid breaching the cap. The rule makes the exemption suitable for a monitored opening of a market; it is not a promise that an exempt pool can absorb unlimited global orders around the clock. At a large enough scale, a successful venue could hit a ceiling built into its permission to operate.
The SEC explains why it imposed the limits. Automated market maker prices depend partly on the ratios of assets inside a pool. They may depart from prices on the conventional stock market. Keeping the pool small relative to the underlying share’s trading volume is intended to limit any disruption while the regulator observes the model. The price a buyer sees at 2 a.m. can be real for that pool while differing from the last conventional market price. The order itself treats that possibility as a market design problem.
Around-the-clock trading still needs an off switch
NYSE has advertised a digital platform designed for 24-hour trading. A clock without a closing bell does not mean a market without intervention. In its TSV order, the SEC requires the exempt venue to stop trading a tokenized stock at the same time the primary listing exchange halts or suspends trading in the underlying share. Reasons include a market-wide circuit breaker, material news or a listing problem. The venue must tell its users about the stoppage.
Advertisement
The off switch reveals who governs the token market in that model. The primary listing exchange’s decision travels into the onchain venue. A security does not become independent of its issuer, listing rules and national market protections when its trading record moves to a blockchain. How a separate ATS implements its own halt and reopening procedures will be set by the rules governing that venue; the TSV order should not be copied over to it without checking its filings.
Hours raise a second issue. The underlying company’s earnings release, dividend timetable and proxy process remain tied to corporate and securities law. An onchain pool can quote a price during a weekend, but its access to fresh price discovery, market makers and the ordinary exchange session will differ by hour. NYSE’s plan calls for continuous trading. It has not shown what spreads, depth or price protections a specific token will have on a Sunday.
Execution also depends on who supplies liquidity. The SEC allows certain firms supplying their own tokenized shares to an exempt pool to rely on conditional dealer relief. Their trading incentives and any arrangements with the venue must be disclosed under the order. The company whose shares are tokenized, the venue that controls access and the firm quoting against customers are separate actors. Calling the whole arrangement ‘decentralized’ would obscure those roles.
Issuer control and investor access pull in different directions
NYSE has a substantial case for its design. Martin’s September testimony says the company wants the token and conventional equity to be the same security in different forms, with the same rights. The SEC’s exemption separately requires equivalent rights and lets companies stop unaffiliated third-party tokens from trading under it. A holder may prefer a slower or more restricted path that can actually deliver a vote and a dividend over a token that offers only price exposure.
Advertisement
The counterargument is not simply that issuers should lose control. Distribution partners want investors in more countries to reach U.S. securities through an interface they already use. Blockchain.com executive Peter Smith made that access argument in the Sept. 23 announcement. An issuer notice requirement, permissioned access and volume limits could reduce the number of listings or buyers under the exempt TSV route. The question is which constraints protect ownership rights and which reflect a particular market design. Crypto.news covered the issuer veto dispute before the SEC’s order took effect.
There is evidence that the distinction matters commercially. NYSE’s agreement discusses its global distribution audience, while its prospective venue remains subject to approvals. DTCC’s tokenization service begins with DTC participants and approved wallets, a different customer entry point. The SEC’s TSV order permits a public chain for smart contracts but still requires the venue to approve participants. Public ledger access does not give every wallet holder permission to trade U.S. shares.
The SEC has heard objections from established market firms about granting special relief to venues outside the traditional exchange framework. Its order responds with disclosures, records, trading limits and a five-year term. Advocates of an open financial system may reasonably ask whether those limits narrow the audience too much. Issuers and investors may reasonably ask what happens to rights and market integrity if they are loosened. The records support both questions; they do not yet measure the cost of either choice in a live, large-scale U.S. stock token market.
One observation could challenge the concern that onchain trading merely adds gatekeepers. If a live platform shows verifiable ownership records, reliable transfers across approved venues, effective voting instructions and lower all-in costs for investors, the extra technology may simplify a chain of intermediaries. A second observation could challenge the access claim: accounts may be numerous while approved investors and actual trading stay small. Both tests require live disclosures, not launch language.
Advertisement
The launch question is who can correct a share transfer
At the point of a disputed transfer, the competing promises of tokenization become concrete. An investor may see a final blockchain transaction while a custodian, transfer agent or issuer’s master file shows a different owner. A mistaken corporate action may credit the wrong wallet. A key may be lost. A sanctioned account may need to be blocked. The documents defining which record controls and who can amend it decide how such cases are handled.
Issuer-sponsored stock can make the chain itself part of the master file. A custodial token can make the chain an entitlement record linked to shares held elsewhere. NYSE’s intended platform may support more than one settlement path, while DTCC is developing tokenized representations within its existing custody structure. The precise legal and technical link has to be documented for every product made available. It cannot be assumed from a partnership announcement.
The SEC’s TSV order requires a venue to explain its tokenization process, assess the legal status and technical integrity of each security, and disclose how it verified equivalent holder rights. It requires information about smart contracts, onchain and offchain functions, access rules, trading interruptions and affiliated trading. These notices would make it possible to test a venue against its claims once one operates under the order. They are not proof that NYSE’s proposed ATS will use the same design.
What happens next is checkable. NYSE must disclose the approvals and operating rules for its digital ATS before its proposed Blockchain.com distribution route can be assessed as a live market. The partners need to name the securities available, eligible jurisdictions and the legal interests delivered to users. DTCC’s planned October service launch will offer another view of how tokenized positions are kept in sync with shares held in conventional custody. The SEC will collect comments on its separate exemption as venues test it.
Advertisement
For a person buying a tokenized share, the shortest useful question remains the hardest one: if the wallet, venue and shareholder record disagree, whose entry wins?
What to watch
NYSE’s ATS filings: Look for the operating rules, approved trading hours and settlement design of the digital venue named in the Sept. 23 memorandum.
The first stock terms: Check whether a token is the share itself, a custodial entitlement, or a price-linked contract, and who handles votes and dividends.
Country-level eligibility: Compare Blockchain.com’s 44 million confirmed accounts with the jurisdictions and users actually permitted to trade U.S. securities.
Advertisement
DTC’s October launch: Watch for the planned wider tokenization service and details of conversion between conventional and tokenized positions.
Exempt TSV notices: Track issuer objections, eligible symbols, affiliated liquidity and any volume pauses under SEC release No. 34-106402.
FAQ
Can Blockchain.com users trade tokenized NYSE stocks now?
The Sept. 23 memorandum sets out a plan for access through a proposed NYSE digital ATS. The companies made that plan subject to necessary regulatory approvals and did not announce a launch date.
Does a stock token always make its buyer a shareholder?
No. An issuer-backed token may be the security, a custodial token may represent an interest in a held share, and a synthetic token may only track its price. The legal terms determine the buyer’s rights.
Advertisement
How many tokenized stocks does the SEC exemption allow?
An exempt TSV can trade up to 75 Tier 1 symbols and 250 Tier 2 symbols, for 325 in total, subject to other conditions. Those caps do not automatically apply to NYSE’s planned ATS.
Can a company block a third party from tokenizing its shares?
Under the SEC’s TSV exemption, the issuer has 30 calendar days after written notice to object to trading a third-party tokenized version of its stock on that venue. Other products and venues require separate legal analysis.
Will tokenized stocks include votes and dividends?
Stocks traded under the SEC’s TSV exemption must convey the same voting, dividend and liquidation rights as equivalent conventional shares. A synthetic product can follow a stock price without conveying those shareholder rights.
Does the blockchain replace DTCC or transfer agents?
It depends on the model. DTCC’s service represents assets held at DTC, while an issuer or its transfer agent may place the official shareholder file partly or wholly onchain. Neither design follows automatically from displaying a token in a wallet.
Advertisement
Can a tokenized stock keep trading during a halt in its underlying share?
An exempt TSV must stop trading the token concurrently with a halt or suspension on the primary listing exchange. A different venue’s controls must be read from its own rules.
What should an investor check before buying a tokenized share?
Identify the legal issuer, the location of the underlying share, the official ownership record, the route for voting and dividends, and the venue’s access and halt rules. This is educational analysis, not investment advice.
Disclaimer: This article is for information and educational purposes only and does not constitute financial or investment advice. Figures reflect regulatory filings and reporting available at the time of writing and change with each disclosure. Nothing here is a recommendation to buy, sell, or hold any security or asset. Always do your own research. Information is accurate as of September 24, 2025.
Crypto exchange Bitget says it has detected an unauthorized transfer event that affected approximately $351.6 million worth of assets, and it has temporarily suspended withdrawals while it investigates. The incident was identified after Bitget’s security systems flagged suspicious activity involving a limited set of hot wallets around 18:31 UTC on Thursday.
In a live Q&A, Bitget CEO Gracy Chen said the breach was contained to a portion of the exchange’s hot and warm wallet infrastructure, while its cold wallets remained secure. She also indicated that withdrawals are expected to restart within hours to days, and that the exchange is working with law enforcement and onchain security firms.
Key takeaways
Bitget reported unauthorized transfers totaling about $351.6 million and temporarily halted withdrawals.
The company says only a limited number of hot wallets were involved, with cold wallets remaining secure.
Chen cited exposure across multiple networks, with Ethereum representing the largest concentration of the observed stolen funds.
Bitget said customer balances remain accurate and deposits and trading continue.
Bitget claims the losses are more than covered by its User Protection Fund, which it says holds over $464 million.
What Bitget says happened
According to Bitget’s public statement, its security monitoring systems identified unauthorized transfers linked to a small number of hot wallets at 18:31 UTC on Thursday. The exchange then initiated emergency response procedures.
Chen said the incident was confined to certain hot and warm wallet layers. She emphasized that Bitget’s cold wallet setup—typically used to hold the majority of assets offline—was not compromised. This distinction matters because it suggests the attack vector likely targeted operational wallet components rather than Bitget’s offline reserves.
Scope of affected assets and networks
Chen said affected assets included Ether (ETH), XRP (XRP), USDt (USDT), USDC (USDC), Avalanche (AVAX), BNB (BNB), and USDT0 (USDT0) on Arbitrum. She also identified the networks involved as Ethereum, the XRP Ledger, Avalanche, BNB Smart Chain, and Arbitrum.
Advertisement
While Bitget disclosed multiple tokens and multiple networks, Chen pointed to Ethereum as accounting for the main concentration of the observed stolen funds. That detail is important for market participants and onchain analysts because it indicates where investigators may find the clearest trail of movement first—particularly when early reporting is based on initial onchain sightings.
Bitget also addressed a discrepancy between early onchain reporting and its later figure. Chen said the initial estimate appeared lower because the unauthorized activity extended beyond the Ethereum-focused activity captured in early onchain analysis.
Withdrawal suspension and ongoing operations
Bitget temporarily suspended withdrawals during its security review. Chen said the exchange expects withdrawals to resume within a matter of hours or days, implying a staged restoration process rather than an immediate return to full throughput.
At the same time, Bitget stated that user account balances remain accurate and that deposits and trading are continuing normally. For users, that combination—trading functionality intact but withdrawals paused—signals that Bitget likely prioritized liquidity protection and operational controls while it determines how funds moved and what portion can be recovered or compensated.
Advertisement
Bitget said it flagged addresses associated with the transfers and that it had contacted law enforcement and onchain security firms. Those steps typically aim to both support forensic tracing and reduce the likelihood of further movement through blacklisted or monitored pathways.
Compensation stance and promised reporting
Chen said the affected funds are more than covered by Bitget’s User Protection Fund, which she said currently holds more than $464 million. The claim is meant to reassure users that the exchange has a buffer to compensate for losses, even though the final outcome—such as whether any portion is recovered—still depends on the investigation.
Bitget also said it will provide hourly updates and publish a full incident report within 24 hours. The report is expected to include a root-cause analysis and corrective actions, which investors and system auditors will likely focus on to understand how the breach reached hot and warm wallet layers and what controls will be revised to prevent recurrence.
The exchange’s approach—rapid operational containment, public disclosure of token and network scope, and a defined timeline for deeper technical reporting—will be closely watched by users at other exchanges as well. Security incidents often lead to heightened scrutiny of wallet architecture, signing workflows, and monitoring thresholds, particularly when hot wallet access is implicated.
Advertisement
For now, traders and users should watch whether Bitget meets its withdrawal-resumption timeframe and whether the promised incident report clarifies the precise entry point and the corrective measures for hot and warm wallet handling—especially since early onchain estimates differed from the exchange’s later, broader figure.
Risk & affiliate notice: Crypto assets are volatile and capital is at risk. This article may contain affiliate links. Read full disclosure
A visitor walks by a billboard for AI as they attend the PT Expo on September 22, 2026 in Beijing, China.
Kevin Frayer | Getty Images News | Getty Images
BEIJING — Chinese President Xi Jinping told U.S. President Donald Trump that there is more opportunity for cooperation than competition on artificial intelligence.
That’s according to a state media readout of the two leaders’ meeting in the White House Oval Office Thursday local time.
Advertisement
“The two sides can continue AI dialogue, exchange views on risks and benefits, and together guard against the misuse or malicious use of AI,” Xi said in Chinese, according to a CNBC translation of the state media readout.
He noted AI is important to both the U.S. and China. “Both sides have competition. Cooperation, even more so,” he said.
Xi also emphasized that humans should maintain control of the technology, and that AI should support human progress.
Read more Trump-Xi meeting coverage
The U.S. has restricted China’s ability to access advanced semiconductors for training AI models, and criticized Chinese companies for allegedly taking part in illicit distillation of American AI capabilities.
Advertisement
Recent incidents have raised fears that increasingly autonomous AI models could make attacks faster and harder to contain.
Following a meeting with Chinese negotiators in New York, U.S. Treasury Secretary Scott Bessent said earlier this week the two sides had discussed setting up a “U.S.-China AI Dialogue.” He said the U.S. proposed introducing an alert system for AI incidents.
Bitcoin climbed past $87,000 after a rate increase that should have made risk harder to own. The public record identifies several sources of demand, but it cannot put a name to every buyer or turn fund inflows into a complete account of the rally.
Summary
The Fed raised its target range to 3.75% to 4.00% on September 16.
US spot Bitcoin ETFs lost $746.3 million across September 15 and 16.
Those funds then gained about $2.65 billion across five sessions through September 23.
Strategy bought 950 BTC for $75.7 million during September 14 to 20.
Bitcoin reached roughly $87,300 on September 21 before slipping toward $84,000.
Bitcoin’s rally after the Federal Reserve raised interest rates has an answer that can be measured, though not a single buyer who can be named. Money returned to US spot Bitcoin exchange traded funds. A public company resumed purchases. Traders caught on the wrong side of the rise had to close positions. By September 21, Bitcoin had moved above $87,000, then surrendered part of the gain two days later.
The timing matters. The Federal Open Market Committee raised its target range by a quarter point to 3.75% to 4.00% on September 16. Its September projections put the median year end policy rate at 4.1% in both 2026 and 2027. In June, those medians were 3.8% and 3.6%. The Fed did not promise a cut.
Advertisement
JUST IN: Chance of a September Fed rate hike rises to 81% on Polymarket
The odds for a 25-basis-point hike jumped after August CPI, with core inflation rising 0.3% m/m versus 0.2% expected. pic.twitter.com/Yf6ztlzGnW
A hike had been expected by many traders. Expectations alone, however, cannot account for the subsequent purchases. The useful question is narrower: which observable channels brought demand into Bitcoin after the decision, and which claims about the buyers go beyond the evidence?
The funds first lost $746 million
Farside Investors’ daily fund table records $450.4 million of net withdrawals from US spot Bitcoin ETFs on September 15 and another $295.9 million on the day of the Fed decision. Add them: $746.3 million left over two trading sessions. The decision was hardly greeted by an immediate flood into the funds.
Advertisement
The direction changed on September 17. Funds took in $159.5 million, followed by $433.0 million on September 18, $999.0 million on September 21 and $714.7 million on September 22. SoSoValue’s September 23 figures, reported by crypto.news, add $346.98 million for a fifth consecutive positive session.
Together, the five figures total $2,653.18 million. Subtract the $746.3 million of withdrawals from September 15 and 16 and the eight trading days show a net $1,906.88 million entering the funds. The latter is an accounting window, not a measure of money that bought Bitcoin at the rally’s exact hour. It is the net of two sharply different periods, and reporting only the five positive sessions would conceal the withdrawals immediately before the turn.
There is a data trap here. An earlier snapshot of Farside’s September 23 table showed only $32.4 million, with several issuers’ entries still blank. The later SoSoValue reading included $166.29 million for BlackRock’s IBIT and $143.24 million for Fidelity’s FBTC, among other reported fund flows. Treating a blank as zero would understate that day’s total by more than $300 million. These are dated snapshots, and totals can change when issuers report.
The apparent buyers changed between Monday and Wednesday
Monday’s $999.0 million was spread among several funds. Farside recorded $381.4 million for BlackRock’s IBIT, $289.1 million for ARK 21Shares’ ARKB and $238.8 million for Fidelity’s FBTC. Combined, those three accounted for $909.3 million, or about 91% of that day’s total. This identifies fund vehicles, not the institutions or people placing orders through them.
Advertisement
Tuesday’s flow was $714.7 million in Farside’s later table. IBIT received $350.3 million and FBTC $257.4 million. Those two accounted for about 85% of the daily total. By Wednesday, Bitcoin had retreated toward $84,000 even as SoSoValue reported another $346.98 million into the funds.
That final pairing is as important as the Monday surge. A positive ETF print does not guarantee a positive Bitcoin session. Fund subscriptions are one channel of net demand; sellers on exchanges, derivatives positions and the timing of fund hedging all affect the price. The five day fund streak establishes persistent subscriptions. It cannot prove those subscriptions alone pushed Bitcoin through $87,000.
The concentration figures matter for the same reason. On Monday, IBIT, ARKB and FBTC supplied more than nine tenths of net additions; that does not mean three asset managers independently decided to buy Bitcoin with their own balance sheets. A fund can receive orders from brokerage customers, registered advisers and institutions. The issuer reports the fund level flow. Its table does not sort the orders by investor type. Calling all $999 million institutional buying would add a claim the data do not contain.
Advertisement
Monday and Wednesday also illustrate why two kinds of accounting should stay separate. A fund flow is a net change in assets associated with subscriptions and redemptions. A traded fund share can change hands repeatedly between investors in the secondary market without producing the same amount of new fund creation. Price, exchange turnover and ETF net flow are different measurements. A headline can be accurate on one and misleading on another.
ETF inflows are net creations or subscriptions valued in dollars, not a public register of every underlying investor or a second by second ledger of coins bought. Market makers and authorized participants can bridge a fund trade and its underlying hedge at different times. Nor does a dollar flow translate into an exact Bitcoin quantity without choosing a price and knowing when the exposure was acquired. Converting $999 million into BTC at the day’s closing quote would produce an illustration, not an audited purchase count.
A corporate purchase is real, but its clock is different
Strategy provides a named buyer. Its September 21 Form 8-K reports the purchase of 950 BTC for $75.7 million, including fees and expenses, at an average $79,670 per coin. The transactions occurred between September 14 and September 20. The filing gives the period, not the individual trades’ timestamps.
That distinction rules out an easy claim. Strategy’s announcement landed on September 21, when Bitcoin rallied, but the filing does not show that Strategy bought Bitcoin during Monday’s surge. Its purchase may have happened before, after or across the September 16 rate decision. It used existing USD Cash and said it issued no shares through its at the market program during the period.
Advertisement
Strive’s September 21 filing identifies another corporate buyer: 1,355 BTC at an average price of roughly $79,475 during September 14 to 18. Its disclosure has the same dating problem for anyone trying to explain a particular candle. The combined reported 2,305 BTC shows corporate accumulation over overlapping periods; it does not measure corporate buying on September 21.
Strategy’s 950 BTC can be compared with its own past and future disclosures. It cannot simply be added to $2.65 billion of ETF inflows and called total market demand. The windows overlap, the units differ and other buyers and sellers are missing.
Some buyers were closing losing bets
The other identifiable class of buyer did not necessarily want to own Bitcoin for months. A trader short a Bitcoin perpetual or futures contract must buy back exposure to exit. If price rises quickly, liquidation can force that purchase. Those buy orders can add fuel to the move that made the short untenable.
Nansen senior research analyst Nicolai Sondergaard described the rally as a combination of ETF demand and short covering. A September 23 crypto.news account quoted CoinMarketCap research lead Alice Liu saying covering, rather than new buying, drove much of the rise. These are analysts’ interpretations, not a trader by trader audit.
Advertisement
One check comes after the peak. A CryptoQuant analyst’s exchange data, cited by crypto.news, showed Binance Bitcoin open interest falling from about $5.4 billion to $4.9 billion between September 21 and 23. Bitcoin had declined by then. Falling open interest shows positions closed, but it does not, on its own, separate shorts closed during the rally from longs unwound during the retreat. The $500 million change is a change in the dollar value of outstanding positions, not $500 million of confirmed short buying.
No comprehensive public tape identifies the beneficial owner behind each ETF order and each derivatives close. A forced short buy and a patient fund subscription may both lift demand, but they imply different things about what happens when price stops climbing.
The strongest case for lasting demand has a limit
There is a serious argument that the inflows represent more than a squeeze. Five consecutive positive fund sessions, worth $2.65 billion, spanned the climb and continued on September 23 after the pullback. The purchases were not confined to one fund. IBIT, FBTC and ARKB all drew substantial cash on September 21. Corporate filings show at least two companies buying during the surrounding week. Those are observable commitments, regardless of the Fed’s posture.
The opposing interpretation has a different strength. Bitcoin’s move to about $87,300 did not hold; price was back near $84,000 by September 23. The ETF print records subscriptions during a day, while the price reflects all orders at their execution times. If new fund cash keeps arriving as Bitcoin falls, it means sellers are meeting it. That does not make the fund demand imaginary. It means its price impact cannot be read directly off its dollar total.
Advertisement
Recent crypto.news coverage of the ETF streak reported the pullback alongside continuing inflows and falling Binance open interest. Those facts support a mixed account: underlying fund demand was present, while leverage amplified and then retreated from the move. The public numbers do not tell us the exact share attributable to each.
JUST IN: BitMine Chairman Tom Lee says Q4 could ignite one of the biggest market rallies of our lifetime
Lee’s outlook comes as Bitcoin rebounds from its summer lows, while broader markets face catalysts including the Federal Reserve’s rate decision, easing financial conditions… pic.twitter.com/zXGWtrlsBj
For a cleaner test, compare the next complete fund reports with the path of open interest after the rally. If subscriptions remain large while open interest stops contracting, the evidence for demand beyond traders closing shorts strengthens. If subscriptions dry up and the price keeps slipping, Monday’s surge looks more dependent on temporary buying. Neither pattern proves causation on its own, because the public series are aggregated across markets and reported at different frequencies.
Advertisement
There is a second timing problem. Bitcoin trades around the clock; US listed fund shares trade during US market hours. The biggest crypto move can happen before an ETF session opens or after it closes. A daily ETF total cannot be laid over a 24 hour Bitcoin candle as though both cover identical hours. Any precise account of Monday would require intraday spot order flow, fund creation timing and derivatives transactions on a common clock. The available public daily series fall short of that standard.
The Fed did not become a buyer’s signal
The Fed’s September statement said inflation remained elevated and economic activity was expanding at a solid pace. Its 2026 and 2027 median rate projections of 4.1% are each higher than in June. The September projection table is a set of participants’ assessments of appropriate policy, not a binding schedule of decisions, but it offers little support for a claim that a near term rate cut drove the immediate rally.
A risk asset can rise after a hawkish decision if the surprise was already priced, other yields fall, or buyers in its own market outweigh macro pressure. Those are possible mechanisms, not proof that one explains this week. The observed fund reversal begins September 17, one day after the announcement. By September 21 it was large enough to see without a macro theory: $999 million in reported net subscriptions.
The more revealing development came when price and subscriptions parted ways on September 23. That is where the original question becomes testable. If fund creations keep coming while short positioning stays less crowded and Bitcoin holds its gains, the evidence for sustained cash demand improves. If creations turn negative and the price loses the levels recovered after the decision, the short squeeze explanation gains weight. Neither result can assign every past trade to an individual investor.
Advertisement
What the public record can actually name
The records identify funds, companies and position types. They do not name the ultimate owner of IBIT shares purchased on September 21. They do not date Strategy’s 950 BTC to Monday. They do not show that every liquidation produced a spot Bitcoin purchase on an exchange.
What they do show is enough to reject two simple versions of the story. Bitcoin did not rally because investors immediately celebrated the September 16 hike: ETF funds lost a combined $746.3 million on September 15 and 16. Nor was the rebound just a chart artifact with no recorded cash demand: about $2.65 billion entered spot funds over the next five sessions, on the figures available September 24.
A public filing adds 950 BTC of Strategy purchases during September 14 to 20, while Strive reports another 1,355 BTC during September 14 to 18. Short covering plausibly accelerated the price move, but no audited decomposition of its contribution has been published. The answer is a set of buyers, operating on different clocks.
JUST IN: Public companies added only 5,900 $BTC in Q3 2026 as corporate Bitcoin buying slows sharply.
Glassnode data shows corporate treasuries now hold Bitcoin at an average cost of about $80,500, leaving the group roughly 6% underwater at current prices. pic.twitter.com/2CSGmrCGkR
Daily ETF creations: Check the complete issuer table after every fund has reported; a blank cell is not a zero.
Fund concentration: A positive total spread across IBIT, FBTC and ARKB differs from one driven by a single product.
Open interest with price: Rising price and falling open interest can fit short covering; falling price and falling open interest can reflect long unwinds.
Advertisement
Corporate filings: Read transaction windows in each 8-K before assigning a purchase to a specific trading day.
Price against flows: Compare Bitcoin’s daily close with that day’s fund subscriptions. The September 23 divergence deserves more attention than an inflow headline alone.
FAQ
Did the Fed cut rates in September 2026?
No. It increased the target federal funds rate by a quarter percentage point to 3.75% to 4.00% on September 16.
How much entered Bitcoin ETFs after the Fed decision?
Reported net inflows across September 17, 18, 21, 22 and 23 totaled about $2.65 billion, using Farside’s earlier daily figures and SoSoValue’s completed September 23 reading.
Advertisement
Did ETFs buy Bitcoin on the day of the hike?
Fund flow data show a net $295.9 million withdrawal on September 16. The figures are daily net subscriptions, not a complete record of every underlying trade during the Fed announcement.
Which Bitcoin fund drew the most on September 21?
BlackRock’s IBIT led Farside’s table with $381.4 million. ARK 21Shares’ ARKB followed with $289.1 million, then Fidelity’s FBTC with $238.8 million.
Did Strategy buy Bitcoin during the September 21 rally?
Its filing does not establish that. Strategy reported 950 BTC bought between September 14 and 20 and announced the purchases on September 21.
Was the rally only a short squeeze?
The public record does not support that conclusion. Short covering was cited by market analysts, but spot Bitcoin funds registered substantial net subscriptions across five trading sessions.
Advertisement
Why did Bitcoin fall while ETFs still recorded inflows?
Bitcoin moved back toward $84,000 by September 23 while funds recorded $346.98 million of net inflows. Other selling and position changes can outweigh one channel of demand.
Can these figures identify who ultimately bought Bitcoin?
They identify fund vehicles and disclosed corporate purchasers, not every beneficial owner or trade. This is educational analysis, not investment advice.
Disclaimer: This article is for information and educational purposes only and does not constitute financial or investment advice. Figures reflect regulatory filings and reporting available at the time of writing and change with each disclosure. Nothing here is a recommendation to buy, sell, or hold any security or asset. Always do your own research. Information is accurate as of September 24, 2026.
European financial watchdogs have warned on Sept. 23 that sufficiently advanced quantum computers could undermine cryptography securing blockchains, while CryptoQuant founder Ki Young Ju estimates 6.89 million BTC may have public-key exposure relevant to a future quantum attack.
Summary
EU financial watchdogs warn quantum computing could undermine cryptography securing blockchains, transactions, databases and communications.
CryptoQuant founder Ki Young Ju estimates 6.89 million BTC may face future quantum exposure risks.
EU states should begin post-quantum migration by 2026, protecting high-risk uses no later than 2030.
Bitcoin developers have proposed quantum-resistant migration paths, but consensus and legacy coin handling remain unresolved.
The Joint Committee of the European Supervisory Authorities, comprising the European Banking Authority, European Insurance and Occupational Pensions Authority and European Securities and Markets Authority, warned that quantum computing could create major risks for cryptographic systems protecting transactions, communications, databases and blockchains.
The Sept. 23 Autumn 2026 risk update did not say a machine capable of breaking Bitcoin cryptography exists today. Its warning focused on preparation, noting that quantum-related security risks could emerge before commercially useful quantum applications become practical.
Advertisement
EU watchdogs say cryptographic risks could emerge early
In its risk update, the Joint Committee said quantum computing could improve financial processes, pricing, fraud detection and compliance monitoring. The same technology could eventually weaken cryptography used throughout financial infrastructure. The authorities wrote that “risks posed could also materialise faster than any commercially viable application.”
A separate ESMA technical analysis published in May examined the mechanics in more detail. It said sufficiently advanced quantum computers could use Shor’s algorithm against public-key schemes including RSA and elliptic-curve cryptography, or ECC. Bitcoin relies on elliptic-curve signatures for ownership and transaction authorization.
ESMA stressed that such attacks remain beyond current noisy intermediate-scale quantum, or NISQ, machines. Its report said systems capable of threatening existing cryptography are not expected immediately, but long migration periods make early preparation necessary.
Advertisement
IBM has taken a similar position on timing. The company said in April that fault-tolerant quantum systems could begin approaching cryptographic relevance by the end of the decade. IBM has not said a Bitcoin-breaking quantum computer exists now.
Bitcoin quantum exposure estimates depend on methodology
The amount of Bitcoin potentially exposed to a future quantum attacker remains disputed because researchers count address types and reused keys differently.
CryptoQuant founder Ki Young Ju estimated in February that approximately 6.89 million BTC could face quantum exposure under his methodology. His figure included roughly 1.91 million BTC associated with directly visible public keys and other coins whose keys may have been revealed through previous spending behavior. The estimate included dormant holdings attributed to early Bitcoin users.
Glassnode later produced a different calculation. Its May research measured 6.04 million BTC, or 30.2% of issued supply, as having public-key exposure at rest. Within that total, Glassnode classified 1.92 million BTC as structurally exposed because the output type reveals the key by design.
Advertisement
The Glassnode framework includes early pay-to-public-key outputs, bare multisig outputs and Taproot outputs in the structural category. Operational exposure covers situations where address reuse, partial spending or custody practices make a key visible while coins remain associated with it.
As crypto.news reported in its coverage of Bitcoin quantum exposure measured by Glassnode, the firm’s narrower structural measure put 1.92 million BTC directly in the category where public keys are revealed by design.
Exposed public keys create the Bitcoin-specific risk
Bitcoin ownership depends on digital signatures. For several common address formats, a public key may remain hidden behind a hash until coins are spent. Other output types expose the public key from creation, while address reuse can leave previously hidden keys visible onchain.
BIP-360, currently listed as a draft in the official Bitcoin Improvement Proposal repository, proposes Pay-to-Merkle-Root outputs designed to reduce long-exposure attacks against elliptic-curve keys. Its specification identifies P2PK, reused outputs and Taproot outputs among categories with long-exposure risk.
Advertisement
The proposal does not claim to solve every quantum attack path. BIP-360 notes that protection against an attacker deriving a key while a transaction waits for confirmation may require a post-quantum signature scheme.
BIP-361 addresses migration policy. The draft would eventually prevent new funds from being sent to quantum-vulnerable output types and later tighten spending rules for legacy ECDSA and Schnorr signatures. Its timetable begins only after a post-quantum output type is implemented and activated.
As crypto.news detailed in its Bitcoin BIP-360 and BIP-361 migration coverage, developers continue debating how dormant or inaccessible coins should be handled if legacy signatures eventually become unsafe.
Neither BIP is an activated Bitcoin consensus rule. The official BIP repository lists BIP-360 and BIP-361 as drafts, leaving the technical standard and migration policy unsettled.
Advertisement
Europe wants post-quantum migration to start in 2026
The European Commission already has a transition timetable covering public institutions and critical infrastructure. Its post-quantum roadmap calls for all EU member states to begin moving toward post-quantum cryptography by the end of 2026. High-risk use cases should complete the transition no later than the end of 2030.
The roadmap grew out of a Commission recommendation issued in 2024 and a coordinated implementation plan adopted in June 2025. A Sept. 2, 2026 consultation update said respondents favored clear deadlines, risk-based prioritization, hybrid cryptographic approaches and crypto-agility.
ESMA’s May paper set out another concern known as “harvest now, decrypt later.” Attackers can collect encrypted information today and store it until future computers become capable of decrypting it. The regulator said the long useful life of some financial information makes migration planning a multi-year security task.
For blockchains, migration involves an extra problem because existing assets and keys may need to move before older signature systems become unsafe. Bitcoin changes require consensus across developers, miners, businesses, wallet providers and node operators before new consensus rules can become active.
Advertisement
Institutional custodians have begun preparing without waiting for Bitcoin to choose a final signature system. In related coverage, crypto.news reported that Coinbase is designing post-quantum Bitcoin custody capable of supporting multiple potential signature schemes. Coinbase Chief Cryptographer Yehuda Lindell said the company wants its custody architecture to remain usable regardless of which system a blockchain ultimately adopts.
Ledger CTO Charles Guillemet has separately argued that migration may take years because changing wallets, custody systems and existing holdings can be harder than selecting a post-quantum algorithm. Crypto.news reported that Bitcoin’s quantum migration remains a wallet and coordination challenge while BIP-360 and BIP-361 remain drafts.




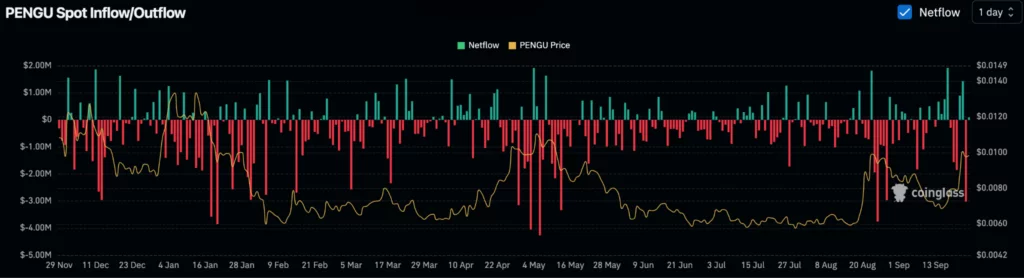
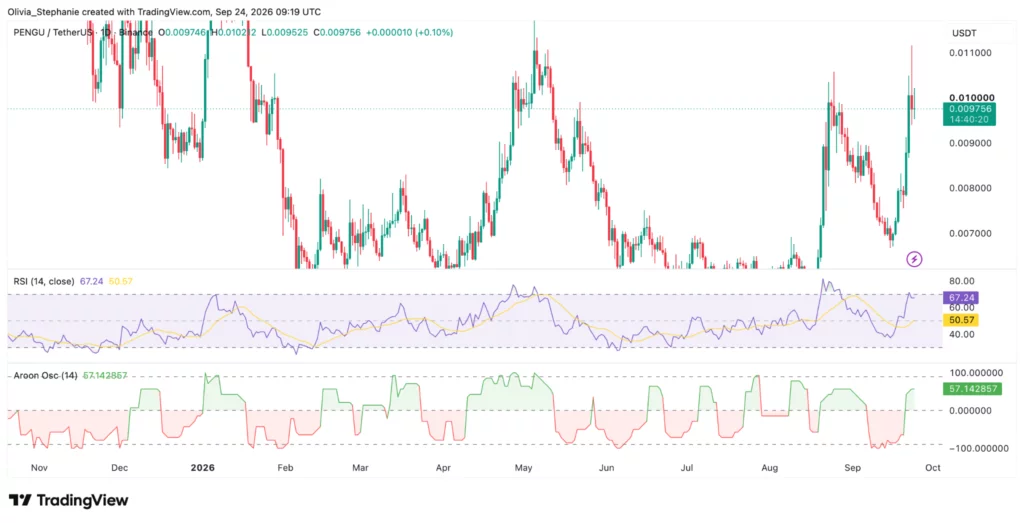










































You must be logged in to post a comment Login