
Crypto World
Dollar General EVP Reardon Sells 5,578 Shares

Kathleen A. Reardon, EVP & Chief People Officer of Dollar General (NYSE:DG), sold 5,578 shares of common stock on Sept. 3, 2026, according to a recent SEC Form 4 filing.
Transaction summary
Transaction value based on SEC Form 4 weighted average sale price ($131.33); post-transaction value based on Sept. 3, 2026, market close ($131.26).
Key questions
-
What is the significance of the transaction size relative to the insider’s equity position?
Reardon traded shares equal to 8% of the direct stake held before the filing, maintaining a core position of 61,071 shares. -
What was the price context of the execution?
The shares were sold at a weighted average price of $131.33, with individual executions occurring within a price range of $131.24 to $131.41. -
What is the current market value of the remaining equity holdings?
As of the Sept. 3, 2026, market close, the executive’s direct position in the discount retail chain is valued at $8 million.
Company Overview
Company Snapshot
-
Dollar General operates an extensive discount retail network across the southern, southwestern, Midwestern, and eastern United States, offering a diverse product assortment centered on consumable items, including household essentials, food and grocery products, personal care items, and general merchandise.
-
The company generates revenue through a high-volume, low-margin retail model that emphasizes value pricing and convenient store locations, primarily targeting price-conscious consumers seeking everyday essentials and household goods.
-
Dollar General’s primary customer base consists of middle and lower-income households across rural and urban markets who prioritize affordability and convenience in their purchasing decisions.
Dollar General is a significant player in the U.S. discount retail sector, with a substantial operational footprint, supported by approximately 194,000 employees, and TTM revenues of $43.6 billion. The company’s strategic positioning focuses on delivering value-oriented merchandise to underserved markets, leveraging its extensive store network and efficient supply chain to maintain competitive pricing advantages. With a market capitalization of $28.9 billion and TTM net income of $1.7 billion, Dollar General demonstrates the scalability and profitability potential of the discount retail model in serving price-sensitive consumer segments.

Aurora Innovation (NASDAQ:AUR) is preparing to expand its autonomous-trucking operations through a second-generation hardware rollout, a planned transition toward a driver-as-a-service model and additional manufacturing relationships, Co-founder and CEO Chris Urmson said at the Morgan Stanley Laguna conference.
Urmson said Aurora began driverless operations last year and launched its second-generation hardware in April. The newer system is intended to support commercial scaling, with Aurora expecting it to enable production of roughly 1,500 tractors. He said the technology is more reliable and lower-cost than the company’s first-generation hardware and is designed to support Aurora’s unit-economic profitability goals.
Production ramp and next-generation hardware
→ 2 Stocks Breaking Out Post-FOMC With One Thing in Common
Aurora expects to end the current quarter with 20 to 25 trucks in operation and plans to reach a production rate of 20 trucks per week in the fourth quarter, Urmson said. The company is working with Roush in Livonia, Michigan, to upfit International trucks with the Aurora Driver system before delivering vehicles to customers.
Urmson said Aurora expects the Roush-supported operation to reach an annualized run rate of about 1,000 units. He also said Volvo has publicly indicated it expects to launch autonomous Volvo VNL trucks in the first quarter of next year and to have more than 300 trucks on the road next year. Urmson said those vehicles would predominantly, if not entirely, be powered by Aurora’s technology.
→ Generac Plugs into Amazon for an $8B AI-Powered Deal
The company plans to introduce third-generation hardware with supplier AUMOVIO, a Continental spinout, over the course of next year and into 2027. Urmson said the system is intended to support production at automotive scale, potentially reaching tens of thousands of units. Aurora has worked with AUMOVIO for several years on the supply chain, manufacturing and design of the hardware, he said.
According to Urmson, Aurora’s second-generation system cuts hardware costs by more than 50% and offers roughly three times the durability of its first-generation equipment. Those improvements are intended to lower amortized costs per mile.
Customer demand and operating model
→ 3 Nimble Free Cash Flow Names With Light Assets
Urmson said Aurora is fully allocated for 2026 and is seeing a faster path from initial discussions to customer contracts. The company works with customers including FedEx, Werner, Hirschbach, Detmar, McLane and Schneider, he said.
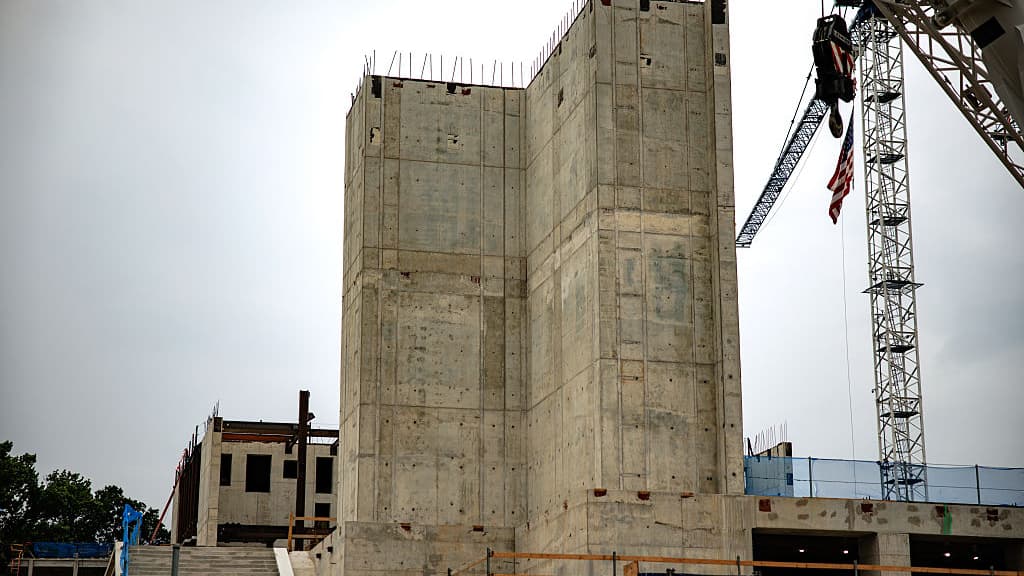
Wehle says that decades-long accumulation of authority has brought the Executive Branch close to treating the President as “above the law.”
“Trump’s authority is at its apex when it can be tied to the Commander-in-Chief power,” Wehle says.
Republicans control both the House and Senate, she says, and Trump could have attempted to get Congressional approval for both the ballroom and arch projects by rallying his own party’s support—but he didn’t.
Instead, the Administration has opted to add military justification to its efforts, she says, which “makes it more convenient for the court to reinterpret the Constitution around unaccountable, unlimited, concentrated power in one person.”
Can Trump’s triumphal arch also function as a military site?
Trump has not given much information regarding what military use the arch would have, but George Washington University law professor Sara Bronin, who is also an architect, tells TIME that she is not aware of any other structures that double as commemorative monuments and military infrastructure.
On September 17, KeyBanc lifted its price target on AppFolio, Inc. (NASDAQ:APPF) from $255 to $280 and maintained its Overweight rating on the stock after conducting customer checks and speaking with the company’s investor relations team to better understand the resident services opportunity.

KeyBanc believes resident services could become a meaningful driver of average revenue per user (ARPU) for the company, as residents could potentially spend more than $100 per month on additional offerings. While adoption remains in its early stages and certain states have restrictions, KeyBanc continues to see this as the most significant upside driver.
The research firm’s new $280 price target is based on 7.5 times 2027 enterprise value-to-sales and 27 times enterprise value-to-free cash flow.
AppFolio Raises 2026 Outlook, But Risks Remain
The company has been seeing strong growth. For the second quarter ended June 30, 2026, AppFolio, Inc. (NASDAQ:APPF) reported revenue of $281 million, up 19% year over year. It also crossed $1 billion in trailing 12-month revenue for the first time.
The company raised its full-year revenue guidance, supported by continued growth in premium-tier adoption and increasing use of its products and services. AppFolio, Inc. (NASDAQ:APPF) now expects full-year 2026 revenue between $1.117 billion and $1.127 billion, while its non-GAAP operating margin range as a percentage of revenue is expected to range from 26.5% to 28.0%.
Despite the stronger outlook, the company is facing some risks that could limit its growth. Higher infrastructure costs are one concern, as data center spending increases as the company seeks to support more AI usage. Non-GAAP cost of revenue, excluding depreciation and amortization, rose to 36% of revenue from 35% a year earlier.
Management also indicated that unit growth among existing customers could become more moderate, which could limit near-term growth.
AppFolio, Inc.’s (NASDAQ:APPF) valuation also leaves less room for disappointment. The stock currently trades at a forward P/E ratio of 31.86. This represents a premium when compared with 22.41 for the industry.
What the Numbers Say
Hedge fund interest in the stock weakened during the second quarter. According to Insider Monkey‘s database, 39 hedge funds held AppFolio, Inc. (NASDAQ:APPF) at the end of the second quarter, down from 43 in the first quarter.
As of August 31, short interest stood at 9.84% of the company’s float, indicating some level of bearish positioning in the stock.
RB Global, Inc. (NYSE:RBA) doubled its buyback authorization as profits expanded, putting cash generation at the center of the investment case. On September 15, 2026, the commercial-asset and vehicle marketplace announced Toronto Stock Exchange approval to raise the program’s aggregate dollar ceiling from US$500 million to US$1 billion.
The amendment, expected to take effect September 17, also raises the share limit from 10 million to 14,224,129. Purchases must stay within both ceilings. The program expires March 17, 2027, unless completed or terminated earlier.
RB Global, Inc. (NYSE:RBA) had already repurchased about 5.36 million shares by September 11, implying about $500 million in spending based on the disclosed average purchase price. The amendment therefore creates roughly $500 million of additional dollar capacity.

Bull Case
RB Global, Inc. (NYSE:RBA) reported second-quarter revenue growth of 11% to $1.3 billion, while GAAP net income increased 31% to $143.6 million. That earnings expansion strengthens the case for returning capital alongside continued investment in the business.
Retiring shares increases each remaining shareholder’s ownership interest. For RB Global, Inc. (NYSE:RBA), repurchases could create value if executed below intrinsic value while preserving sufficient funding for operations, acquisitions, and debt obligations.
The authorization also gives management flexibility over execution. RB Global, Inc. (NYSE:RBA) can pace purchases around available cash and investment opportunities, with no requirement to exhaust the program. Selective execution could make repurchases a useful complement to reinvestment and debt management.
Bear Case
RB Global, Inc. (NYSE:RBA) generated $365.8 million of operating cash flow in the first half, down from $483.3 million, a decline of approximately 24%. Operating assets and liabilities absorbed $292.4 million, compared with $117.8 million a year earlier, helping explain why stronger earnings did not translate into higher operating cash flow.
Competing uses were substantial. During the first half, RB Global, Inc. (NYSE:RBA) spent $183.9 million on property, plant and equipment and intangible additions, and paid $132.8 million in dividends. Subtracting those outlays from operating cash flow leaves $49.1 million before acquisitions and repurchases. Acquisitions, net of cash acquired, consumed another $331.1 million, while buybacks used $150 million.
RB Global, Inc. (NYSE:RBA) ended June with $524.9 million in cash and cash equivalents and approximately $2.9 billion in debt. Accelerating repurchases without stronger cash generation could reduce financial flexibility or increase reliance on borrowing.
New crypto presales often compete for attention with big promises and fast-moving social posts.
MemeToro is standing out in a different way. It has moved into Stage 7 at $0.00430, raised more than $139K, and published public code for an AI-guided fair-launch system on BNB Chain.
That combination gives buyers more than a price chart to consider. The project wants to use an AI agent to help creators build memecoin launches with fixed distribution and funding rules. $MT is planned as the token that connects users to this wider ecosystem.
The most bullish case is that MemeToro becomes a useful place to launch, discover, and trade meme assets. The key risk is that the product is still being built. For buyers looking at new crypto presales in 2026, progress and delivery matter more than slogans.
Discovering MemeToro’s stage 7 crypto presale opportunity
MemeToro is an emerging BNB Chain project that focuses on memecoin creation and trading tools. Its presale has passed $139K, and the active Stage 7 price is $0.00430 per $MT. The project displays a launch target of $0.05186, which creates a large difference between the current price and the target.
The presale is only one part of the story. MemeToro is also building an AI agent that is meant to help launch creators choose fixed token allocations and funding mechanics. The project’s public Solidity release outlines a fair-launch design that aims to remove insider tiers and make key rules visible.
This is what makes the Stage 7 progress notable. Buyers are not only purchasing exposure to a meme token. They are looking at a project that wants to create infrastructure for future BNB Chain memecoin launches.
The current opportunity remains speculative. A presale total does not prove future success. But early funding can give the project more room to complete its technical roadmap, attract users, and move toward a working launchpad.
How MemeToro’s AI agent utility could create demand
MemeToro’s planned AI agent is designed to simplify launch planning. It could help a creator set up a token distribution, funding plan, and launch settings without needing to understand every smart contract detail. The final rules would then be designed to move through the fair-launch contract structure.
This matters because memecoin launchpads are crowded. A platform needs a reason for users to return after the first launch. MemeToro’s planned ecosystem gives $MT several possible roles, including access, launch funding, platform transactions, staking, and rewards.
The roadmap also includes:
- memecoin trading tools
- prediction markets
- a crypto news portal
- creator and community activity
- AI-supported discovery features
These are planned features, not completed products. Still, they show that MemeToro is aiming for utility beyond a simple presale. If users need $MT to access or use key functions, demand could grow with platform activity. That is the central upside case for long-term holders.
Public fair-launch code adds a research layer
MemeToro has released 1,373 lines of Solidity across 17 files under an MIT license. The release includes a fair-launch escrow contract, interfaces, tests, and documentation. In plain language, it is meant to show how the platform could lock important launch rules before buyers take part.
The stated design aims to prevent a creator from adding a private insider allocation later. It also sets out a model where funds can move only through refund or planned liquidity routes, rather than through a developer-controlled treasury path.
That public approach is important for new crypto presales. Buyers often have to decide whether they trust a project without seeing its underlying systems. MemeToro gives them code to inspect.
The release is not a final security guarantee. The project still needs testnet deployment, liquidity execution, and independent security review. Yet public development gives MemeToro a stronger evidence base than projects that only publish a roadmap. In a high-risk market, visible work can matter.
Tokenomics: $MT distribution & staking metrics
The distribution framework splits the 1.2 billion total supply into clear structural pools. The public sale accounts for 71% of the tokens. The remaining supply is divided into centralized exchange reserves at 10%, marketing partners at 7.56%, platform trading liquidity at 5%, network rewards at 4.44%, and the core team allocation at 2%.
Key Protocol Rules:
- Presale Release: 100% unlocked and claimable on the official launch date.
- Partner Lockups: Subject to a 24-month vesting period to prevent dilution.
- Staking Rewards: Programmatic distribution offering yields up to 35% APR.
- Security Status: Fully audited smart contract architecture.
FAQs
What is the current $MT price?
The active Stage 7 price is $0.00430 per $MT, based on the latest supplied presale update.
Is MemeToro’s AI agent live?
The AI launchpad is under development. Buyers should treat it as a roadmap feature until the project shows a live product.
How can buyers join the presale?
Use the official MemeToro (memetoro.com) portal, connect a compatible wallet, choose a supported payment option, and confirm the purchase. Never share a seed phrase.
More Information on MemeToro ($MT) Presale Here:
Website: https://memetoro.com/
Telegram: https://t.me/memetoro_mt
YouTube: https://www.youtube.com/watch?v=gY0jgWy_DtA
To identify monster stocks before they take off, investors should first focus on underlying business momentum. Stocks can be volatile in the near term, but they ultimately track the business’s long-term growth. Investing in businesses with attractive growth prospects when they trade at attractive valuations relative to earnings can help you succeed in finding tomorrow’s winners.
Here’s why DoorDash (NASDAQ: DASH) and Viking Holdings (NYSE: VIK) are great candidates right now.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »

1. DoorDash
DoorDash is a fast-growing logistics platform that makes it easy for customers to get orders from local merchants delivered to their door. The company earns money through merchant commissions, delivery fees, subscriptions, and advertising, and it’s expanding rapidly. Revenue has climbed from $4.9 billion in 2021 to $13.7 billion in 2025, indicating its long-term potential.
It is emerging as the leader in grocery delivery and has also recently gained momentum in restaurant and retail orders. The stock’s performance reflects this trajectory, rising 141% over the past three years. Revenue grew 36% year over year in the second quarter, driven by strength in deliveries and continued growth in DashPass subscribers.
DoorDash benefits from a reinforcing growth flywheel. Revenue growth funds product improvements, which drive higher order frequency and more DashPass sign-ups. Once customers join DashPass, DoorDash usage can become habitual. In the second quarter, DashPass customers generated 75% of U.S. grocery and retail orders.
There’s room to expand internationally, although DoorDash faces stiffer competition abroad. It is currently No. 2 in the U.K., Italy, Germany, and Canada, but management indicated on the second-quarter earnings call that it’s growing faster than the competition in those markets.
Delivery is a low-margin business, reflecting fierce competition from Uber Eats and Instacart. Even so, DoorDash’s operating profit has improved from -$579 million in 2023 to $723 million in 2025. This shows it can price its service to earn a profit, indicating capital efficiency and a solid competitive position.
The stock trades at a forward price-to-earnings (P/E) multiple of 34. If DoorDash meets analysts’ expectations for 44% annualized earnings growth, that valuation relative to the growth rate could set up market-beating returns over the next five years.
MicroStrategy has not bought Bitcoin (BTC) in two weeks, its most recent regulatory filing shows. In his latest post, however, Executive Chairman Michael Saylor has investors betting the company may have broke that pause last week.
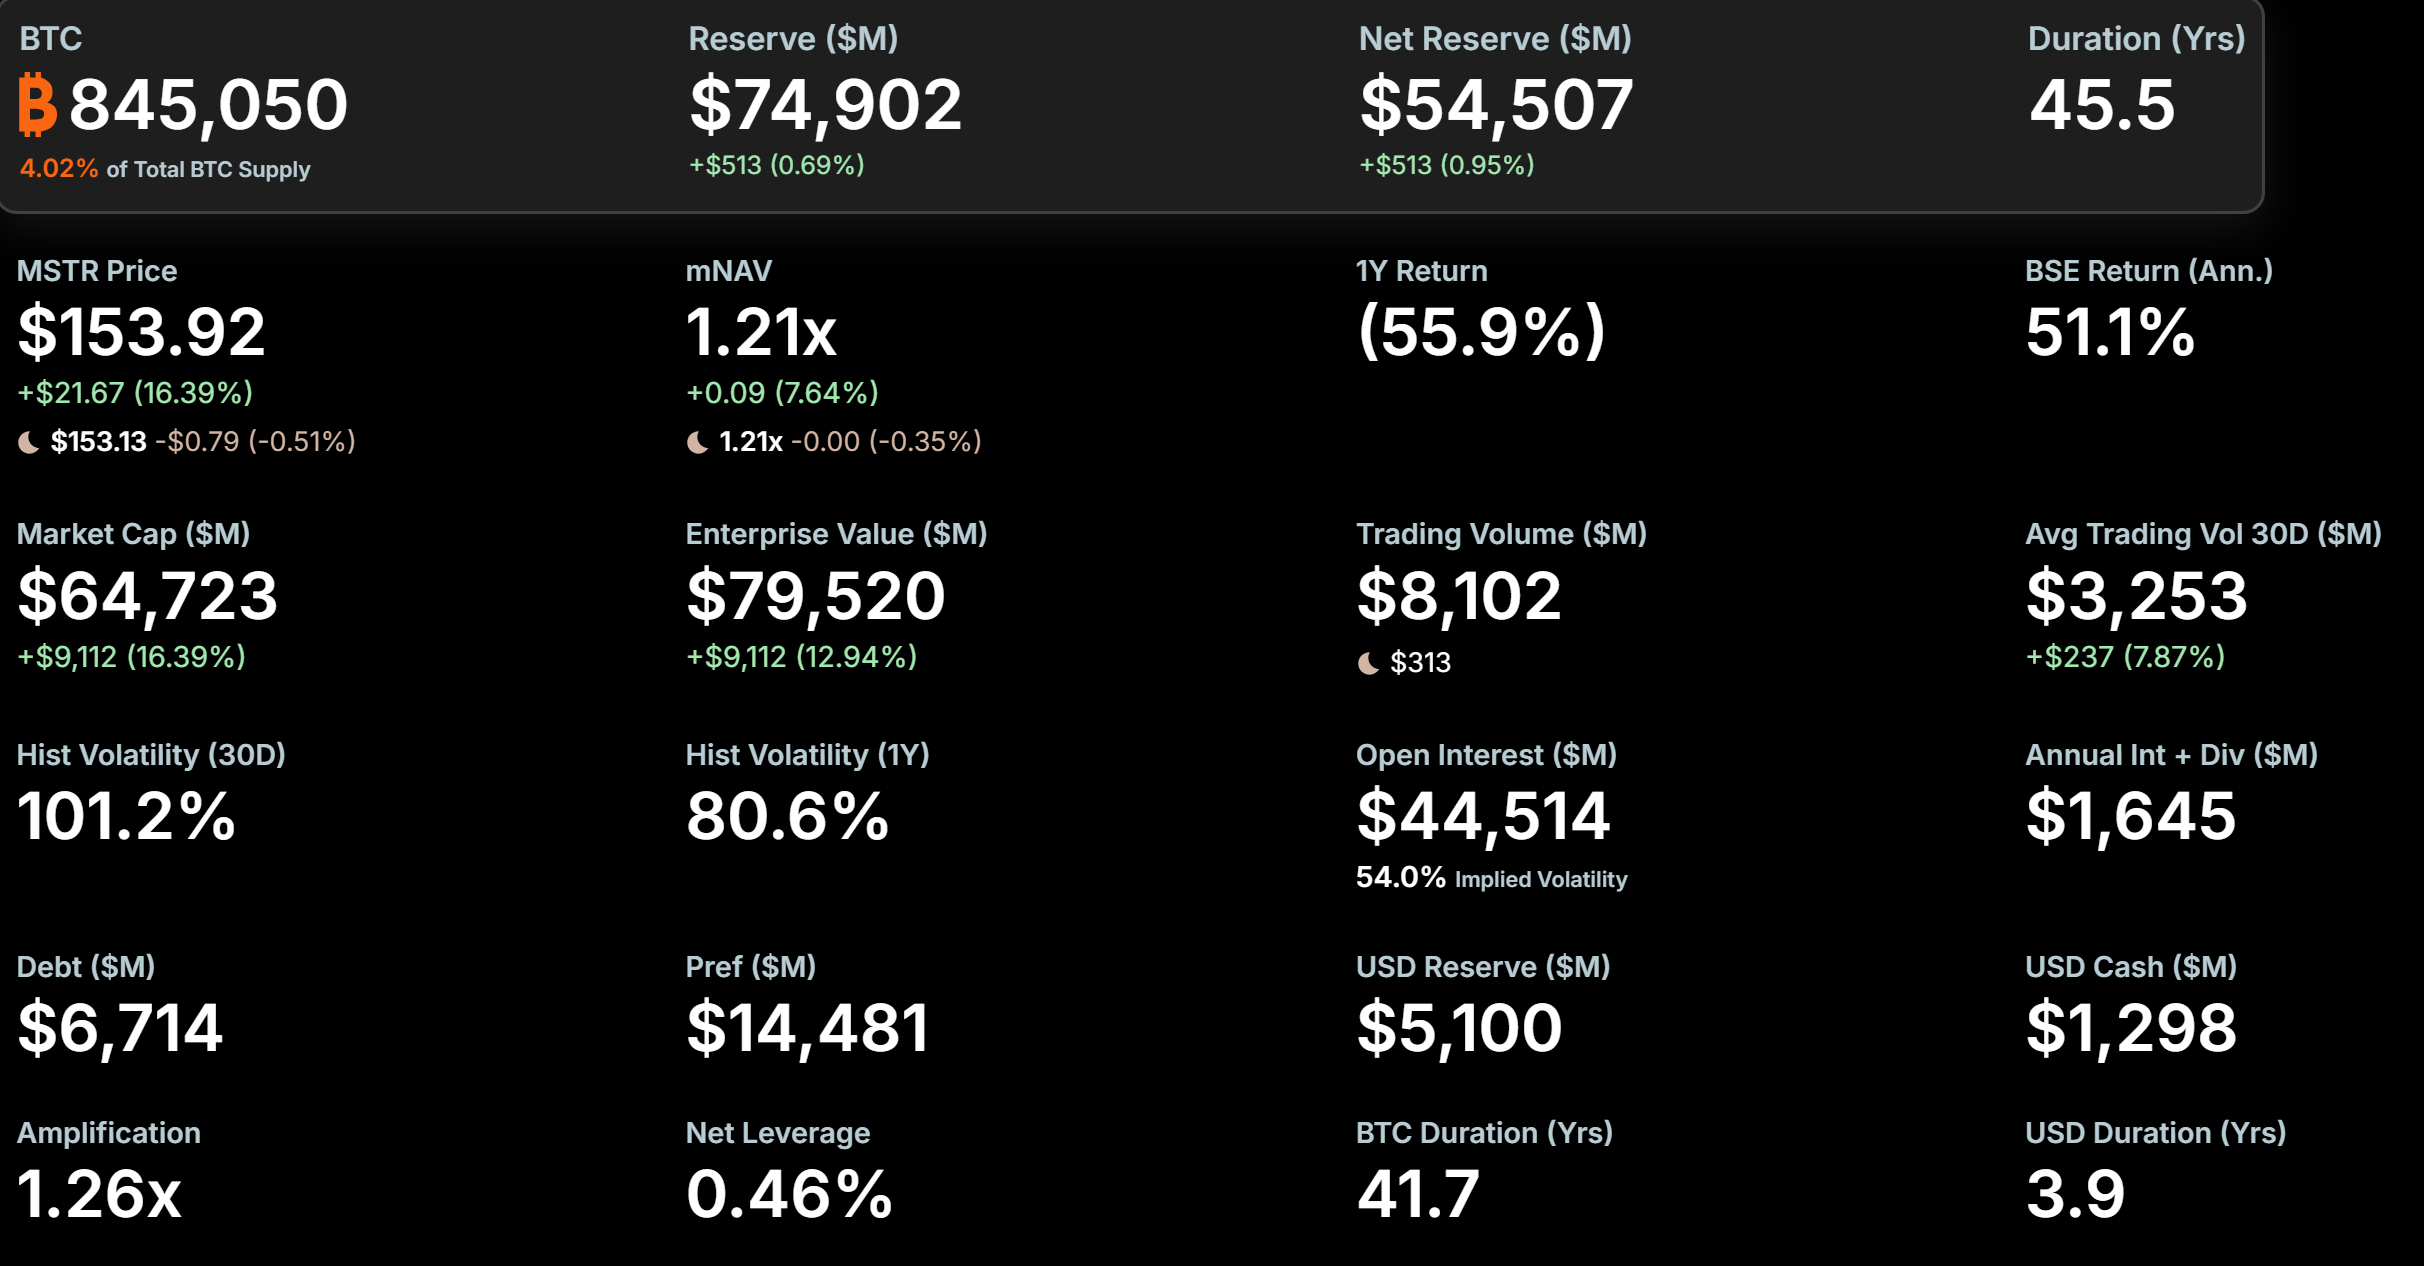
Saylor wrote “A little more orange” above a chart of the firm’s holdings. He has used that format before purchase disclosures. MicroStrategy reports any Bitcoin buying every Monday.
Strategy’s Bitcoin Holdings Have Not Moved Since August
The company told the US Securities and Exchange Commission (SEC) on September 14 that it neither bought nor sold Bitcoin between September 8 and September 13. Its filing a week earlier reported the same for the previous seven days.
Strategy held roughly 845,050 BTC as of September 13. It paid $63.73 billion for that stack, an average of $75,412 per coin.

Its last purchase was 4,603 BTC for $369.7 million, disclosed on August 31. That deal ended a 10-week pause. BeInCrypto called the restart the day before it was announced, after a similar Saylor teaser.
Cash is the constraint. Strategy spent $139.3 million buying back preferred shares in the week to September 13 rather than buying Bitcoin. That left $1.30 billion in the account it uses for purchases. The firm has also sold Bitcoin to support that share price this year.
Calacanis Called Bitcoin Boring and Saylor Answered Him
Angel investor Jason Calacanis started the argument on Friday. He posted a one-year chart showing Bitcoin down about 31% and wrote that the dead cat continues to bounce.
A dead cat bounce is a short price recovery inside a bigger decline, named for the idea that even a dead cat bounces if it falls far enough.
Calacanis said Bitcoin works poorly for payments and smart contracts and no longer excites the public. He compared it to compact discs in the streaming era.
“Jason, you’ve watched Bitcoin grow since 2011. It’s now a $1.6 trillion success and the world’s most valuable digital asset. Digital Capital is the killer app. Preserving wealth across generations is a bigger ambition than entertaining a dinner party. The orange tie stays,” Saylor challenged.
ARK Invest founder Cathie Wood equally rejected the dead cat label and pointed to her firm’s research on Bitcoin and artificial intelligence.
By the strict market definition, Jason’s label does not fit, because a dead cat bounce is only confirmed when price rolls over and breaks the old low. Bitcoin price at $81,292 as of this writing is still above the roughly $75,000 dip it rebounded from.

What he actually argued is a cultural verdict rather than a chart call, that Bitcoin stopped winning new use cases and settled into a boring store of value. That part is opinion, not something the price data can prove or disprove.
The post Michael Saylor Hints at More MicroStrategy Bitcoin Buys After “Dead Cat Bounce” Debate appeared first on BeInCrypto.
As the artificial intelligence boom shifts into a more mature phase, should you choose to invest in the processing power of Advanced Micro Devices (NASDAQ:AMD) or the essential memory infrastructure of SK Hynix (NASDAQ:SKHY)?
AMD specializes in the brains of computing, designing processors that power cloud servers and gaming consoles. SK Hynix focuses on the storage components, such as High Bandwidth Memory (HBM), which are indispensable for training complex AI models. Together, they represent two critical, yet distinct, pillars of the global hardware ecosystem.
The case for Advanced Micro Devices
Advanced Micro Devices designs and sells high-performance computing components for data centers and gaming markets. The company provides specialized chips for major clients like Microsoft (NASDAQ:MSFT) and Sony. In late 2025, the company secured a strategic partnership with OpenAI to supply powerful graphics processors for AI infrastructure.
In its 2025 fiscal year (FY), revenue reached $34.6 billion, representing a significant 34.3% increase over the previous year. This growth supported a net income of $4.3 billion for the period. The net margin, which measures the percentage of revenue remaining after all expenses, improved to 12.5%.
As of its December 2025 balance sheet, the debt-to-equity ratio was 0.1x. This ratio shows how much debt the company has relative to what shareholders own. The current ratio stands at 2.9x, indicating that the business has nearly three times more short-term assets than it does liabilities due within a year. Free cash flow, or the cash left after paying for capital assets, was $6.7 billion. Note that stock-based compensation (SBC) represented 21.2% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
The case for SK Hynix
SK Hynix is a global leader among semiconductor stocks. It produces high-speed memory chips and storage solutions essential for servers, mobile devices, and artificial intelligence hardware. While the company does not disclose individual major customers in its filings, its memory products are vital for most large-scale data centers. Its strategy focuses on advancing High Bandwidth Memory technology to meet the rising storage demands of complex software.
In FY 2025, revenue reached 97.2 trillion Korean won, a massive 46.8% jump from the previous fiscal year. This surge led to a net income of 42.9 trillion won. The net margin for the period was 44.2%, reflecting a high level of profitability relative to total sales.
Crypto World
I Own Constellation for the Nuclear Fleet, Not the AI Headlines. Here’s Why That Matters Now.
Artificial intelligence and its growing energy demands dominate the headlines, especially for independent power companies like Constellation Energy (NASDAQ: CEG). Deals with hyperscalers like Meta Platforms and Microsoft have put Constellation on the map as power demands soar, but that’s not the only reason to own Constellation.
While AI attracts attention, Constellation’s real advantage is its massive nuclear fleet. With the largest nuclear fleet in the U.S. and a track record of efficient operations, Constellation boasts a strong competitive advantage and durable moat. As nuclear power returns to favor, that moat could become even more valuable. Here’s why.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »

Constellation boasts the U.S.’s largest nuclear energy fleet
Nuclear power is returning to favor, and for good reason. Growing power demand, combined with a desire to cut carbon emissions, makes nuclear a highly appealing choice. On top of that, nuclear provides reliable 24/7 baseload energy, making it a no-brainer for businesses and governments looking to secure carbon-free power.
Constellation boasts a massive fleet of nuclear power assets. It has 22 gigawatts (GW) of nuclear capacity, making it the largest nuclear energy operator in the U.S. by a long shot. The next-closest nuclear fleet operators include Duke Energy, with roughly 11 GW of capacity, and Vistra, with 6.6 GW.
Constellation’s highly efficient nuclear fleet also comes with downside protection
In addition, Constellation’s nuclear fleet posted a 93% capacity factor in the second quarter and 94.7% in 2025. This was the highest capacity factor in the industry, which the company attributes to its fast refueling time of roughly 21.5 days per outage compared to 35 to 38 days on average. Ultimately, this high capacity factor means Constellation can provide customers with truly reliable energy.
Another benefit of this nuclear fleet is that it is eligible for the federal Nuclear Production Tax Credit (PTC) through 2032. Created as part of the Inflation Reduction Act, this credit provides transferable, inflation-protected credits that serve as an explicit price floor, protecting cash flows if power prices drop.
Constellation’s nuclear fleet has also secured the vast majority of power generation through 2050 and beyond. Commercial nuclear units are licensed to operate for up to 80 years. Key nuclear plants across Constellation have secured these licenses or have filed applications that keep their physical operating authorization active into the late 2040s and 2050s.
T-Mobile and Verizon have been gaining momentum in attracting new internet customers; however, competition has just intensified with a new rival in the broadband market.
In recent months, both companies have benefited from a growing trend of consumers switching from traditional internet services offered by cable operators to lower-priced fixed wireless and fiber internet offerings from wireless carriers.
Amid this trend, T-Mobile reportedly added roughly 520,000 broadband customers in the second quarter of 2026, according to data from research and consulting firm Recon Analytics. Verizon gained about 348,000 internet customers during the quarter, its latest earnings report revealed.
In a May report from RCR Wireless News, Jeff Moore, telecom analyst and principal of Wave7 Research, said the “U.S. broadband duopoly of cable and telcos is fading” as “increased competition from carriers and alternative providers is giving consumers more choices, wider availability, easier setup, and lower prices.”
Cricket Wireless introduces 5G home internet service
As T-Mobile and Verizon benefit from shifting consumer behavior, Cricket Wireless, which is owned by AT&T, has entered the broadband market by launching 5G home internet service (a fixed wireless internet service).
Cricket 5G Home Internet officially launched on Sept. 16, according to a new press release. The carrier states that the offering “simplifies connectivity with predictable pricing, no annual contracts, and plan taxes included” in the monthly price. It also runs on AT&T’s network.
The plan is $65 per month, and if new customers bundle it with Cricket Wireless, it is $75 per month. However, existing Cricket Wireless customers can add Cricket 5G Home Internet for $45 per month (with the $5 autopay discount activated).
Related: T-Mobile adds monthly fee to a new iPhone feature for customers
The plan offers “unlimited data for streaming, gaming, browsing and everyday household connectivity.” It has a typical download speed of 90-300 Mbps, an upload speed of 8-30 Mbps, and a latency of 30-65 milliseconds.
Also, Cricket Wireless states that no installation appointments are needed, as customers can set up the service themselves in minutes using the myCricket Internet App.
“Customers are looking for fast, reliable internet that’s simple to buy, easy to understand, and backed by a brand they trust,” said Angela Rittgers, president of Cricket Wireless, in the press release. “With Cricket 5G Home Internet, we’re delivering the internet you need at the value you deserve while removing the complexity; it’s just the smarter way to stay connected.”


Hyundai Ioniq 6 N Review: Electric Performance Saloon Tested

Vibe coding, parasocial and Rickroll officially added to dictionary

How Caleb Williams’ Injury Could Change the Bears’ Season




-
 Fashion2 days ago
Weekend Open Thread: Talbots – Corporette.com
-
 Crypto World2 days ago
Circle launches Arc Studio AI agent for building onchain apps
-

 Crypto World6 days ago
Revolut Attackers Warn of Ongoing Daily Customer Data Leaks
-
 NewsBeat2 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World6 days ago
Kraken Lets xStocks Holders Earn Yield Through DeFi
-
 Crypto World5 days ago
Robinhood engineers charged over $50K crypto scheme
-

 Crypto World5 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-

 Crypto World4 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-
 Crypto World2 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Crypto World6 days ago
Elon Musk Drops a Bombshell: Grok 5 Could Be the AGI Breakthrough
-
 NewsBeat6 days ago
‘Sick conspiracy’: Trump says only guardrails AI needs is ‘a strong and smart (High IQ!) president’ in all-caps rant
-

 Crypto World6 days ago
NVIDIA Analysis: Attempted Rising Wedge Breakout Amid Pressure on the AI Sector
-
Business6 days ago
SK Hynix ADRs Fall More Than 6% as Memory Rally Breaks on Fears of Slower AI Spending
-

 Crypto World7 days ago
3 Token Unlocks to Watch in the Third Week of September 2026
-
 Tech5 days ago
Webb’s IC 348 Mosaic Includes Two-Jupiter Dwarfs, Twin Jets, and a Nursery Still Making Worlds
-
Crypto World6 days ago
Can Circle’s Arc Repeat Robinhood Chain’s Meme Coin Boom?
-

 Crypto World6 days ago
DOJ Seeks to Seize $61M in Iran Oil Funds From Binance Accounts It Vouched For
-
 Entertainment5 days ago
Big Brother Update: Melody Explodes at Drew as Illness Sweeps BB28 House
-
 Crypto World3 days ago
Silver prices recover quickly, hitting weekly high today
-
 NewsBeat2 days ago
US was ‘on brink of war’ with China over false AI report of nukes moving in Middle East
You must be logged in to post a comment Login