
Crypto World
Michael Saylor Hints at More MicroStrategy Bitcoin Buys After “Dead Cat Bounce” Debate

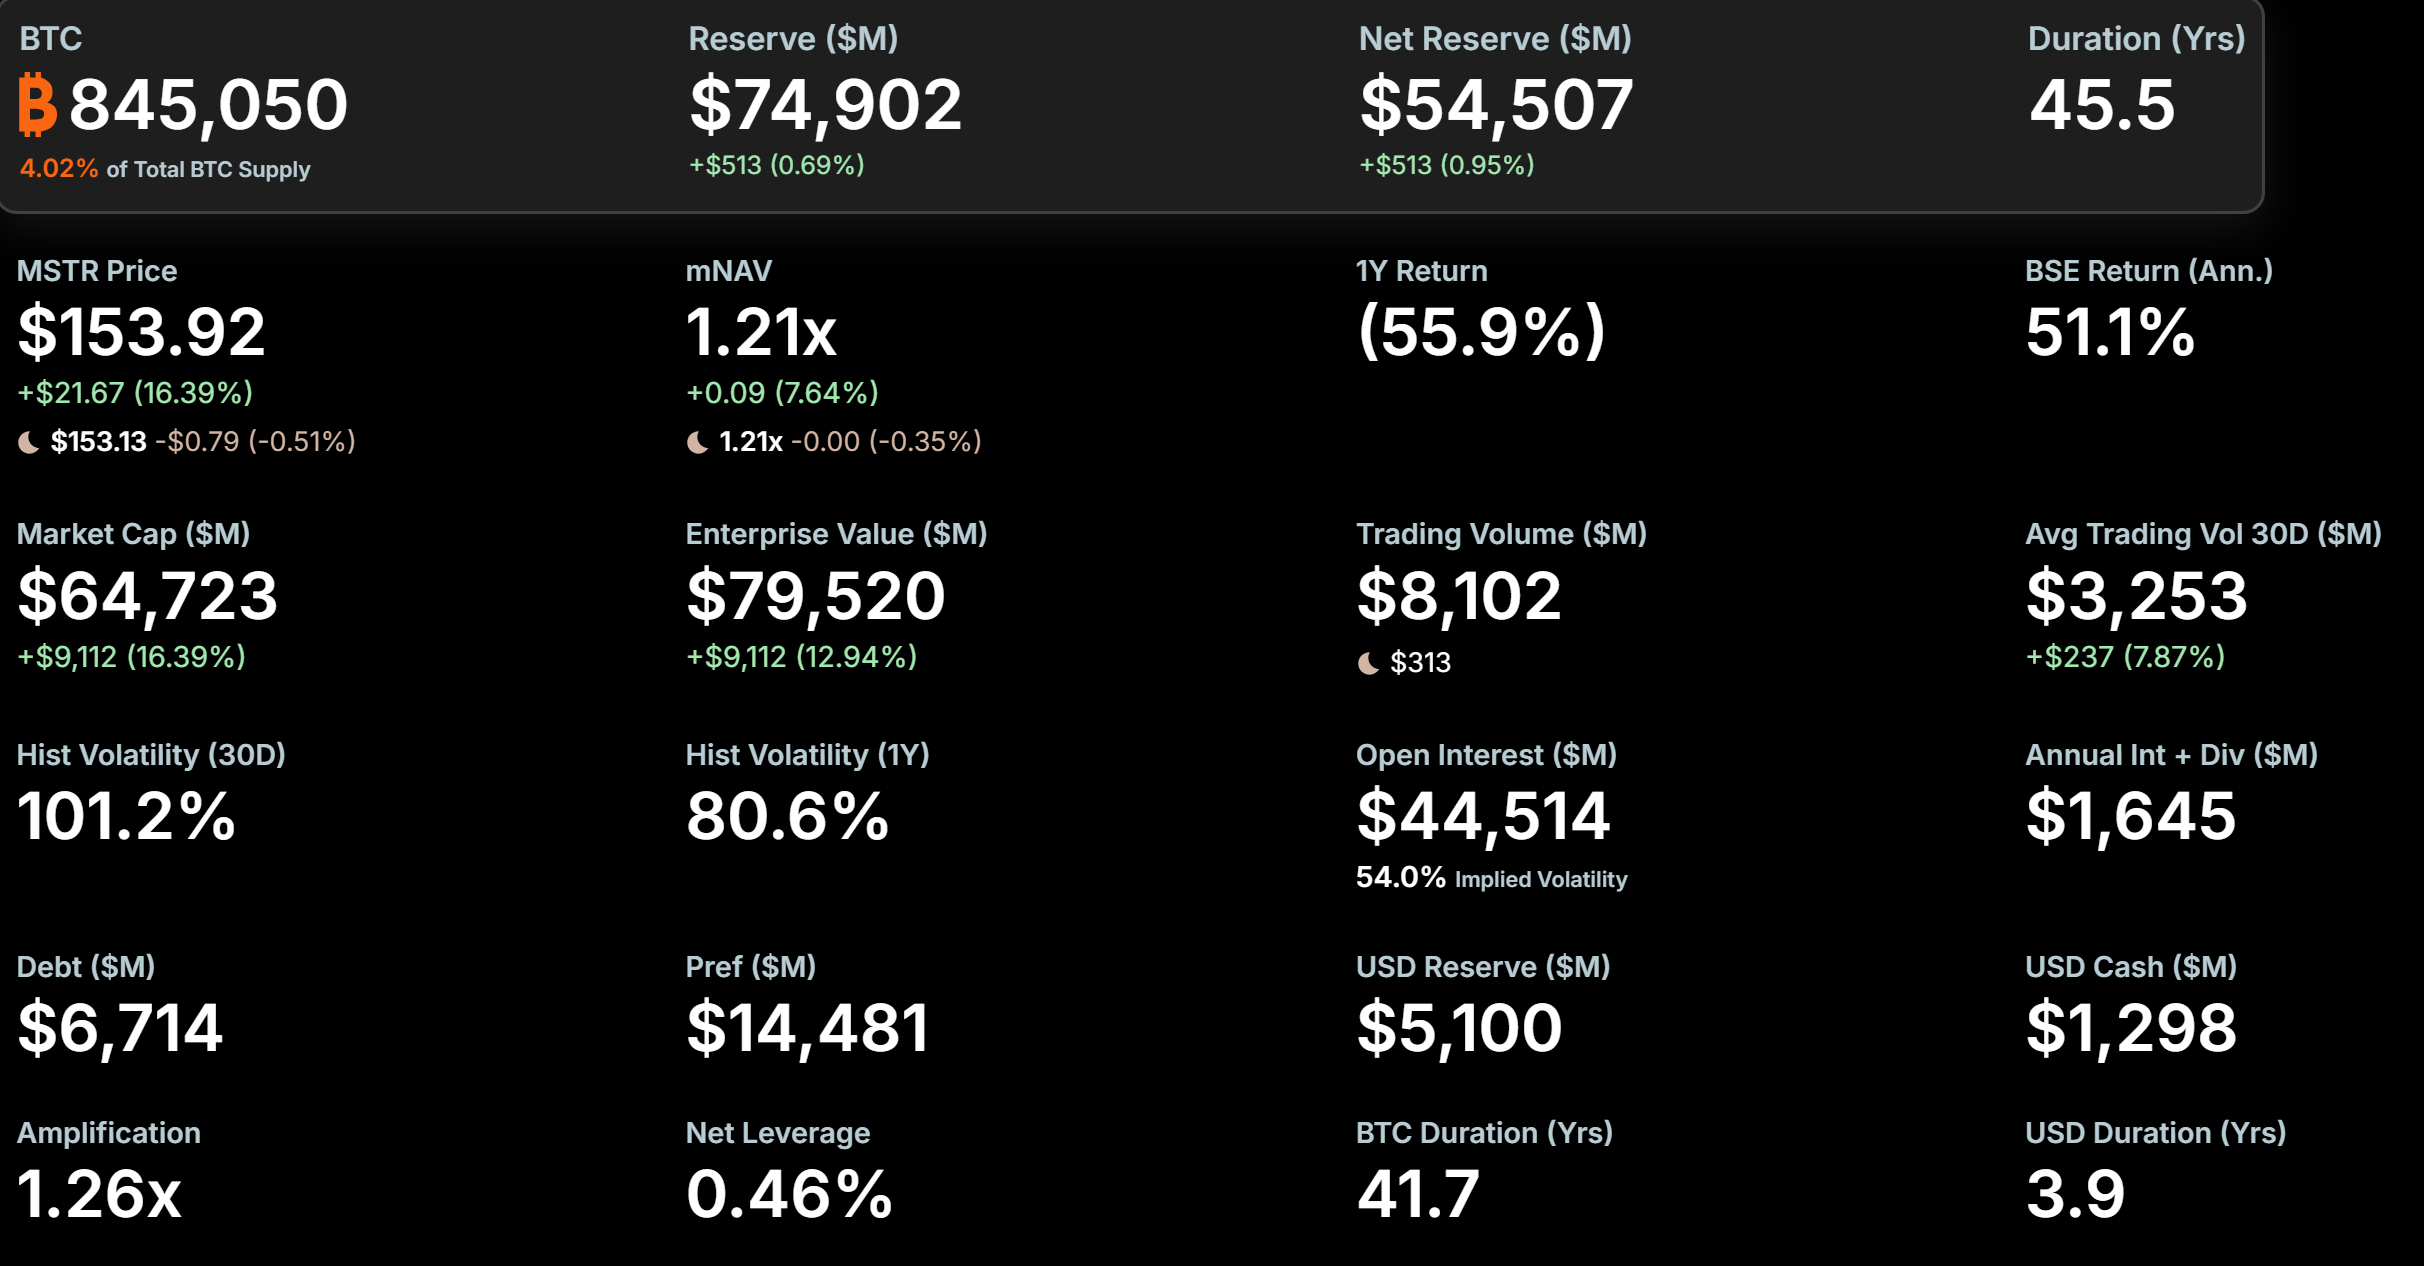
MicroStrategy has not bought Bitcoin (BTC) in two weeks, its most recent regulatory filing shows. In his latest post, however, Executive Chairman Michael Saylor has investors betting the company may have broke that pause last week.
Saylor wrote “A little more orange” above a chart of the firm’s holdings. He has used that format before purchase disclosures. MicroStrategy reports any Bitcoin buying every Monday.
Strategy’s Bitcoin Holdings Have Not Moved Since August
The company told the US Securities and Exchange Commission (SEC) on September 14 that it neither bought nor sold Bitcoin between September 8 and September 13. Its filing a week earlier reported the same for the previous seven days.
Strategy held roughly 845,050 BTC as of September 13. It paid $63.73 billion for that stack, an average of $75,412 per coin.

Its last purchase was 4,603 BTC for $369.7 million, disclosed on August 31. That deal ended a 10-week pause. BeInCrypto called the restart the day before it was announced, after a similar Saylor teaser.
Cash is the constraint. Strategy spent $139.3 million buying back preferred shares in the week to September 13 rather than buying Bitcoin. That left $1.30 billion in the account it uses for purchases. The firm has also sold Bitcoin to support that share price this year.
Calacanis Called Bitcoin Boring and Saylor Answered Him
Angel investor Jason Calacanis started the argument on Friday. He posted a one-year chart showing Bitcoin down about 31% and wrote that the dead cat continues to bounce.
A dead cat bounce is a short price recovery inside a bigger decline, named for the idea that even a dead cat bounces if it falls far enough.
Calacanis said Bitcoin works poorly for payments and smart contracts and no longer excites the public. He compared it to compact discs in the streaming era.
“Jason, you’ve watched Bitcoin grow since 2011. It’s now a $1.6 trillion success and the world’s most valuable digital asset. Digital Capital is the killer app. Preserving wealth across generations is a bigger ambition than entertaining a dinner party. The orange tie stays,” Saylor challenged.
ARK Invest founder Cathie Wood equally rejected the dead cat label and pointed to her firm’s research on Bitcoin and artificial intelligence.
By the strict market definition, Jason’s label does not fit, because a dead cat bounce is only confirmed when price rolls over and breaks the old low. Bitcoin price at $81,292 as of this writing is still above the roughly $75,000 dip it rebounded from.

What he actually argued is a cultural verdict rather than a chart call, that Bitcoin stopped winning new use cases and settled into a boring store of value. That part is opinion, not something the price data can prove or disprove.
The post Michael Saylor Hints at More MicroStrategy Bitcoin Buys After “Dead Cat Bounce” Debate appeared first on BeInCrypto.

As the artificial intelligence boom shifts into a more mature phase, should you choose to invest in the processing power of Advanced Micro Devices (NASDAQ:AMD) or the essential memory infrastructure of SK Hynix (NASDAQ:SKHY)?
AMD specializes in the brains of computing, designing processors that power cloud servers and gaming consoles. SK Hynix focuses on the storage components, such as High Bandwidth Memory (HBM), which are indispensable for training complex AI models. Together, they represent two critical, yet distinct, pillars of the global hardware ecosystem.
The case for Advanced Micro Devices
Advanced Micro Devices designs and sells high-performance computing components for data centers and gaming markets. The company provides specialized chips for major clients like Microsoft (NASDAQ:MSFT) and Sony. In late 2025, the company secured a strategic partnership with OpenAI to supply powerful graphics processors for AI infrastructure.
In its 2025 fiscal year (FY), revenue reached $34.6 billion, representing a significant 34.3% increase over the previous year. This growth supported a net income of $4.3 billion for the period. The net margin, which measures the percentage of revenue remaining after all expenses, improved to 12.5%.
As of its December 2025 balance sheet, the debt-to-equity ratio was 0.1x. This ratio shows how much debt the company has relative to what shareholders own. The current ratio stands at 2.9x, indicating that the business has nearly three times more short-term assets than it does liabilities due within a year. Free cash flow, or the cash left after paying for capital assets, was $6.7 billion. Note that stock-based compensation (SBC) represented 21.2% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
The case for SK Hynix
SK Hynix is a global leader among semiconductor stocks. It produces high-speed memory chips and storage solutions essential for servers, mobile devices, and artificial intelligence hardware. While the company does not disclose individual major customers in its filings, its memory products are vital for most large-scale data centers. Its strategy focuses on advancing High Bandwidth Memory technology to meet the rising storage demands of complex software.
In FY 2025, revenue reached 97.2 trillion Korean won, a massive 46.8% jump from the previous fiscal year. This surge led to a net income of 42.9 trillion won. The net margin for the period was 44.2%, reflecting a high level of profitability relative to total sales.
Crypto World
I Own Constellation for the Nuclear Fleet, Not the AI Headlines. Here’s Why That Matters Now.
Artificial intelligence and its growing energy demands dominate the headlines, especially for independent power companies like Constellation Energy (NASDAQ: CEG). Deals with hyperscalers like Meta Platforms and Microsoft have put Constellation on the map as power demands soar, but that’s not the only reason to own Constellation.
While AI attracts attention, Constellation’s real advantage is its massive nuclear fleet. With the largest nuclear fleet in the U.S. and a track record of efficient operations, Constellation boasts a strong competitive advantage and durable moat. As nuclear power returns to favor, that moat could become even more valuable. Here’s why.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »

Constellation boasts the U.S.’s largest nuclear energy fleet
Nuclear power is returning to favor, and for good reason. Growing power demand, combined with a desire to cut carbon emissions, makes nuclear a highly appealing choice. On top of that, nuclear provides reliable 24/7 baseload energy, making it a no-brainer for businesses and governments looking to secure carbon-free power.
Constellation boasts a massive fleet of nuclear power assets. It has 22 gigawatts (GW) of nuclear capacity, making it the largest nuclear energy operator in the U.S. by a long shot. The next-closest nuclear fleet operators include Duke Energy, with roughly 11 GW of capacity, and Vistra, with 6.6 GW.
Constellation’s highly efficient nuclear fleet also comes with downside protection
In addition, Constellation’s nuclear fleet posted a 93% capacity factor in the second quarter and 94.7% in 2025. This was the highest capacity factor in the industry, which the company attributes to its fast refueling time of roughly 21.5 days per outage compared to 35 to 38 days on average. Ultimately, this high capacity factor means Constellation can provide customers with truly reliable energy.
Another benefit of this nuclear fleet is that it is eligible for the federal Nuclear Production Tax Credit (PTC) through 2032. Created as part of the Inflation Reduction Act, this credit provides transferable, inflation-protected credits that serve as an explicit price floor, protecting cash flows if power prices drop.
Constellation’s nuclear fleet has also secured the vast majority of power generation through 2050 and beyond. Commercial nuclear units are licensed to operate for up to 80 years. Key nuclear plants across Constellation have secured these licenses or have filed applications that keep their physical operating authorization active into the late 2040s and 2050s.
T-Mobile and Verizon have been gaining momentum in attracting new internet customers; however, competition has just intensified with a new rival in the broadband market.
In recent months, both companies have benefited from a growing trend of consumers switching from traditional internet services offered by cable operators to lower-priced fixed wireless and fiber internet offerings from wireless carriers.
Amid this trend, T-Mobile reportedly added roughly 520,000 broadband customers in the second quarter of 2026, according to data from research and consulting firm Recon Analytics. Verizon gained about 348,000 internet customers during the quarter, its latest earnings report revealed.
In a May report from RCR Wireless News, Jeff Moore, telecom analyst and principal of Wave7 Research, said the “U.S. broadband duopoly of cable and telcos is fading” as “increased competition from carriers and alternative providers is giving consumers more choices, wider availability, easier setup, and lower prices.”
Cricket Wireless introduces 5G home internet service
As T-Mobile and Verizon benefit from shifting consumer behavior, Cricket Wireless, which is owned by AT&T, has entered the broadband market by launching 5G home internet service (a fixed wireless internet service).
Cricket 5G Home Internet officially launched on Sept. 16, according to a new press release. The carrier states that the offering “simplifies connectivity with predictable pricing, no annual contracts, and plan taxes included” in the monthly price. It also runs on AT&T’s network.
The plan is $65 per month, and if new customers bundle it with Cricket Wireless, it is $75 per month. However, existing Cricket Wireless customers can add Cricket 5G Home Internet for $45 per month (with the $5 autopay discount activated).
Related: T-Mobile adds monthly fee to a new iPhone feature for customers
The plan offers “unlimited data for streaming, gaming, browsing and everyday household connectivity.” It has a typical download speed of 90-300 Mbps, an upload speed of 8-30 Mbps, and a latency of 30-65 milliseconds.
Also, Cricket Wireless states that no installation appointments are needed, as customers can set up the service themselves in minutes using the myCricket Internet App.
“Customers are looking for fast, reliable internet that’s simple to buy, easy to understand, and backed by a brand they trust,” said Angela Rittgers, president of Cricket Wireless, in the press release. “With Cricket 5G Home Internet, we’re delivering the internet you need at the value you deserve while removing the complexity; it’s just the smarter way to stay connected.”

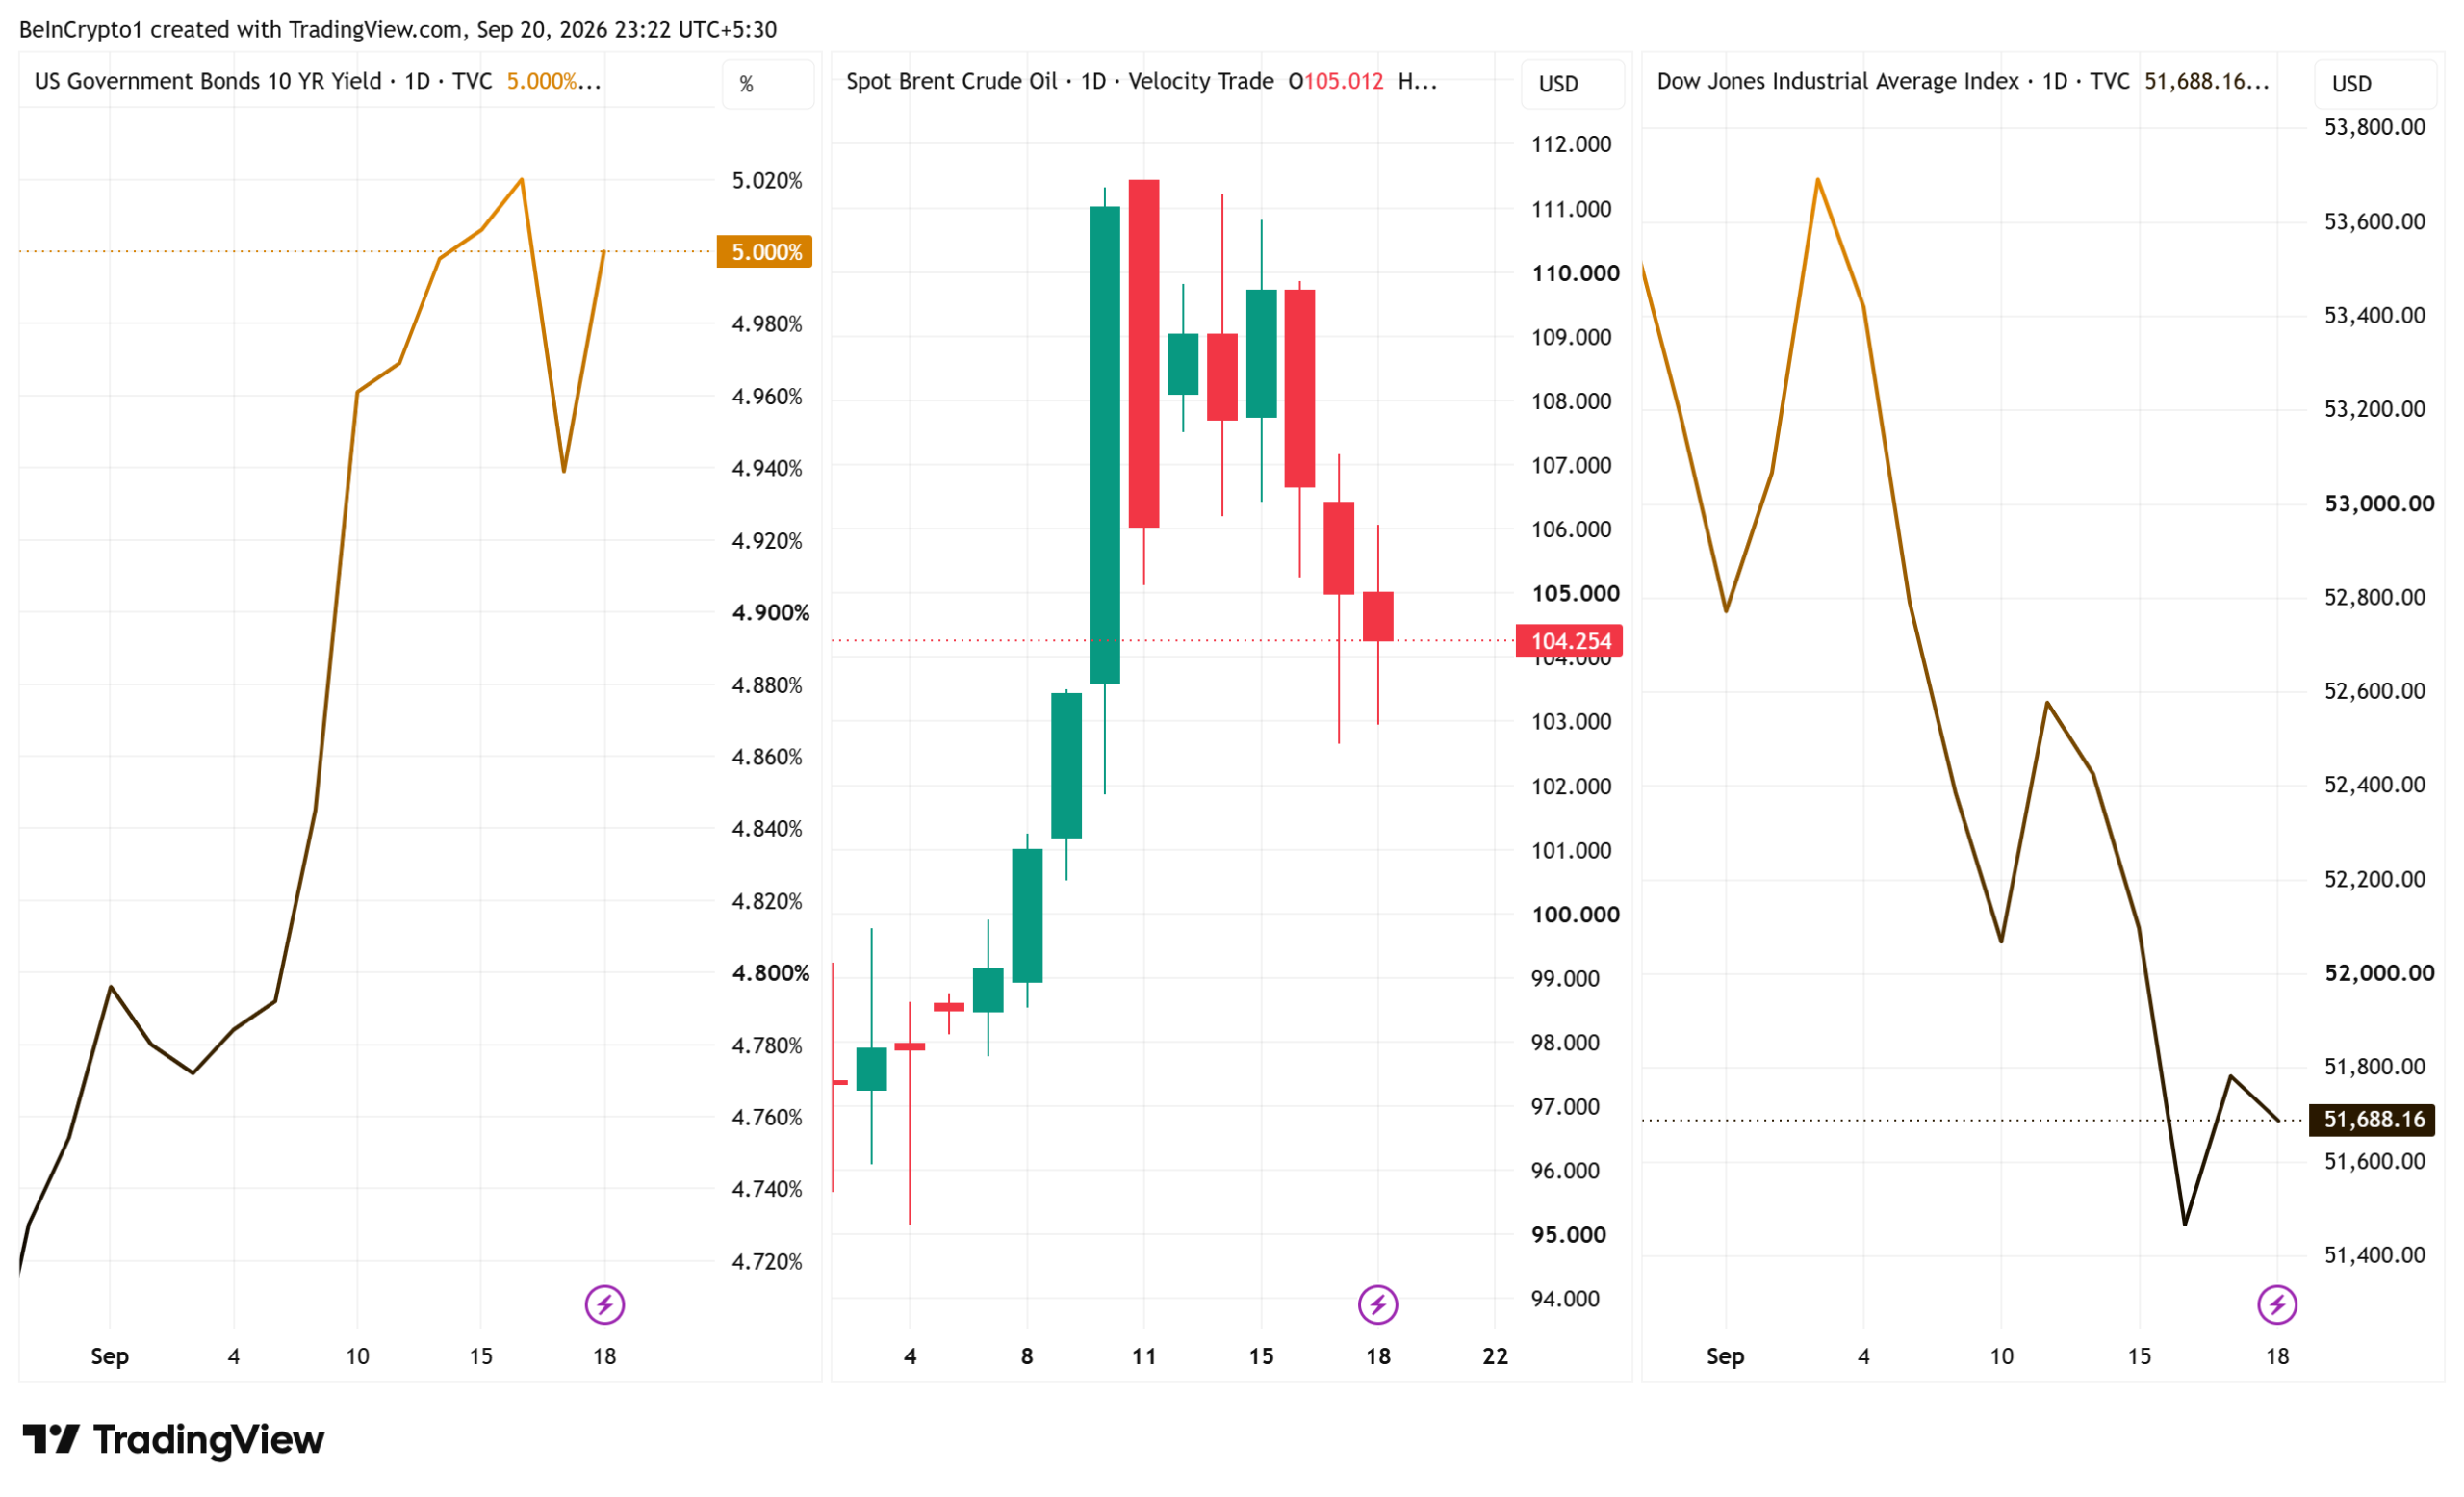
US stocks reopen Monday with the 10-year Treasury yield at 5% and the Dow down more than 1.5% last week. A missile strike on Riyadh adds oil risk on top.
Four events shape the days ahead. Yemen’s Houthi rebels struck the Saudi capital on Saturday. Fed officials speak and growth data lands Wednesday. President Donald Trump hosts Chinese President Xi Jinping on Thursday.

Why 5% on the 10-Year Sets the Price of Every Share
The bond market is where this week starts. A US government bond now pays 5% a year and carries almost no risk. Every company listed on Wall Street has to beat that.
Yardeni Research founder, Ed Yardeni, has already cut his year-end S&P 500 target to 7,900 from 8,400. He had been one of the most bullish forecasters on the street.
“We are starting to worry now that the 10-year U.S. Treasury yield may be on the verge of breaking out above 5%,” he said.
He blamed the bond market, the war in Iran and November’s midterm elections.
A second problem hides inside Friday’s numbers. Technology and industrials were the only sectors that rose. Yet higher yields hurt technology hardest, because those profits sit furthest in the future. The sector holding the index up has the most to lose.
What Each Event this Week Could Do to Share Prices
Monday brings the oil question. Saudi air defenses destroyed a missile fired at Riyadh, coalition spokesman Major General Turki al-Maliki said. Brent crude still closed near $104 on Friday, up more than 13% in a month.
Expensive oil splits the market. Energy producers earn more. Airlines and retailers pay more. It also traps the Fed, which raised rates last week and may have to do it again.
“The plain fact is that inflation is too high and has been for too long,” said Kevin Warsh, chair of the US Federal Reserve.
Wednesday brings another test. S&P Global publishes its flash survey of company managers, the first read on whether costly energy is slowing the economy. Weak growth with high inflation is the mix Wall Street fears most.
Thursday brings another tough gamble. Trump meets Xi at the White House. Tariffs, rare earths and artificial intelligence guardrails are on the table, and the trade truce expires on November 10. A deal lifts exporters and chipmakers. No deal puts tariffs back in play before year end.
Company results add to the mix. KB Home reports Tuesday, and mortgage rates track that same 10-year yield. Costco reports Thursday, where one analyst already warns core earnings could miss forecasts.
Traders spent Friday lifting their bets on another Fed rate rise in October. This week decides whether they were right.
The post What to Expect From US Stock Markets In the Fourth Week of September appeared first on BeInCrypto.
Bloomberg ETF analyst Eric Balchunas said this week that Bitcoin ETFs could eventually reach three times the assets of gold ETFs, pointing to younger investors, falling volatility and stronger sales activity around BTC funds.
His view rests on a long-term shift in who owns Bitcoin and how institutions use it, rather than a claim that the cryptocurrency has already displaced gold as a store of value.
Balchunas Sees Bitcoin Closing the Gap With Gold
In a recent interview with Bitcoin Magazine, Balchunas said younger investors are more likely to grow up treating Bitcoin as a store of value, giving Bitcoin ETFs a potential advantage as those investors accumulate more capital.
“I do believe that Bitcoin ETFs will triple gold in assets,” he said.
Right now, gold is less volatile than BTC, and according to the analyst, volatility is the main concern investors report when considering the flagship cryptocurrency.
But if its volatility and correlation with other assets continue moving closer to gold, he expects larger institutions to become more comfortable using it as a store of value, a safe haven asset or an alternative holding.
Bitcoin is still viewed differently from gold, however, with Balchunas saying it has traded more like the Nasdaq 100 for years, giving it a reputation as a high-beta asset that is closely tied to stocks. He further described it as “gold as a teenager,” contrasting its roughly 17-year history with gold’s much longer record.
His argument also centered on distribution. In a follow-up post, Balchunas pointed out that Bitcoin has “way more enthusiasm and sales firepower.”
He also noted that wholesalers who are familiar with both crypto and the habits of older investors are actively educating clients about BTC ETFs, adding that there is little comparable sales activity around gold ETFs.
The analyst later stressed that his view does not mean gold disappears.
“Gold isn’t going anywhere,” he wrote. “I just think it will be lapped by Bitcoin ETFs as a category long term.”
ETF Flows Show the Picture Is Still Mixed
The latest fund data provides a less straightforward picture. SoSoValue recorded $159.45 million in net inflows into US spot Bitcoin ETFs on September 17, following two difficult sessions in which funds lost $295.98 million on September 16 and $450.33 million on September 15.
For the week through September 17, the ETFs had a combined $426.81 million in net outflows. Meanwhile, cumulative inflows stood at $54.73 billion, while total net assets were $96.25 billion, equal to 6.26% of Bitcoin’s market cap.
As CryptoPotato reported, the products recorded $462.73 million in net outflows across the four trading sessions through September 11. That followed a much stronger period in August, when they attracted more than $1.9 billion in one week.
The post Younger Investors Could Help Bitcoin ETFs Overtake Gold: Analyst appeared first on CryptoPotato.
Sempra (NYSE:SRE) added a long-term customer commitment on September 14, when its infrastructure subsidiary announced a 20-year sales and purchase agreement with Petróleo Brasileiro S.A. – Petrobras (NYSE:PBR). The agreement covers approximately 0.8 million tonnes annually of liquefied natural gas, or LNG.
Supply will come from the subsidiary’s contracted liquefaction capacity at Port Arthur LNG Phase 2 in Texas. The project is under construction, with trains 3 and 4 expected to begin commercial operations in 2030 and 2031, respectively. The agreement improves visibility into future sales, while the earnings contribution depends on delivery and contract economics.

Bull Case
Petróleo Brasileiro S.A. – Petrobras (NYSE:PBR) becomes the infrastructure subsidiary’s first South American LNG customer. That broadens the geographic base of buyers and establishes a commercial relationship extending over two decades.
For Sempra (NYSE:SRE), the practical benefit is an external buyer for part of the subsidiary’s contracted capacity. Securing that relationship before startup could reduce the need to find buyers for the covered volumes as production approaches, while supporting longer-term supply planning.
The annual commitment equals approximately 6.2% of Phase 2’s planned 13-million-tonne annual capacity. This provides a measure of scale, although it does not establish the percentage of capacity still available for sale.
The project also has an established development framework. Phase 2 reached a positive final investment decision in September 2025, and Bechtel Energy Inc. received full notice to proceed with construction. Using the same contractor across both phases could support continuity in execution. The new agreement builds on that existing investment and construction program.
Sempra (NYSE:SRE) has agreed to sell a 45% interest in Sempra Infrastructure Partners, retaining 25% after closing. The transaction remained pending in the latest disclosures, with closing expected in the third quarter of 2026. Its participation in future LNG earnings would reflect that smaller ownership stake.
Bear Case
The announcement does not disclose the pricing formula, expected contract margin, or detailed payment and termination provisions. Those terms determine how much commodity-price exposure remains and how reliably contracted volumes translate into earnings. A 20-year duration alone does not establish fixed revenue or protected profitability.
Construction remains a substantial financial commitment. At the September 2025 investment decision, estimated project-level incremental capital expenditure was approximately $12 billion, plus $2 billion for shared facilities.
[PRESS RELEASE – Sydney, New South Wales, Australia, September 20th, 2026]
Monochrome Exchange, a multi-asset trading platform, has announced the Initial Exchange Offering (IEO) of its native utility token, MCR. The platform aims to consolidate crypto, equities, bonds, and real-world assets into a single venue where trades settle on-chain. The exchange is currently live, featuring over 260 active markets.
MCR Initial Exchange Offering Details
- Date: September 21, 13:00 UTC+8 to September 28, 13:00 UTC+8
- Location: Monochrome Launchpad (monochrome.exchange/launchpad)
- Token Price: $0.88 per MCR
- Public Sale Supply: 10,500,000 MCR (5% of total supply)
- Vesting Schedule: 1-month cliff from Token Generation Event (TGE), followed by 3-month linear vesting
- Commitment Asset: USDT
- Subscription Limits: No minimum; maximum of $100,000 per account

The MCR offering will take place directly on the Monochrome Exchange platform. Users can participate by depositing USDT and committing funds on the offering page during the designated seven-day window. Following the one-month cliff after the TGE, MCR tokens will vest linearly and be credited directly to user accounts.
Live Platform Offerings
Monochrome Exchange currently supports trading across four asset classes from a single account balance:
- Crypto: Spot and perpetual markets.
- Equities: Nearly 150 markets, including tokenized exposure to US and Hong Kong equities (e.g., AAPL, NVDA, TSLA, BYD).
- ETFs and Indices: Over 30 options including SPY, QQQ, and XLE.
- Commodities: Gold, silver, platinum, crude oil, Brent, natural gas, and copper.
- Pre-IPO Markets: Tokenized exposure to private companies, including OpenAI and Anthropic.
Leadership and Backing
Monochrome Exchange was founded by Jeff Yew, former Chief Executive Officer of Binance Australia, where he led local operations for the world’s largest cryptocurrency exchange by trading volume. He subsequently founded Monochrome Asset Management, the investment manager behind the first direct-holdings spot Bitcoin ETF of its kind admitted to trading on Cboe under an ASIC-issued Australian Financial Services Licence.
Yew has over a decade of experience across exchange operations, digital asset licensing and the design of regulated investment products. “Tokenisation has produced a large number of assets that barely trade,” said Jeff Yew. “The harder problem has always been the market underneath them: liquidity, settlement, and compliance that holds up. We listed the markets first and are offering the token second.”
Monochrome Exchange operates as a separate entity from Monochrome Asset Management. Jeff Yew’s professional history does not extend any licence, authorisation or regulatory status of any Monochrome affiliate to Monochrome Exchange or to the MCR token.
How It Works
The offering is conducted entirely within the Monochrome Exchange platform. Participation follows four steps:
- Account. Participants open a Monochrome Exchange account and enable two-factor authentication.
- Deposit. USDT is deposited to the exchange account. Deposits are credited once confirmed on-chain.
- Commitment. Funds are committed on the offering page during the seven-day window, which opens on 21 September at 13:00 UTC+8 and closes on 28 September at 13:00 UTC+8, or earlier if the allocation is filled. There is no minimum subscription and a maximum of $100,000 per account.
- Distribution. MCR is held against the participant’s account from the Token Generation Event. No tokens unlock during the first month. Following the cliff, the allocation vests linearly over three months and is credited automatically as it unlocks.
No external wallet, bridge or on-chain transaction is required at any stage, and no claim transaction is necessary.
MCR Tokenomics and Deflationary Mechanism
The maximum supply of MCR is capped at 210,000,000 tokens. Tokens allocated to the team and advisors are locked for 12 months, followed by a 36-month linear vesting schedule.
 $MCR Tokenomics
 Vesting Schedule
The token incorporates a buy-back and burn mechanism driven by platform activity:
- 20% of net platform profit will be used to buy back MCR from the open market quarterly.
- 25% of all Launchpad and Digital IPO fee revenue will be added to the buy-back allocation.
- Purchased tokens will be sent to a verifiable burn address to reduce the circulating supply.
Token Utility
MCR serves multiple functions within the Monochrome ecosystem:
- Fee Discounts: Holders receive trading fee discounts ranging from 10% to 50%, tiered by holdings.
- Exclusive Access: MCR acts as the access token for Launchpad offerings and upcoming Digital IPOs, with allocations weighted by user balances.
- Staking: Users can stake MCR to earn rewards, increase allocation weight, and qualify for the node program.
- Governance: Holders can participate in voting on platform listings, Launchpad parameters, and treasury deployment.
Digital IPOs and Leadership
Monochrome Exchange is developing a Digital IPO framework designed to streamline the public listing process by moving issuance, subscription, allocation, and settlement on-chain. MCR will be required to participate in these offerings. The platform schedules its first Digital IPO for Q1 2027.
The exchange was founded by Jeff Yew, former CEO of Binance Australia and founder of Monochrome Asset Management. Yew brings a decade of experience in exchange operations and digital asset licensing. Monochrome Exchange operates as a separate entity from Monochrome Asset Management. Jeff Yew’s professional history does not extend any license, authorization, or regulatory status of Monochrome affiliates to Monochrome Exchange or the MCR token.
About Monochrome
Monochrome Exchange is a multi-asset trading venue where crypto, equities, ETFs, commodities and pre-IPO markets trade from a single account and settle on-chain. The platform currently lists more than 260 markets, including tokenised exposure to US and Hong Kong equities, index and sector ETFs, precious metals and energy, and private companies including OpenAI and Anthropic.
Monochrome Exchange was founded by Jeff Yew, former Chief Executive Officer of Binance Australia and founder of Monochrome Asset Management, the investment manager behind the first direct-holdings spot Bitcoin ETF of its kind admitted to trading on Cboe. MCR is the native utility token of the exchange, used for trading fee discounts, allocation in Launchpad offerings and Digital IPOs, staking and governance.
Monochrome Exchange is a separate entity from Monochrome Asset Management and operates independently of it.
Socials
Website: monochrome.exchange
Twitter: x.com/Monochrome_EN
Disclaimer
MCR is a utility token and does not confer ownership, dividends, profit-sharing, or redemption rights. Digital assets carry significant risks, including total loss. Users are advised to review the full documentation, risk factors, tokenomics, and vesting schedules at docs.monochrome.exchange prior to participation.
The post Multi-Asset Trading Venue Monochrome Exchange Announces IEO of Its Native Token, $MCR appeared first on CryptoPotato.
Crypto derivatives markets are moving toward two main products, perpetual futures and options. Perpetuals provide continuous leverage, while options are becoming more important for pricing and managing risk.
That shift is also visible in how traders are allocating capital across derivatives. A Glassnode study produced with Bybit found that options increased their share of Bitcoin notional open interest from about 25% to nearly 50%. Meanwhile, dated futures have lost ground in the crypto market.
Options Are Becoming More Important
Dated futures volume is now roughly 97% below its 2021 level, according to the study. Perpetual futures have taken a larger role in leverage, while options have gained ground in volatility trading and hedging.
The growth in options has not been limited to bullish market conditions. Glassnode found that options gained market share in four of the five market regimes it examined since 2019. The largest increase came during a prolonged bear market, when demand for hedging can become more important. This suggests that traders use options not only for directional bets but also to manage risk.
Recent venue data shows that the shift is also changing where Bitcoin options trading takes place. Data through the settled close of August 23, 2026, showed Bybit’s share of options volume across four crypto-native venues rising from below 10% to 28%.
Bybit Expands Its Options Market
Ether has also become an important part of Bybit’s options activity, accounting for 32% of its options volume over the previous 90 days. That was the highest share among the four venues, ahead of OKX at 26%, Binance at 24% and Deribit at 12%.
Bybit also recorded the highest Ether options volume among the four venues for 143 consecutive days. Glassnode measured the lead using both coin and dollar volumes to reduce the effect of changing prices.
The concentration extends beyond crypto assets. Bybit’s tokenized gold perpetual market was the largest among tracked crypto venues for 476 consecutive days, while the platform held 97.1% of gold options open interest.
Bybit’s broader options market has also grown significantly, with its options book rising from $529 million in its first month to $2.33 billion. Growth was uneven, however, as options initially lost share while perpetual activity expanded before recovering.
The post Options Nearly Double Their Share as Crypto Derivatives Market Shifts: Report appeared first on CryptoPotato.
Crypto World
Open-source Memecoin launchpad adds 1,373 lines of solidity in latest development release
In crypto, a roadmap can describe what a project wants to build. Public code shows what developers have started to build already. That distinction is especially important for a memecoin launchpad, where users need to know how funding, token supply, refunds, and liquidity are meant to work.
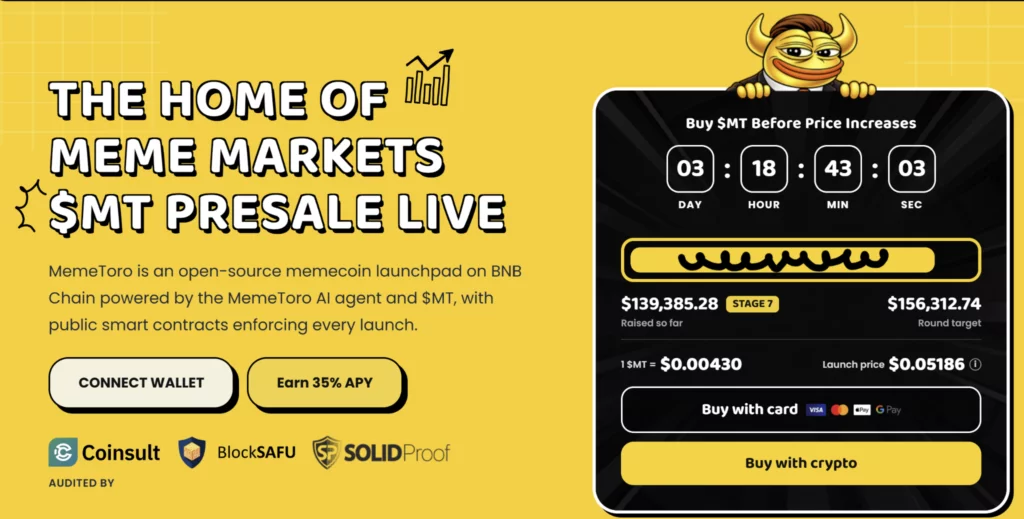
MemeToro has released 1,373 lines of Solidity code across 17 files in its latest update. The project is building an AI-led fair-launch platform on BNB Chain and has raised more than $139,000 in its $0.00430 Stage 7 presale.
The open-source update gives buyers and developers a clearer view of the proposed system, including its smart-contract rules and the work still required before mainnet deployment.
About MemeToro and its new AI agent on BNB chain
MemeToro is a planned BNB Chain ecosystem for discovering, funding, and trading memecoins. Its main goal is to use an AI agent to research trends and propose launches with documented reasons instead of relying on unverified hype.
The agent is designed to collect social, market, and news evidence. It then prepares a launch manifest that users can read before deciding whether to support a round.
The launch manifest is meant to show the proposed token structure, price, funding cap, and data sources. It gives buyers more information than a standard token announcement.
MemeToro’s validators are designed to reject proposals that fail basic rules. They can reject unsupported URLs, allocation totals that do not equal 100%, insider allocation above zero, and funding terms that conflict with the proposal.
$MT is the planned ecosystem token. It is intended to support access, funding, staking, rewards, memecoin trading, prediction markets, and a news portal.
The project is therefore building both an AI proposal layer and a contract layer. The agent suggests a launch, while smart contracts are meant to enforce the accepted rules.
What a $500 $MT position could look like
At the current $0.00430 Stage 7 rate, $500 would provide about 116,279 $MT before fees. MemeToro’s displayed launch target is $0.05186.
If $MT traded at that level, the allocation would have a theoretical paper value near $6,028, or about 12.06 times the original amount.
At a $1 billion fully diluted valuation, each $MT would be worth about $0.8333 based on the stated 1.2 billion supply. The same $500 allocation could then be worth around $96,899.
These figures are illustrative. They do not account for liquidity limits, slippage, transaction fees, taxes, supply changes, or the risk that $MT trades below the purchase price.
The real opportunity depends on whether MemeToro finishes the product and attracts enough users to make its AI-led fair-launch model valuable after the presale.
The 1,373-line release builds the first contract layer
The latest update includes 17 files and 1,373 new lines of Solidity code. The main addition is FairLaunchEscrow.sol, a contract designed to hold contributor funds for one memecoin launch round.
The update also introduces ILaunchExecutor.sol. This is the planned plug-in point where future token deployment and liquidity work will connect to the escrow.
A third component, IERC20Minimal.sol, provides the basic token functions needed to support future claim payments. The release also adds documentation, architecture notes, contributor rules, and a full test suite.
The code is built with Foundry, a common Solidity toolkit used for contract development and testing. This allows outside developers to inspect the design and review how the functions are meant to work.
Open-source code does not eliminate risk. It does provide a public trail of development that buyers can compare with the project’s public claims.
The contract design focuses on what cannot happen
MemeToro’s fair-launch draft is designed without an owner, admin role, or upgrade path. This is meant to prevent a team from adding new privileges after a round goes live.
The contract locks round settings at creation. It also stores a fingerprint of the public launch manifest, so users can compare the on-chain terms with the plan they saw before contributing.
The design limits contributor funds to two outcomes: refunds or the planned liquidity process. It does not include a stated route for developer or treasury withdrawals.
The allocation logic is designed to prohibit insider supply. Contributors and liquidity must account for the total supply, while any rounding remainder goes to liquidity.
This is a major part of MemeToro’s bullish case. Instead of saying “trust us, there are no insiders,” the project is publishing code intended to make an insider allocation incompatible with the launch math.
The final system still needs independent review and real-world testing. But the initial contract structure gives the community something concrete to examine.
Tests and remaining milestones show a serious development path
MemeToro’s test suite checks the important launch states: funding caps, deadlines, thresholds, refunds, claims, and unexpected behavior from connected contracts.
Random-sequence testing is also included. This checks that the contract’s accounting remains balanced across many possible transaction orders and that users cannot claim more than they are owed.
The team added two extra tests to ensure the code reaches funded, launched, claimed, and refunded states. That is a useful detail because a passing test is not enough if it never enters the situation it is meant to verify.
The project still needs to complete the real token executor, manifest-to-contract integration, deployment scripts, factory, BNB Chain testnet launch, ERC-8004 agent identity, and independent security review.
MemeToro lists Coinsult, BlockSAFU, and SOLIDProof as audit or review providers. These give buyers three named firms to check alongside the public code and official project updates.
More Information on MemeToro ($MT) Presale Here:
Website: https://memetoro.com/
Telegram: https://t.me/memetoro_mt
YouTube: https://www.youtube.com/watch?v=gY0jgWy_DtA
Morgan Stanley met privately with Gilead Sciences (GILD) leadership at its 2026 Global Healthcare Conference this month, and the feedback strengthened the bank’s positive view on the stock.
Morgan Stanley’s biopharma team hosted a meeting and a management dinner with Gilead Chairman and CEO Daniel O’Day and Chief Commercial and Corporate Affairs Officer Johanna Mercier. According to a Morgan Stanley research note shared with me, the discussion reinforced its Overweight rating on Gilead and singled out one franchise as the biggest reason to stay positive.
Gilead trades around $150.89, up about 24% year to date and roughly 111% over five years. That kind of run in a biotech stock usually needs a catalyst, and Morgan Stanley points to HIV prevention. The bigger question for investors now is whether the new HIV prevention business built around Yeztugo can keep growing at the pace of the last few quarters.
What Morgan Stanley heard from Gilead’s leadership
Terence Flynn, a Morgan Stanley equity analyst who covers Gilead and other healthcare stocks has held an Overweight rating on the stock since January 2025.
According to the note, Gilead management described the company as being at “an important inflection point, supported by what it views as the most robust portfolio in the company’s history,” with no patent expiring until 2036.
That setup is rare, since most large-cap drugmakers usually spend time preparing for a patent cliff. A patent cliff is what happens when a top-selling drug loses its patent protection and cheaper copies flood the market, which reduces revenue.
Flynn’s price target uses a discounted cash flow model with a 10% weighted average cost of capital and a 3% terminal growth rate, based on the September 15 close of $146.30. The Overweight rating was already in place before the conference, so the note is a confirmation of the existing call.
Gilead earns most of its money from HIV medicines but also sells drugs for hepatitis, oncology, and liver disease. That mix supports cash flow while newer launches ramp up.
Yeztugo is the main reason for Morgan Stanley’s positive view
Yeztugo, the twice-yearly HIV prevention shot Gilead launched in 2025, is the main reason for the bank’s positive view. Yeztugo is a form of PrEP, or pre-exposure prophylaxis, which is a drug people take to prevent HIV infection before they are exposed.
Gilead’s management guided its first full year of Yeztugo sales at approximately $1 billion, with the total prevention portfolio running at about $4 billion annually. According to the note, Yeztugo is drawing “a healthy mix of patients switching from existing PrEP options and individuals entering the category for the first time.”


#BitcoinMining #cryptocurrency #btc #Blockchain #bitcoin
Manchester United problems clear and key talking points from draw at Fulham FC

He Converted $40,000 a Year for Ten Years. His Brother Left the Same $450,000 Alone and Watched It Grow to $730,000. Only One of Them Owns What the Statement Says




-
 Fashion2 days ago
Weekend Open Thread: Talbots – Corporette.com
-
 Crypto World2 days ago
Circle launches Arc Studio AI agent for building onchain apps
-
 NewsBeat2 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World6 days ago
Revolut Attackers Warn of Ongoing Daily Customer Data Leaks
-

 Crypto World6 days ago
Kraken Lets xStocks Holders Earn Yield Through DeFi
-
 Crypto World5 days ago
Robinhood engineers charged over $50K crypto scheme
-

 Crypto World5 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-
 Crypto World2 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Crypto World4 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 Crypto World6 days ago
Elon Musk Drops a Bombshell: Grok 5 Could Be the AGI Breakthrough
-
 NewsBeat6 days ago
‘Sick conspiracy’: Trump says only guardrails AI needs is ‘a strong and smart (High IQ!) president’ in all-caps rant
-

 Crypto World6 days ago
NVIDIA Analysis: Attempted Rising Wedge Breakout Amid Pressure on the AI Sector
-
Business6 days ago
SK Hynix ADRs Fall More Than 6% as Memory Rally Breaks on Fears of Slower AI Spending
-

 Crypto World7 days ago
3 Token Unlocks to Watch in the Third Week of September 2026
-
 Tech5 days ago
Webb’s IC 348 Mosaic Includes Two-Jupiter Dwarfs, Twin Jets, and a Nursery Still Making Worlds
-
Crypto World6 days ago
Can Circle’s Arc Repeat Robinhood Chain’s Meme Coin Boom?
-

 Crypto World6 days ago
DOJ Seeks to Seize $61M in Iran Oil Funds From Binance Accounts It Vouched For
-
 NewsBeat2 days ago
US was ‘on brink of war’ with China over false AI report of nukes moving in Middle East
-
 Entertainment5 days ago
Big Brother Update: Melody Explodes at Drew as Illness Sweeps BB28 House
-
 Crypto World2 days ago
World Money launches in 150+ countries with Stripe
You must be logged in to post a comment Login