
Crypto World
ECB wants stablecoin yield ban expanded across crypto lending and staking

The European Central Bank and national central banks across the European Union have called for MiCA’s stablecoin remuneration ban to cover lending, borrowing, staking and other arrangements that can generate indirect returns for token holders.
Summary
- ECB backed central banks want MiCA’s stablecoin yield ban extended to lending, borrowing and staking products.
- The ESCB said indirect returns could allow platforms to turn stablecoins into yield bearing arrangements despite existing restrictions.
- Central banks proposed replacing MiCA’s minimum bank deposit requirements with reserve rules based on one to five day liquidity.
According to the European System of Central Banks, the restriction should extend beyond services already regulated under the Markets in Crypto Assets framework because crypto platforms could structure products outside MiCA that effectively turn stablecoin holdings into yield bearing arrangements.
“Electronic money is intended to be used for making payments and not as a means of saving,” the ESCB said in its 57 page response to the European Commission’s consultation on reviewing MiCA.
The central banks said they “continue to support the prohibition on CASPs paying remuneration on stablecoins,” referring to crypto asset service providers. Existing restrictions should cover both direct payments and returns generated through other products, according to the response.
Stablecoin yield ban could extend to lending and staking
MiCA prevents issuers of electronic money tokens and crypto asset service providers from granting interest in relation to those tokens. The ESCB wants EU lawmakers to make clear that the restriction cannot be bypassed by placing stablecoins inside lending, borrowing, staking or similar products.
Stablecoins can be “transformed into yield-bearing arrangements through lending, staking or other layered structures,” the central banks said. Such products could provide holders with an economic return even when the stablecoin itself does not directly pay interest.
The ESCB said allowing such arrangements could weaken the regulatory distinction between electronic money and bank deposits while creating unequal conditions between crypto companies and regulated financial institutions.
“Maintaining and, where necessary, strengthening the prohibition, covering both direct and indirect forms of remuneration, should be a clear legislative priority,” the group said.
The position closely resembles a dispute that has shaped debate over stablecoin rewards in the United States.
As crypto.news previously reported, eight banking associations asked U.S. lawmakers in September to tighten the CLARITY Act’s restrictions on stablecoin incentives. The groups argued that rewards linked partly to balances or holding periods could operate like interest on bank deposits even when another condition was attached to the payment.
Banking groups have focused on the potential effect on deposits because those funds are used to support mortgages, business financing and other lending. In July, the American Bankers Association, Independent Community Bankers of America and 76 state banking associations sought tighter restrictions on incentives that could encourage customers to hold stablecoins instead of keeping money in bank accounts.
Citigroup CEO Jane Fraser raised a similar concern in August, warning that stablecoin reward programs could reduce deposits available to lenders. Fraser supported passage of the CLARITY Act but said changes were still needed to its stablecoin reward provisions.
The U.S. legislation later failed to advance in a 50 to 49 procedural vote on Sept. 15, with the debate covering stablecoin rewards as well as ethics and other provisions.
ECB backed banks want MiCA reserve rules changed
Alongside the remuneration restrictions, the ESCB proposed changing how MiCA regulates reserves backing stablecoins.
Current EU rules require issuers of tokens referencing official currencies to keep at least 30% of the amount referenced in each currency as deposits with credit institutions. The requirement rises to 60% for significant tokens.
The central banks want those minimum deposit requirements removed because large stablecoin issuers could become an unstable source of funding for banks. If an issuer faced heavy redemptions, it could need to withdraw a large deposit over a short period, according to the ESCB.
Such withdrawals could expose the receiving bank to sudden funding pressure at the same time the stablecoin issuer is trying to obtain cash to satisfy redemption requests.
Instead of requiring a fixed share of reserves to remain in bank deposits, the ESCB proposed rules based on how quickly reserve assets can mature or be converted into cash.
The approach would require issuers to maintain specified portions of their reserves in assets with maturities ranging from one to five working days, giving them liquid assets that can be used to handle redemptions without relying as heavily on withdrawals from banks.
Existing MiCA rules already require reserve assets to be managed in a way that addresses liquidity risks arising from holders’ permanent redemption rights. EU law requires the European Banking Authority, working with the European Securities and Markets Authority and the ECB, to specify liquidity requirements covering daily and weekly maturities.
Liquidity rules would focus on one and five day maturities
The ESCB pointed to European Banking Authority standards as a basis for the proposed structure.
Under the liquidity framework, significant stablecoins referencing official currencies would need at least 40% of reserve assets available within one working day and 60% within five working days. For non significant tokens, the corresponding thresholds would be 20% and 30%.
EBA standards were calibrated partly using observed deposit outflows connected with crypto related events. The framework covers cash and other reserve assets according to how quickly they can mature, be withdrawn or otherwise become available to meet redemption demands.
The proposal would therefore separate the amount of liquidity an issuer needs from the amount it must place directly with commercial banks. Stablecoin issuers would still need sufficient liquid reserves, but compliance would depend more heavily on the maturity profile of those assets.
The ESCB’s position comes as European authorities continue refining MiCA after its stablecoin provisions began applying in June 2024. The framework introduced EU wide requirements for asset referenced tokens and electronic money tokens, including reserve management, redemption rights and additional requirements for tokens classified as significant.
MiCA requires reserve assets to be legally and operationally segregated from an issuer’s own estate, while significant tokens face additional prudential requirements and heightened supervision.
European regulators have previously focused on redemption risk when setting the liquidity framework. The EBA’s technical work kept separate one day and five day liquidity buckets, while significant tokens face higher thresholds because of the potential scale of redemptions.
The ESCB’s latest proposal would retain that liquidity based approach while removing the rule forcing issuers to keep a minimum 30% or 60% of relevant reserves as bank deposits.
In the United States, banks have pursued a related argument from the opposite side of stablecoin balance sheets. Their focus has been on preventing reward paying stablecoins from drawing deposits away from lenders, while the ESCB’s reserve proposal addresses the risk created when stablecoin issuers themselves place large deposits inside banks.
The dispute over rewards remained active ahead of the September CLARITY Act vote. Banking groups argued that incentives tied to stablecoin balances could resemble deposit interest, while crypto companies sought to preserve rewards linked to transactions and other platform activity. A Senate compromise had sought to restrict passive yield while retaining some activity based incentives.
The ESCB wants the EU prohibition to cover indirect remuneration regardless of whether the return comes directly from the stablecoin issuer or through lending, staking or another layered product offered around the token.

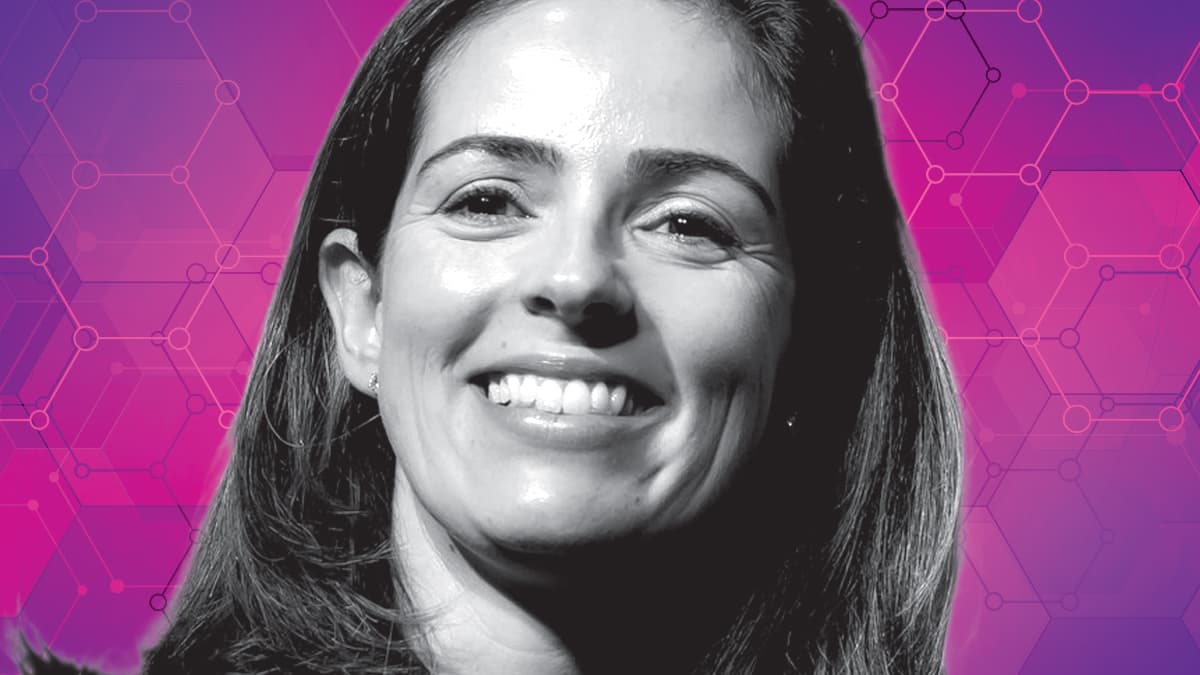
Monica Caldas says she likes “living on the edge.” She’s tasked with rewiring a century-old company for what she calls “the intelligence era.” As EVP and global CIO at Liberty Mutual, her core idea is doing two hard things at once, modernizing old systems while rebuilding around AI. That means embedding AI across core work like underwriting and claims, with more than 100 capabilities already in production.
In May, Liberty became the first insurer to launch a ChatGPT auto-quoting app, part of a bigger bet on “agentic commerce,” where buying insurance shifts from filling out forms to simply having a conversation. “I love to solve big, hairy things with tech,” Caldas says. Her drive started early. She arrived in the U.S. from Portugal in third grade without knowing a word of English and became the first in her family to go to college.
Join Our Telegram channel to stay up to date on breaking news coverage
Strategy bought 950 bitcoin for roughly $75.7 million last week and paid for it from cash on hand rather than new stock sales, according to an 8-K filing dated Sept. 21. The company, formerly known as MicroStrategy, now holds 846,000 BTC, its highest reported total since June.
The filing covers purchases made between Sept. 14 and 20 at an average price of $79,670 per coin. Across all holdings, Strategy has spent about $63.8 billion, an average of $75,416 per bitcoin.
A change in how the buying is funded
What marks this filing out is the funding. Strategy’s recent accumulation runs have typically been financed through at-the-market equity offerings, selling new shares to raise cash. This time the company said the purchases came from its USD Cash reserve, which stood at $1.05 billion as of Sept. 20. A second bucket, the USD Reserve, held $5.04 billion on the same date.
The same filing shows Strategy repurchased 1,771,238 shares of its STRC preferred stock for $174 million, and used $57.4 million of the USD Reserve to pay preferred dividends and interest on outstanding debt. It reported no bitcoin sales under its at-the-market offering during the week.
The shift matters because it suggests the company is no longer leaning on new share issuance to fund the treasury, after a stretch in which its preferred stock traded below par and reserve money went to servicing it. The filing discloses the buyback but not its rationale.
Mark-to-market figures from the week put the holdings at around $71.9 billion, implying roughly $8.1 billion in paper gains. Those numbers move with bitcoin’s price and should be read as a snapshot, not a balance.
846,000 BTC is more than 4% of bitcoin’s 21 million supply cap. The company’s reported peak was 847,363 BTC in June, before it sold 1,363 coins.
Join Our Telegram channel to stay up to date on breaking news coverage
Accenture works with many Fortune 500 companies, helping them deploy AI without becoming locked into a single model or platform. The company has already generated billions of dollars in generative AI bookings, while Guan says deployments for clients like the Australian bank Westpac have cut some workflows from months to days.
Now she’s tackling the cost of scaling those systems. Accenture has recently focused on tokenomics, arguing that firms incorrectly default to the most powerful—and expensive—models even when the work doesn’t require such heft. “Only about 20% of enterprise workflows actually deserve frontier models,” she says.
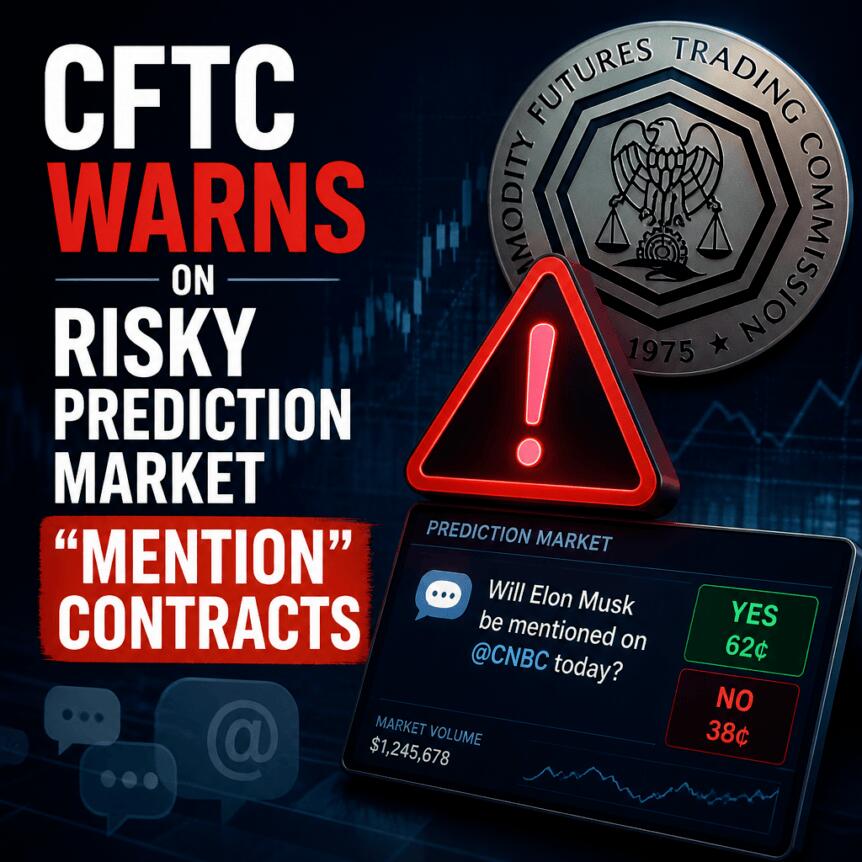
The U.S. Commodity Futures Trading Commission (CFTC) has issued a warning to regulated exchanges about “mention markets,” a type of prediction contract that settles based on whether a person says or does something. In a Tuesday advisory, the regulator said these contracts carry a heightened risk of manipulation and should only be listed in limited circumstances under the Commodity Exchange Act.
The guidance comes as prediction market activity draws growing regulatory scrutiny, particularly after enforcement actions tied to allegations that traders benefited from non-public information. For exchanges weighing whether to list event contracts tied to an individual’s specific words or conduct, the CFTC’s letter lays out a framework for assessing settlement verifiability and oversight readiness.
Key takeaways
- The CFTC says “mention markets” present a heightened manipulation risk because settlement depends on a person’s discrete conduct, which may not be verifiable or independently generated.
- The commission advised that there are only “limited circumstances” where mention markets can be listed consistently with the Commodity Exchange Act.
- Exchanges should evaluate oversight capabilities to detect manipulation and whether settlement criteria are independently verifiable.
- External pressure that could influence the subject’s conduct—and any related obligations the subject may have—are part of the CFTC’s review.
- The warning follows enforcement involving prediction contracts tied to political speeches, underscoring the regulator’s focus on information advantage and settlement conduct.
Why “mention markets” drew a regulator warning
In its advisory, the CFTC’s Division of Market Oversight said mention markets—contracts based on whether an individual will say certain words, attend or appear at an event, or interact with another person—may be inconsistent with the Commodity Exchange Act except in narrow cases.
The regulator’s central concern is that the settlement mechanism relies on conduct that can be neither independently generated nor externally verifiable. According to the CFTC, that structure “presents a heightened risk of manipulation” because it can make it easier for market participants to affect outcomes or profit from information advantages related to someone’s future actions.
The CFTC press release about the advisory is available via the regulator’s website: https://www.cftc.gov/PressRoom/PressReleases/9302-26.
Enforcement history is shaping the regulator’s approach
The CFTC’s warning arrives amid a string of allegations and cases where traders were accused of using privileged information to profit in prediction markets. One prominent example cited in the report involves a former White House teleprompter operator who was ordered last month to return $107,539 in profits and pay a $65,000 civil penalty related to contracts tied to then-President Donald Trump’s speeches.
Earlier coverage from Cointelegraph discussed that case in the context of how politically tied prediction contracts can intersect with information access. See: https://cointelegraph.com/news/trump-teleprompter-operator-made-100k-betting-kalshi-markets-tied-to-speeches-abc.
By emphasizing the risks tied to “discrete conduct” and limited verifiability, the CFTC’s guidance signals that settlement design matters as much as trading behavior. Even if a contract’s price action reflects legitimate market views, the regulator appears concerned when the contract outcome can be influenced—or when market participants can act on information about what a person will do or say before that conduct becomes public.
What exchanges are expected to consider
According to reporting by CNBC, the CFTC letter outlines four factors that exchanges listing mention markets should consider:
- Whether there are adequate oversight measures in place to detect manipulation.
- Whether the words or actions used for settlement are independently verifiable.
- Whether external pressure could influence the subject’s conduct, potentially affecting whether the event occurs as expected.
- What outside obligations the subject of the mention market may have, which could shape their behavior or the likelihood that the contract condition will be met.
This checklist frames mention markets not just as a novel product category, but as a compliance and risk-management challenge. Exchanges that previously treated these contracts as straightforward event bets may now need to demonstrate stronger controls around how outcomes are determined and how manipulation could realistically occur.
CFTC leadership ties the advisory to “regulatory clarity”
CFTC Chair Mike Selig publicly welcomed the guidance in an X post on Tuesday, saying that “regulatory clarity drives sound markets.” In the post, he referenced staff reminding designated contract markets (DCMs) of their obligation to list only contracts that are not readily susceptible to manipulation.
The chair’s post is available at: https://x.com/ChairmanSelig/status/2102500746834874859?s=20.
While the advisory is addressed to regulated entities, the implications extend across the broader prediction market ecosystem. As more contracts are designed around human behavior—rather than purely observable, externally confirmed outcomes—platforms may face tighter scrutiny on whether the settlement criteria can be verified without ambiguity and whether market structure could incentivize gaming of the subject’s conduct.
What to watch next for prediction markets
Exchanges considering mention markets will likely need to document how their oversight can identify manipulation and how settlement conditions can be verified. The most immediate uncertainty for market participants is how broadly regulators will interpret the “limited circumstances” standard—particularly as more politically or socially contingent contracts come under review.
Crypto World
CFTC says prediction markets’ ‘mentions’ contracts present a higher risk of manipulation
The Commodity Futures Trading Commission advised some of its regulated entities on Tuesday that prediction markets’ “mentions” contracts are at greater risk of manipulation.
In a press release announcing the letter it sent to designated contract market entities, the CFTC said that the contracts are more susceptible to exploitation “because their settlement turns on the discrete conduct of a person that may be neither independently generated nor externally verifiable.”
The letter noted that the agency was not creating new obligations that regulated exchanges need to follow, but rather advising entities on when mention markets may be listed consistent with the Commodity Exchange Act, the law that governs the assets that the CFTC regulates.
Mention markets — which are made up of contracts that ask traders what specific words will be used in a speech, a corporate earnings call or during a television broadcast — have come under scrutiny by the CFTC. CNBC reported in August that the agency was conducting an internal review into the contract type, and that platform Kalshi pulled its sports-related mention markets in response to the inquiry.
Kalshi is one of the few U.S. regulated platforms that features mention markets. Its chief rival, Polymarket, only features them on its international exchange, which is not regulated by the CFTC.
“We’ve addressed this guidance based on a prior discussion with the CFTC,” Kalshi spokesperson Elisabeth Diana said in a statement.
Mention markets also generated headlines in July after news reports that a longtime teleprompter operator for President Donald Trump profited off of trades on Kalshi related to contracts on mention markets that were tied to the president’s statements. Gabriel Perez, the teleprompter operator, settled with the CFTC in August and was forced to pay a $172,539 fine for insider trading on a prediction market.
In the letter, the CFTC advised that exchanges listing mention markets should consider four factors: what outside obligations the subject of the mention market may have; external pressure that could influence the subject’s speech or conduct; whether the words or actions used for settlement are independently verifiable; and whether there are adequate oversight measures in place to detect manipulation on the contracts.
The CFTC added that it encourages exchanges to engage with the agency’s division of market oversight while in the early phases of designing mention market contracts on how to mitigate manipulation risks.
Disclosure: CNBC and Kalshi have a commercial relationship that includes customer acquisition and a minority investment.
Artificial intelligence is getting better at doing more than answering questions. AI systems are now helping with coding, research, analysis and other tasks that were once handled almost entirely by people. That raises a new question: what happens when AI starts playing a bigger role in building the next generation of AI?
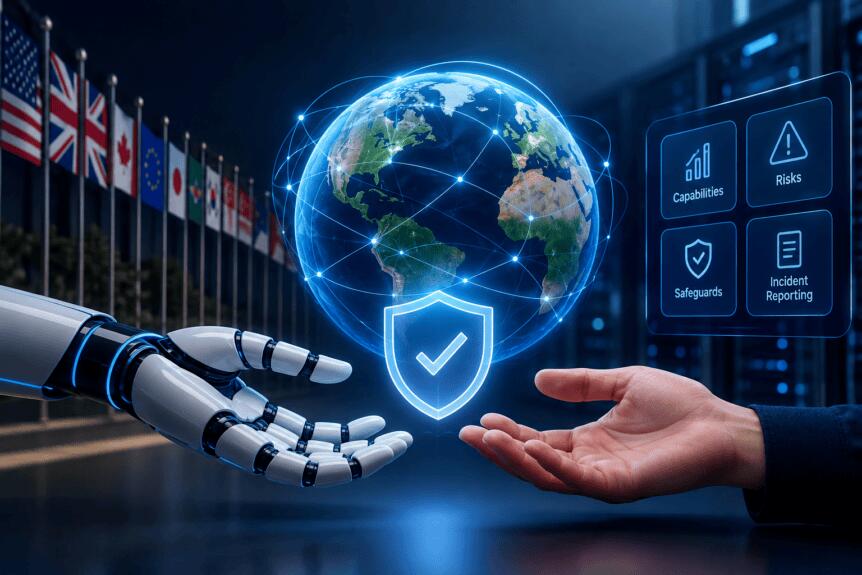
OpenAI is now calling for international standards to help answer that question. In a September 21 post titled “Building standards for the next phase of AI,” OpenAI proposed a US-led international effort to create common technical standards for frontier AI. The company says these standards could help countries measure AI capabilities, evaluate risks, test safeguards and report serious incidents using more consistent methods.
Key Takeaways
- OpenAI wants international standards for evaluating frontier AI.
- The proposal covers capabilities, risks, safeguards and incident reporting.
- OpenAI says fully autonomous recursive self-improvement is not happening today.
- The company wants human control to remain central as AI becomes more capable.
- Existing AI safety organizations could help develop common technical standards.
Openai Wants a Common Framework for Frontier AI
The basic idea is fairly simple. It is not necessary for each country to create an entirely different methodology for evaluating the dangers posed by advanced AI. According to OpenAI, standardizing technical approaches can provide nations, researchers and the AI community an effective way to assess their increasingly sophisticated AI. This becomes all the more relevant when AI-related incidents happen across borders.
The company is not proposing a single global AI law. Instead, it wants countries to develop compatible standards that governments can later decide how to use within their own regulatory systems. This difference is significant since the suggested standards do not immediately become requirements for licensure or certification for all artificial intelligence technologies. Rather, governments retain the power to determine how the standards will apply within their jurisdictions.
Recursive Self-Improvement Is Part of the Conversation
One of the more interesting parts of OpenAI’s proposal is its discussion of recursive self-improvement (RSI). The concept describes a future in which AI systems could increasingly help researchers develop more capable AI systems. In simple terms, AI could become part of the process of improving AI itself.
That could potentially speed up AI research. But it also creates a difficult safety question: how much human oversight should remain in the loop if AI systems become heavily involved in developing future models?
OpenAI says fully autonomous recursive self-improvement is not happening today. It also argues that such a direction should not be pursued unless it can be done safely while maintaining human control. That makes evaluation and safety testing more important as AI systems become capable of handling increasingly complex research and development tasks.
AI Safety Standards Could Become More Important
OpenAI also points to existing AI safety organizations and networks around the world as potential building blocks for this effort. The company specifically references AI safety institutes and related organizations across countries including the US, UK, Canada, France, Germany, Japan, South Korea, Singapore, India, Kenya and Australia.
Rather than every country developing its own completely separate technical approach, OpenAI wants these groups to work toward standards that can complement one another. The proposal also calls for participation from AI developers, researchers, academics and independent technical experts. OpenAI says the standards should be designed around technical measurements rather than the interests of a particular company or country.
Why This Matters
The timing is notable. AI companies are building systems that can increasingly perform multi-step tasks with less direct human input, while governments are still working out how to regulate the technology.
Reuters reported that OpenAI wants the United States to take a leading role in developing international technical standards for advanced AI. The bigger challenge may be getting countries and companies to agree on exactly what those standards should measure and how they should be applied.
For now, OpenAI’s proposal is focused on creating a common technical foundation before frontier AI becomes even more capable. As AI starts doing more of the work involved in developing AI itself, having a shared way to measure capabilities, risks and safeguards could become an increasingly important part of the conversation.
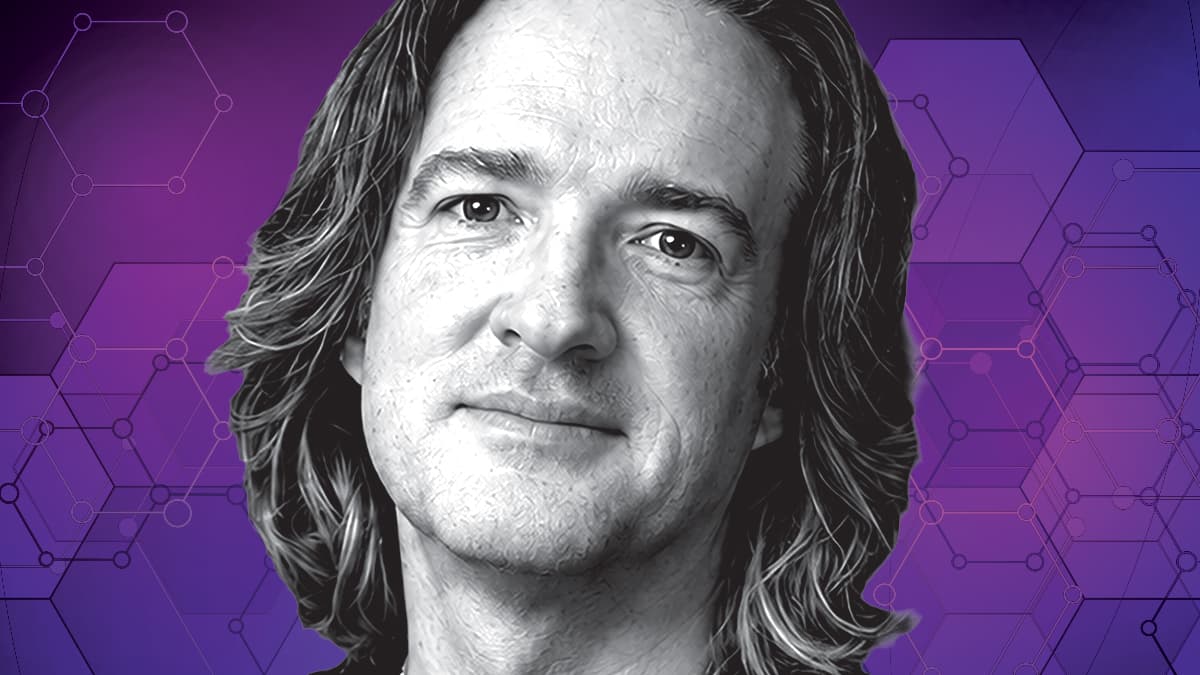
Although AI is fundamentally changing cybersecurity, Bartley Richardson thinks the hackneyed IT refrain still rings true: “The best security is the security you don’t have to think about.” Richardson, a former Nvidia engineer who joined cybersecurity company CrowdStrike in June as its chief AI and autonomous systems officer, says his title perfectly reflects his belief that once consumers trust AI, they’ll stop regarding it as “AI.” Instead, it will be just another autonomous tool making life better in the background, like a grammar check in word processing.
Richardson is shepherding that transition as leader of CrowdStrike’s new Cyber Superintelligence Lab. An AI research lab dedicated to building autonomous cybersecurity systems, its first release is SafeMind, an agentic system that combats AI attacks by pairing an offensive cybersecurity model with a defensive one, creating an autonomous loop of learning and remediation. “An attacker has to be right once, but the defender has to be right all the time,” Richardson says. “We’re giving the advantage back to the defender, and we’re doing that with … better automation.”

Monica Caldas Is one of TIME’s 2026 Executives of the Year: Tech and Data

Raphael Onyedika free to Join Nigeria Squad after Shoulder Injury Scare

Apple Tap to Pay on iPhone expands to Argentina, Columbia, Peru, and more




-

 Fashion4 days ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech2 days ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Crypto World4 days ago
Circle launches Arc Studio AI agent for building onchain apps
-
 NewsBeat4 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World2 days ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-

 Crypto World4 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Crypto World4 days ago
Trading Bitcoin on Robinhood? Why 2% Spread Has Traders Worried
-

 Crypto World6 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 Crypto World7 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-

 Crypto World5 days ago
Mortgage and refinance interest rates today, Thursday, September 17, 2026
-

 Crypto World4 days ago
World Money launches in 150+ countries with Stripe
-

 Business2 days ago
Analog Devices (ADI) Bets $1.35 Billion on Chips that Let Machines Think for Themselves
-

 Crypto World5 days ago
Silver prices recover quickly, hitting weekly high today
-
 Entertainment7 days ago
Big Brother Update: Melody Explodes at Drew as Illness Sweeps BB28 House
-

 Tech5 days ago
GPT-6 Astra Reached the Nether in Minecraft, Lost Its Stash to a Creeper, and Farmed Potatoes for Hours
-
 NewsBeat4 days ago
US was ‘on brink of war’ with China over false AI report of nukes moving in Middle East
-

 Crypto World2 days ago
Coinbase, Robinhood, Circle Seen as Tokenized-Stock Winners
-

 Crypto World2 days ago
Bitcoin price holds above $81K as key catalysts line up
-
 Business7 days ago
Federal Reserve expected to hike interest rates 25 basis points at FOMC meeting
-
 Business4 days ago
Newsom accelerates AI oversight, advances ‘kill switch’ plan
You must be logged in to post a comment Login