
Crypto World
Fed’s Barkin says economy may be firming, inflation not limited to energy, tariff shocks

By Howard Schneider
BALTIMORE, Sept 22 (Reuters) – US economic conditions “are, if anything, firming,” with continued consumer spending and strength beyond the boom in artificial intelligence keeping the Federal Reserve’s focus on inflation, Richmond Fed President Tom Barkin said on Tuesday.
“The risks to inflation outweigh the risks to maximum employment. That’s why we raised rates,” at last week’s meeting, Barkin said in comments prepared for delivery to the CFA Society Baltimore, adding that the quarter-percentage-point hike “will help” restore inflation to the Fed’s 2% target.
“Will additional hikes be required, and how many? We’ll see,” said Barkin, who is not a voting member of the central bank’s rate-setting Federal Open Market Committee this year.
The Fed last week raised its policy interest rate to the 3.75%-4.00% range, with investors anticipating more increases.
Barkin’s comments follow those of other Fed officials who have broadened their concerns about inflation that they feel is being driven increasingly by strong demand in the economy, and not just by energy, tariff and other supply issues that might be expected to fade on their own.
Even those “‘passing’ shocks aren’t proving to be short-lived, or one-off events,” but are producing more persistent price pressures than at first expected, Barkin said.
“It is tempting to try to blame high inflation on a handful of categories with particularly high exposure to the Middle East conflict or to tariffs,” he said. But much of the Personal Consumption Expenditures Price Index is increasing at greater than a 3% annual rate.
“I am hearing momentum outside of data centers, too. The defense sector is hot. Manufacturing contacts are starting to sound more upbeat. Bankers tell us pipelines are healthy,” Barkin said.
(Reporting by Howard Schneider; Editing by Paul Simao)

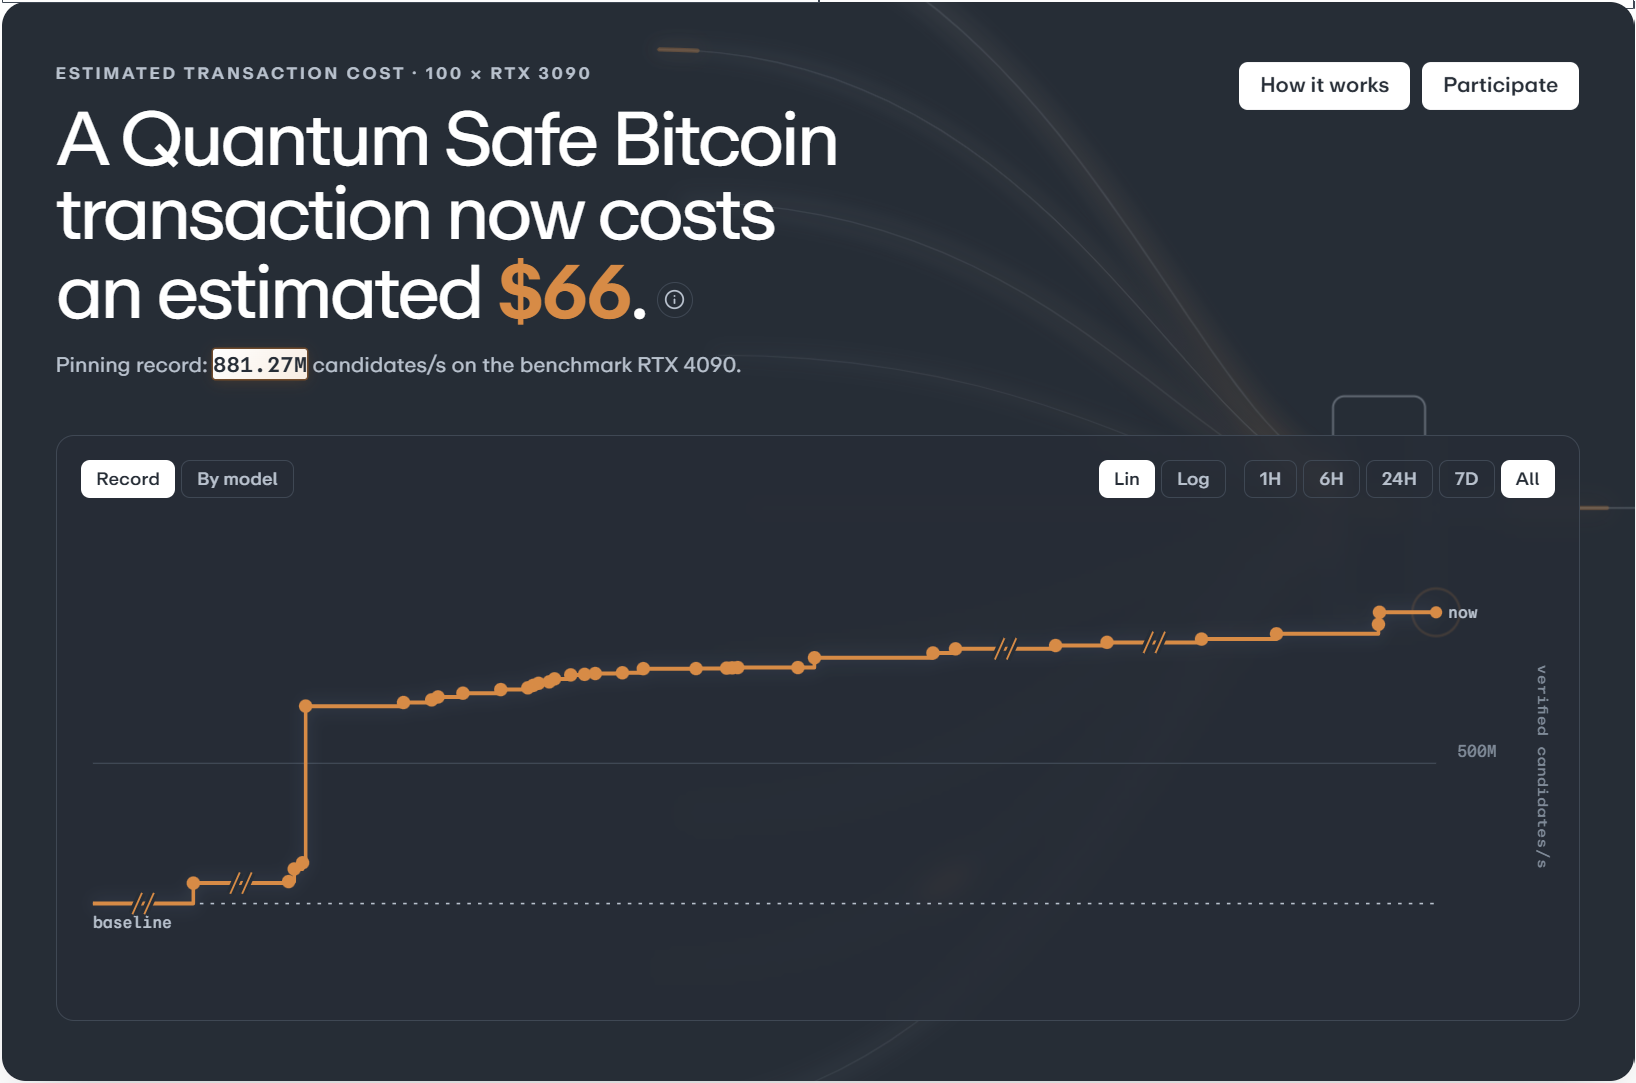
The estimated computational cost to prepare a quantum-resistant Bitcoin transaction has fallen below $67 after a week of optimization, down from the roughly $320 spent on the first such mainnet transaction in August, according to StarkWare.
The results came after participants in the Quantum-Safe Bitcoin Optimization Challenge found ways to push down the GPU computation needed to build a quantum-safe Bitcoin transaction.
The reduction could make the experimental defense (which doesn’t require changes to the network’s consensus rules) against future quantum attacks more practical for Bitcoin holders. However, the latest optimizations have only been demonstrated in benchmark tests.
“A construction that costs a few hundred dollars per transaction is a demo. One that costs $67 is closer to something a holder with a large unexposed balance might reach for in an emergency,” StarkWare wrote in its Sept. 23 update. The dashboard now shows the estimated cost has dropped to $66.
Quantum-Safe Bitcoin an “emergency” solution
StarkWare researcher Avihu Levy published the Quantum-Safe Bitcoin (QSB) design in April, outlining a way to add hash-based protection against quantum attacks without changing Bitcoin’s consensus rules. At the time, he described it as a “last resort measure” due to costs, complexity and limited applicability, while continuing to advocate for protocol-level changes.
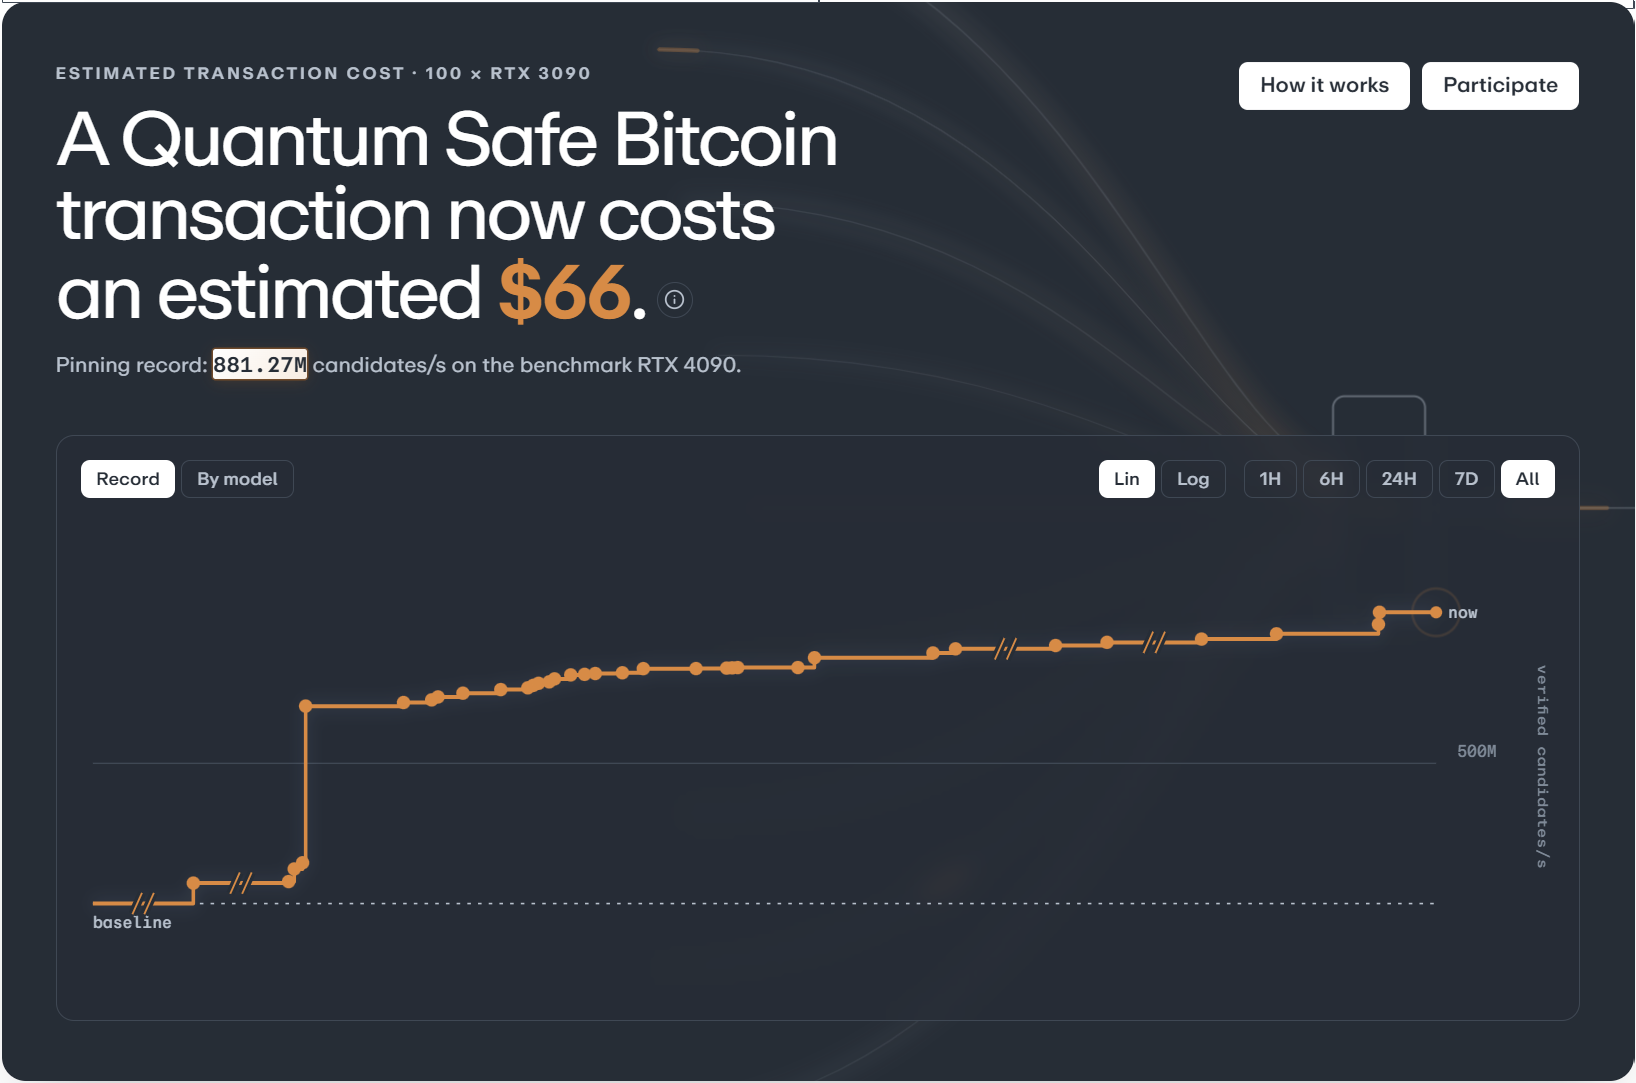
The estimated cost fell by another dollar since publication. Source: Yukon
According to StarkWare, the first QSB transaction was mined and confirmed on Aug. 26, with engineering work from Tomer Giladi and direct submission through MARA’s Slipstream service. Preparing it required approximately 3,100 GPU-hours across roughly 100 GPUs, at a compute cost of about $320, excluding Bitcoin network fees.
Related: Crypto’s first quantum attack will look like unexplained breach: Quantus founder
To find ways to bring that cost down, StarkWare, Yukon Research and Eigen Labs launched the QSB challenge on Sept. 16, inviting developers, researchers and AI agents to make the transaction-building software faster and more efficient.
In its latest update, StarkWare said the challenge produced 62 accepted improvements across two computational tasks needed to prepare a QSB transaction. According to StarkWare, this ended up cutting the estimated computing cost by about 79%, based on benchmark tests.
The development comes amid increasing concern that a sufficiently powerful quantum computer could break the elliptic-curve digital signatures used by Bitcoin, potentially allowing attackers to steal coins whose public keys are exposed.
Researchers are developing quantum-resistant protections, including QSB. However, StarkWare said it still favors a soft fork — a change to Bitcoin’s consensus rules — as a better “long-term answer” for broad quantum protection on Bitcoin.
Magazine: A quantum roadmap would push Bitcoin much higher: Charles Edwards

GE Vernova (GEV) is giving investors another reason to focus on its long-term growth opportunity as surging electricity demand drives a sharp expansion in its order book. The company ended the second quarter of 2026 with a record $176 billion backlog, up $13 billion from the previous quarter, and CEO Scott Strazik recently said GE Vernova remains on track to reach $200 billion in 2027.
The milestone is arriving sooner than the company’s earlier expectations, reflecting strong demand for gas power, electrification, and grid infrastructure as utilities and data center operators invest to meet rising power needs.
More News from Barchart
With backlog visibility improving and demand expected to remain strong, the $200 billion milestone could provide an important catalyst for GEV stock as investors assess the company’s growth prospects through the end of the decade.
About GE Vernova Stock
GE Vernova is a Cambridge, Massachusetts-based energy technology company focused on power generation, electrification, and wind solutions. The company operates through three primary segments: Power, Electrification, and Wind and provides technologies and services spanning gas power, nuclear, grid infrastructure, energy storage, and renewable energy. GE Vernova became an independent public company following its spin-off from General Electric in April 2024 and currently boasts a market cap of $254 billion.
GE Vernova has delivered a strong gain in 2026 despite a recent pullback in the shares. As of the Sept. 18 close, GEV stock was up 46% year-to-date (YTD) and 48% over the past 52 weeks. However, the stock has faced some near-term pressure, declining 1% over the past month and 17% over the past three months.
The recent weakness comes after a substantial rally that pushed the shares to a 52-week high of $1,195.94 in early July, with investors reassessing the valuation and sustainability of the AI-driven power infrastructure boom.
Still, the broader performance reflects strong investor interest in GE Vernova’s exposure to rising electricity demand, gas power and grid infrastructure. The company’s announcement that its backlog is on track to reach $200 billion early in 2027 provides another potential catalyst for investors focused on its longer-term growth trajectory.


Circle has expanded its Cross-Chain Transfer Protocol beyond USDC on Arc, bringing native EURC and cirBTC transfers into the network while preparing Gateway and Bridge Kit for additional multi-asset workflows.
Summary
- Circle expanded CCTP beyond USDC, enabling native transfers for EURC and cirBTC across Arc routes.
- EURC currently moves through CCTP across Arc, Avalanche, Base, Ethereum, and World Chain routes today.
- cirBTC CCTP support currently connects Arc and Ethereum, while Gateway integration remains planned for later.
- Gateway currently unifies USDC balances on Arc and Ethereum, with additional asset support coming later.
- Arc launched September 16 with USDC gas, institutional validators, and interoperability across twenty-plus blockchain networks.
Arc’s Sept. 23 update said Interop on Arc is now live with CCTP, Gateway and Forwarding Service integrated into the Layer 1, giving developers separate tools for native Circle-issued assets, third-party tokens, new multichain assets and unified balances.
The latest deployment does not mean every Circle product already supports all three assets in the same way. CCTP is live for USDC, EURC and cirBTC on specific routes, while Gateway remains limited to USDC at launch. Circle says EURC and cirBTC support for Gateway is planned over time.
Circle expands CCTP beyond USDC on Arc
CCTP now handles native crosschain transfers for USDC, EURC and cirBTC, extending a system that was originally built around USDC burn-and-mint transfers.
Circle’s current CCTP product page describes the protocol as infrastructure that lets supported assets move 1:1 between chains. For Circle-issued assets, CCTP burns tokens on the source network and mints native tokens on the destination, avoiding liquidity pools used by some traditional bridge designs.
EURC entered the system earlier this month. Circle said on Sept. 2 that CCTP had expanded from USDC to native EURC transfers, initially between Ethereum and Base. The Arc launch has since extended EURC coverage to Arc, Avalanche, Base, Ethereum and World Chain.
cirBTC now follows a similar route. Interop on Arc lists CCTP support between Arc and Ethereum for Circle Wrapped Bitcoin, creating a native crosschain path for the BTC-backed token across the two networks.
Circle separately brought cirBTC to Arc on Sept. 21. The company says each token is backed 1:1 by native BTC held for cirBTC holders, with reserve information available for onchain verification. The wrapped asset is issued by Circle International Bermuda Limited, which holds a Class F Digital Asset Business license from the Bermuda Monetary Authority.
Circle launched Bitcoin-backed USDC borrowing through cirBTC on Arc and Ethereum, allowing eligible Circle Mint institutions to post cirBTC to third-party lending markets and receive USDC. Morpho was the first supported lending protocol when the service went live.
EURC and cirBTC get different routes at launch
The three assets do not share identical network coverage. USDC remains CCTP’s most established asset and can use all compatible routes offered through the current Arc interoperability stack. EURC supports Arc, Avalanche, Base, Ethereum and World Chain, while cirBTC currently supports Arc and Ethereum.
Circle says CCTP Fast Transfer can complete transfers in “sub-10-second” times on supported Arc routes. The company cautions in its terms that transfer times and fee estimates are not guaranteed because results depend on the selected chain, route and network conditions.
Forwarding Service handles another part of the flow. It can relay the destination-chain transaction after CCTP completes the asset movement, removing the need for users to separately hold the destination network’s gas token for supported transactions.
Circle updated CCTP earlier in September with prepaid Fast Transfer fees. CCTP now lets developers quote and collect certain crosschain fees on the source network, allowing an application to show the recipient amount before the transfer executes.
Arc routes receive preferential CCTP pricing, according to the Sept. 23 announcement, although rates depend on the asset and route. Circle has not published one universal Arc transfer fee for USDC, EURC and cirBTC.
Gateway still supports USDC before multi-asset expansion
The product creates a unified balance from supported funds held across different networks, allowing applications to treat eligible crosschain liquidity as one available balance. On Arc, Gateway currently supports USDC balances on Arc and Ethereum.
EURC and cirBTC Gateway support is listed as “coming soon.” Circle has not disclosed a launch date for either asset, so CCTP support should not be confused with live Gateway balance support.
Circle’s current legal disclosures likewise describe Gateway as USDC-only. The company says Gateway is non-custodial software infrastructure and does not itself hold, control or transfer customers’ assets. It has not been reviewed or approved by the New York State Department of Financial Services or another regulator, according to the product disclosures.
The company has been building toward multi-asset interoperability for several months. In an April product roadmap, Circle said CCTP had already processed more than $140 billion in cumulative USDC transfers across more than 20 chains and that future versions would extend the same model to assets including EURC and cirBTC.
The Sept. 23 release turns part of that roadmap into production infrastructure, while Gateway’s asset expansion remains unfinished.
Arc lets third-party assets use separate crosschain models
Circle’s interop stack is not limited to tokens issued by Circle. Interop on Arc supports third-party assets through wrapping and a Crosschain Token Standard, or CTS. Developers and issuers can use CTS when they require controls such as allowlists, transfer rate limits, pausing, upgrades and governance rules.
The company says it does not retain override authority over CTS or custom third-party token contracts. Issuers remain responsible for their token structures, operating rules and regulatory obligations.
For new assets, CTS provides a standardized contract structure that can be deployed across chains. Circle describes the system as an alternative to maintaining different token contracts and bridge integrations for each network.
CCTP’s updated architecture supports both burn-and-mint and lock-and-mint models. Native supported assets can move through burn-and-mint, while third-party assets can use wrapping infrastructure where appropriate.
Bridge Kit packages these flows into an SDK for application developers. Arc Studio provides a separate development environment where teams can build applications using the same interop stack without manually connecting every service.
Circle launched Arc Studio as an AI-assisted tool for building applications on Arc, with examples ranging from cross-border payments to software billing and machine-to-machine transactions.
Arc interoperability builds on September mainnet launch
Arc went live publicly on Sept. 16 with USDC used for transaction fees, deterministic sub-second finality and a permissioned founding validator set.
Circle said more than 100 institutional and ecosystem builders and more than 100 applications were participating at launch. Founding validators include BlackRock, DTCC, Galaxy, ICE, Mastercard, MoneyGram, SBI Group, Standard Chartered, Sumitomo Corporation, Visa and Worldpay.
Arc mainnet launched with USDC gas and institutional validators including BlackRock and Visa. Circle said the network began with interoperability across more than 20 blockchain ecosystems through CCTP and Gateway.
Arc’s asset layer has expanded quickly since launch. cirBTC became available on Sept. 21, followed by StableFX on Sept. 22 and the integrated Interop product on Sept. 23. StableFX uses Arc for 24/7 stablecoin-based foreign-exchange settlement with request-for-quote pricing and atomic payment-versus-payment settlement.
Circle says cirBTC can already serve as collateral in Arc lending markets, including supported Aave and Morpho applications. Eligible Circle Mint customers can deposit native BTC, mint cirBTC, provide it to approved third-party lending markets and receive borrowed USDC through Circle’s Digital Asset-Backed Borrowing workflow.
The mainnet roadmap extends beyond interoperability. Circle minted a 10 billion ARC genesis supply before the network launch and is exploring a transition from its current Proof-of-Authority structure toward Proof of Stake in 2027. The company says the genesis mint does not constitute a commitment to publicly launch the ARC token.
Gateway support for EURC and cirBTC remains among the next published interoperability steps. Circle has not provided a launch date, while its Sept. 23 Arc documentation continues to list both assets as “coming soon” for unified balances.
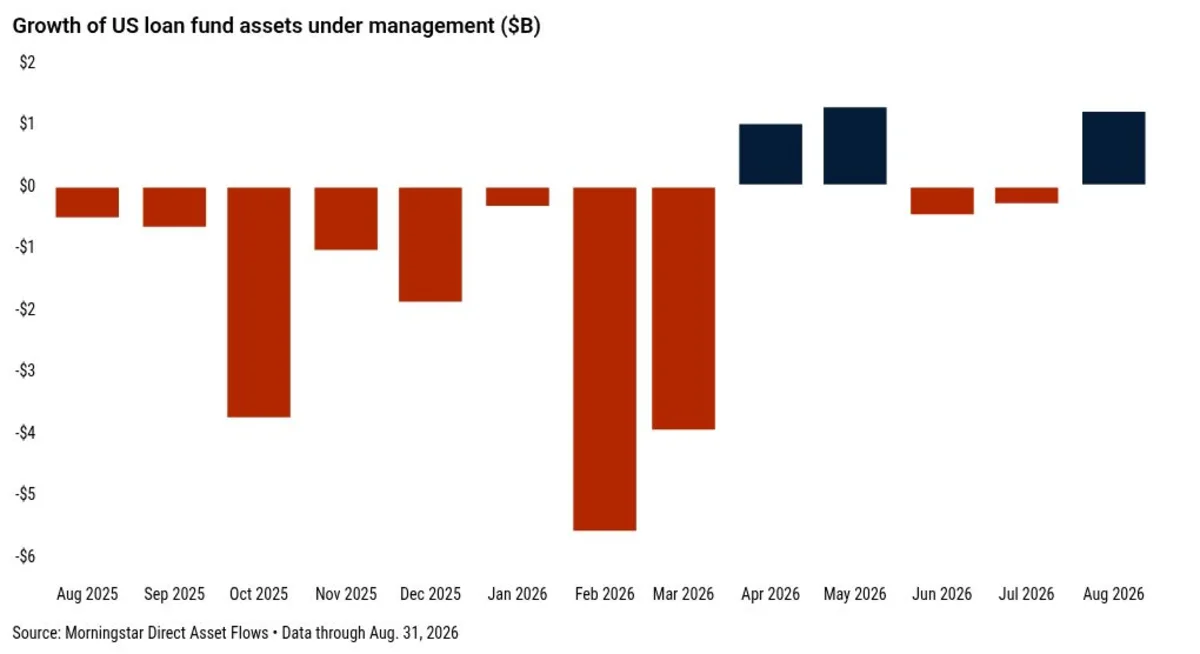
In the run-up to the Fed’s decision to raise the overnight funding rate, assets flowed back into leveraged loan ETFs and mutual funds. Loan fund AUM grew by $1.2 billion in August, according to Morningstar data, and inflows have continued in September. The 0.25-point rate hike on Sept. 16, to 3.75-4.00%, raises the baseline interest return on floating-rate loans.

The first rate hike in more than three years followed a surge in Treasury yields and oil prices. Ten-year Treasury yields have risen from about 4% to 5% since the war in Iran began, and inflation readings have persisted well above the Fed’s 2% target. Investors expect more hikes to come. CME’s FedWatch Tool shows a better-than-50% chance of another 25 bps hike at the October meeting and a target rate of 4.50-4.75% by the end of 2027. As inflows into loan funds have resumed, outflows have increased at fixed-rate high-yield funds, including a hefty $2.5 billion withdrawal in the week through Sept. 16, according to Morningstar.

Rate-hiking cycles have frequently coincided with growth in AUM at leveraged loan funds, while AUM has generally contracted in rate-cutting cycles. The Sept. 16 rate hike ends an eight-month period of rates at a relative minimum (the last cut was in December 2025).

Loans rebound, including software
Prices for leveraged loans have been rising. The weighted average bid price added 41 bps in August, to 95.58, and inched up further to 95.68 by Sept. 21. Software sector loans, which sold off earlier this year, have led the rally.


Funds grow, index grows faster
Since the end of March, AUM at loan funds has grown by $2.7 billion, to $96 billion. Still, loan funds’ share of the Morningstar LSTA US Leveraged Loan Index has slipped to 6.37%, the lowest since September 2009. This continues a longer-term trend of loan fund AUM declining as a share of the growing universe of syndicated leveraged loans, while CLOs have grown as the dominant investors in the asset class.


Sign up for The Credit Pitch
Weekly coverage of US and European loans, bonds, private credit, and more.
Hermen van Laar/Getty Images
This article originally appeared on PitchBook News
FedNow has moved closer to supporting cross-border payments as Federal Reserve Financial Services prepares early institutions to test enhanced messages for the U.S. leg of international transactions.
Summary
- FedNow will support cross-border use cases while settling only the U.S. domestic payment leg directly.
- Early adopters will test enhanced ISO 20022 messages before wider participant access becomes available nationwide.
- Regulation J changes remain proposed, with cross-border functionality still contingent on Federal Reserve approval processes.
- Payall is among early adopters testing FedNow cross-border support for financial institutions serving global customers.
- FedNow settled nearly $275 billion across about five million payments during the second quarter alone.
Federal Reserve Financial Services announced the next phase on Sept. 23, saying participating financial institutions will be able to combine FedNow domestic settlement with established correspondent-banking arrangements that move the international portion of a payment.
The planned capability does not turn FedNow into an end-to-end global settlement network. FedNow would settle the U.S. portion between participating domestic institutions, while banks or other approved intermediaries would continue handling the overseas leg through the cross-border arrangements selected by each participant.
FedNow cross-border payments will keep a domestic settlement leg
The Federal Reserve has been preparing the legal structure for this model since April, when the Board proposed amendments to Regulation J allowing FedNow participants to use intermediaries other than Federal Reserve Banks in a funds transfer. Current rules have effectively limited FedNow to domestic transactions because only two U.S. banks, apart from a Reserve Bank, can participate in a transfer chain.
Under the proposal, a financial institution could use a correspondent bank or another permitted intermediary for the international portion and FedNow for the U.S. portion. The Federal Reserve said in its rulemaking that the model could support private-sector cross-border payment services without having the central bank operate the foreign leg itself.
FedNow currently operates 24 hours a day, seven days a week, including Federal Reserve holidays. Federal Reserve Financial Services states that each service business day runs continuously except for its technical cycle-date rollover process.
The Federal Reserve’s August review of U.S. cross-border payment work said FedNow had remained domestic since its July 2023 launch, while demand from banks for international use had increased as instant payments expanded. The same review noted that Fedwire migrated to ISO 20022 in July 2025, creating more common messaging across international payment chains.
Early adopters will test enhanced ISO 20022 messages
Federal Reserve Financial Services said a group of early adopters will test new FedNow message formats designed to carry information needed when the underlying payment involves a sender or recipient outside the U.S.
Payall Payment Systems is one of the named participants. President and CEO Gary Palmer said the company’s integration is intended to provide financial institutions with faster and more transparent processing for the U.S. portion of international payments while digitizing compliance and transaction-risk checks.
Payall described its role as helping banks “un-nest” payment chains, screen parties and automate risk controls. Those are company claims about its infrastructure and do not establish that every international payment using the future FedNow capability will process faster or at lower cost.
The company’s involvement follows earlier work with FedNow. Payall has previously completed FedNow testing and certification to support participating financial institutions, while its services cover cross-border payment orchestration and compliance systems.
Technical preparation began months before the latest announcement. Federal Reserve Financial Services said in April that enhanced ISO 20022 specifications were available through its MyStandards portal, allowing institutions active in international commerce to begin preparing system changes during 2026.
Once testing progresses, the Federal Reserve says other FedNow participants will be given the opportunity to adopt the enhanced messages. No general launch date has been published.
Regulation J approval remains required before full rollout
The most important unresolved step is regulatory approval. The Federal Reserve Board’s current rulemaking portal still lists docket R-1891 as a “Rulemaking Proposal.” The public comment period closed June 9, but the Board has not posted a final rule replacing the proposal as of Sept. 24.
The Sept. 23 FedNow announcement carries the same limitation. The functionality remains contingent on required amendments to Regulation J and corresponding changes to Operating Circular 8 receiving approval from the relevant Federal Reserve governing bodies.
Operating Circular 8, or OC 8, contains the operating terms for transfers through FedNow. Federal Reserve Financial Services currently lists the April 1, 2026 version as the effective circular, alongside operating procedures that took effect April 28.
Industry feedback on the Regulation J proposal raised compliance questions that the final framework may need to address. The American Bankers Association, for example, recommended clarifying how sanctions, anti-money laundering and fraud checks should work when a FedNow payment forms part of a cross-border chain. The group asked that banks be able to delay or reject payments where required to complete legally mandated screening.
Stripe’s comment on the proposal separately argued that the existing FedNow operating framework contained a residency restriction for certain ultimate customers and said operating-rule changes would be needed alongside the Regulation J amendment for the proposal to achieve its full cross-border purpose.
International payments will still rely on correspondent banks
The Federal Reserve’s design keeps existing correspondent banking infrastructure at the center of the foreign portion of each transaction.
A payment could begin abroad, move through correspondent arrangements and use FedNow once it reaches the U.S. banking system. An outbound transaction could reverse that sequence, with FedNow processing the domestic transfer before an intermediary handles the payment beyond the U.S.
The model resembles structures already used with Fedwire, according to Federal Reserve Financial Services. It does not create direct FedNow access for foreign banks that lack the required U.S. participation structure, nor does it establish a Federal Reserve foreign-exchange service.
Potential uses identified by the Federal Reserve include international payroll, corporate payments, property transactions, insurance disbursements and global treasury activity. The exact speed of the complete international transaction will still depend on the foreign leg, correspondent relationships, compliance reviews and local payment infrastructure.
The distinction is relevant as banks, stablecoin companies and blockchain networks compete to shorten international payment chains. Column connected stablecoin conversion with FedNow, SWIFT and other payment rails, allowing businesses to route different portions of payments through separate settlement systems.
SWIFT began testing a blockchain ledger with 17 global banks for round-the-clock cross-border payments using tokenized commercial-bank deposits. FedNow’s planned model remains based on conventional bank money settled through Federal Reserve accounts for its domestic portion.
FedNow volume has risen sharply before international expansion
FedNow enters the testing phase after rapid growth in domestic payment activity.
Federal Reserve Financial Services reported 4.997 million settled customer payments during the second quarter of 2026, up 83.2% from the first quarter. Their combined value reached $274.66 billion, compared with $271.25 billion during the previous three months.
Average daily volume rose from 30,317 payments in the first quarter to 54,921 in the second. Average payment size fell from $99,414 to $54,957 as transaction counts expanded more quickly than total dollar value.
For all of 2025, FedNow processed 8.41 million payments worth $853.4 billion. That represented 458.9% annual volume growth and more than 2,100% growth in settled value compared with 2024.
The network now spans more than 1,500 participating financial institutions. Federal Reserve Financial Services keeps separate current lists of live institutions, settlement agents and certified service providers, with its participant and provider files most recently updated Sept. 21.
In a separate domestic adoption move, Federal Reserve Financial Services announced a new discount program beginning Jan. 1, 2027, intended to encourage more institutions to activate and increase FedNow sending capabilities.
Cross-border testing is expected to proceed while the Regulation J process remains unfinished. Federal Reserve Financial Services has not published an exact date for general availability and says future progress updates will be provided to participants as testing, rule approval and Operating Circular changes advance.
As the Dow Jones Industrial Average and other stock indexes traded mixed during Tuesday’s session, Amazon (AMZN), Incyte (INCY), Scorpio Tankers (STNG) and XP (XP) were among the names to watch. With the S&P 500 and Nasdaq composite rallying sharply in recent sessions, traders who use The IBD Methodology from Investor’s Business Daily should be putting more capital to work…
Copyright ©2026 Investor’s Business Daily, LLC. All rights reserved. 87990cbe856818d5eddac44c7b1cdeb8
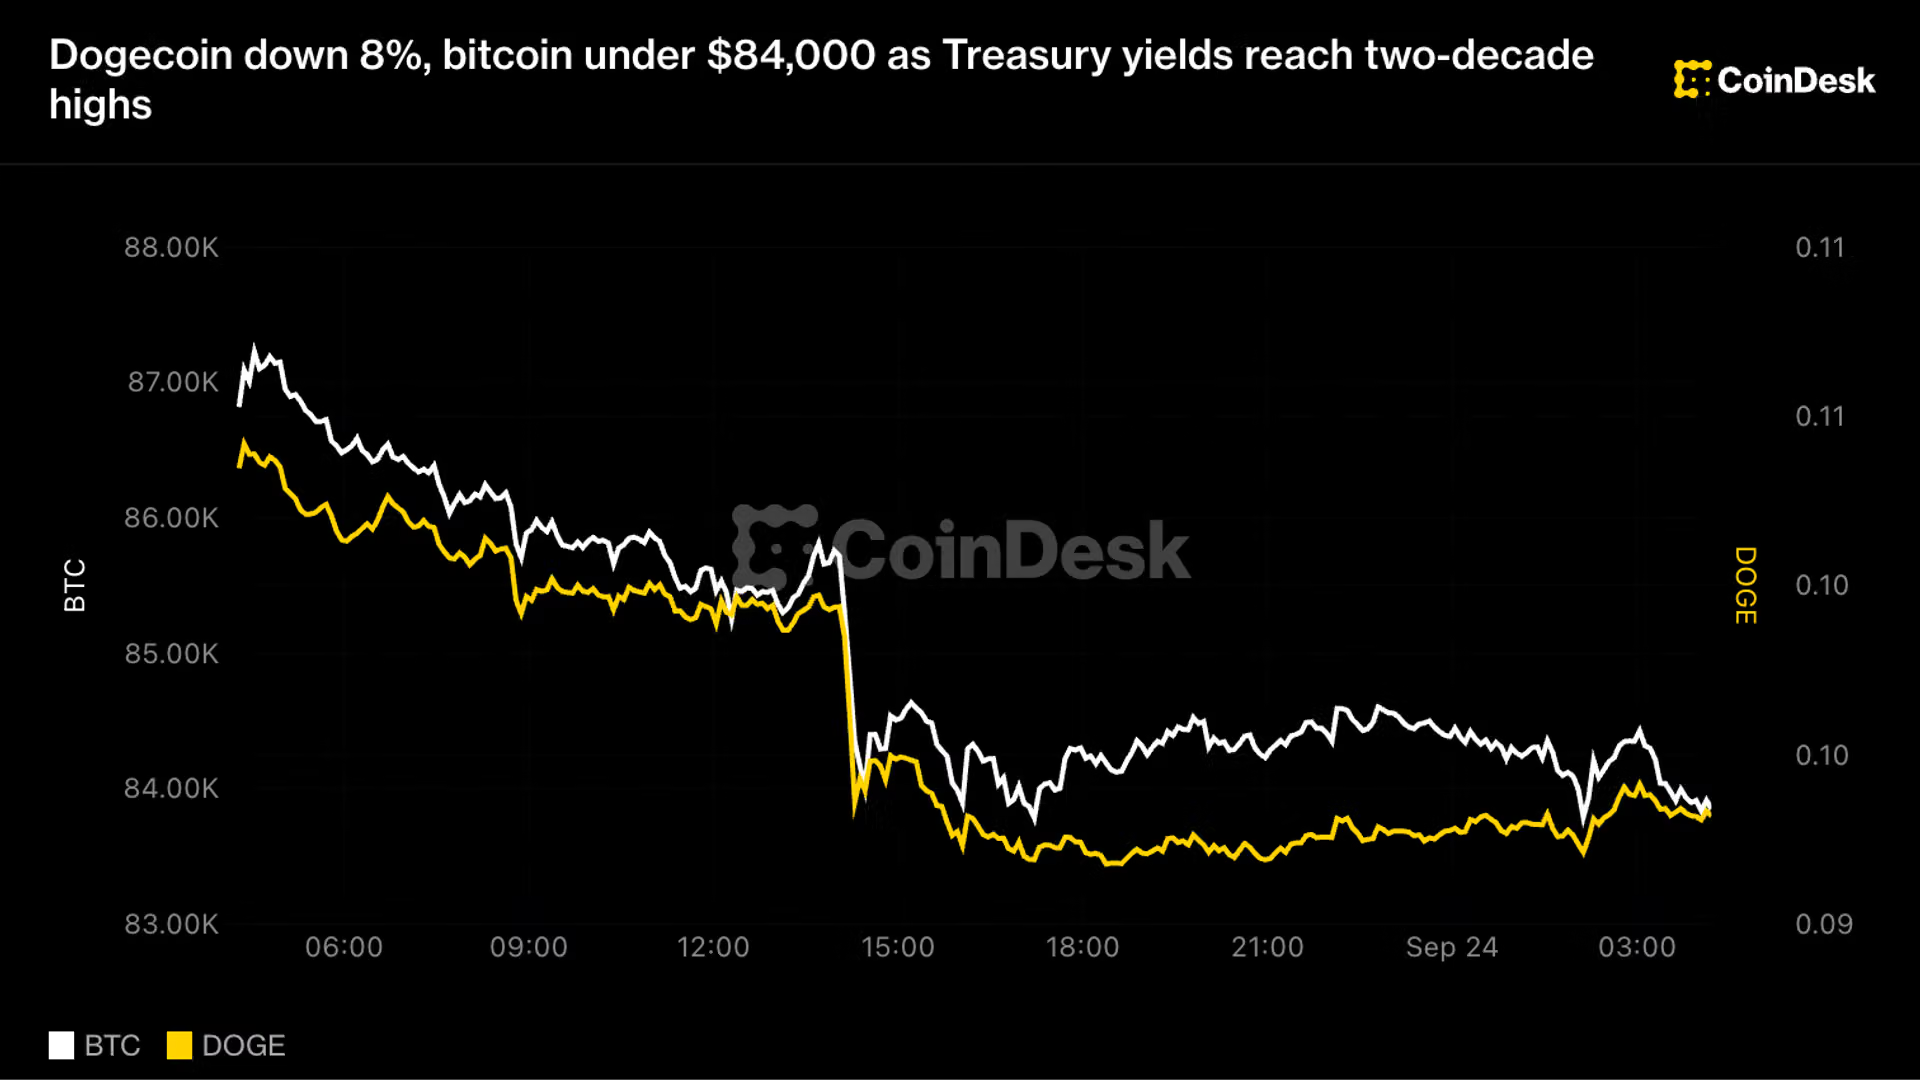
Bitcoin traded near $83,900 as of Thursday Asian morning hours, down more than 2% over 24 hours after touching nearly $87,300, CoinDesk data show. The 10-year U.S. Treasury yield closed Wednesday at 5.11%, up 15 basis points in a day, according to Treasury data.
DOGE took the worst of it, falling 7% to just above 9 cents. ZEC, XRP and HYPE each lost between 5% and 6%, while ether, SOL and BNB fell 2% to 3%. TRX held flat.
Brent crude turned first, climbing more than 4% to nearly $104 a barrel and ending a six-session slide that had been easing inflation worries. S&P Global’s flash survey of U.S. businesses followed, showing output growing at its fastest pace in more than five years, with the composite index at 58.4, its highest since July 2021.
The Treasury’s $70 billion sale of five-year notes landed later in the day and drew weak demand. It cleared at 5.033%, the highest auction yield since 2006 and about 3 basis points above where the notes traded just before the sale, meaning buyers demanded extra yield to take on the debt.
Crypto World
Hyperliquid (HYPE) targets $115 as tokenized asset trading gains momentum – CoinJournal

Key takeaways
- Hyperliquid’s HYPE token has gained 274% year-to-date, making it one of the strongest-performing large cryptocurrencies.
- CFTC Chairman Michael Selig said US regulators are preparing for tokenization, onchain finance, and continuous markets.
- Hyperliquid’s HIP-3 markets processed as much as $115 billion in monthly volume in June.
Hyperliquid (HYPE) has climbed 274% since the beginning of the year, outperforming other leading cryptocurrencies as demand for decentralized derivatives and tokenized real-world assets continues to grow.
The HYPE token recently approached the psychological $100 threshold, supported by expanding activity across Hyperliquid’s HIP-3 markets. Those markets allow builders to deploy permissionless perpetual futures, including contracts linked to real-world assets.
Comments from Commodity Futures Trading Commission Chairman Michael Selig have also strengthened expectations that tokenization and round-the-clock markets will become a larger part of the US financial system.
However, his remarks did not amount to regulatory approval for Hyperliquid or confirm that the platform will be allowed to serve US customers.
US regulators prepare for tokenized markets
Selig discussed the potential impact of tokenization during the 2026 Treasury Market Conference.
He said the CFTC is preparing financial markets for the arrival of large-scale tokenization, onchain finance and 24/7 trading. The chairman compared the shift with the transition from floor-based trading signals to electronic markets.
“Just as the transition from hand signals to electronic trading advanced our financial system, I believe tokenization can do the same for all asset classes,” Selig said.
He added that the regulator is committed to developing clear, principles-based rules intended to support innovation while protecting market integrity.
The comments reflect growing interest among US regulators in blockchain-based markets. The Securities and Exchange Commission recently introduced a temporary Innovation Exemption that allows eligible platforms to test certain tokenized securities products under defined conditions.
Tokenization converts ownership rights in assets such as stocks, bonds, or commodities into blockchain-based digital tokens. Supporters argue that the technology can provide faster settlement, fractional ownership, and continuous trading.
Regulatory support for tokenization could create opportunities for platforms offering real-world asset markets. Still, general statements supporting the technology do not guarantee market access for any specific decentralized protocol.
Hyperliquid would need to satisfy applicable derivatives, securities, and customer-protection requirements before directly offering regulated services in the United States.
HIP-3 volume reaches $115 Billion
HIP-3 has become an important source of growth for the Hyperliquid ecosystem. According to Hyperliquid Analytics, HIP-3 markets processed a recent monthly peak of approximately $115 billion in trading volume in June. Open interest continued rising afterward, reaching nearly $4 billion last month.
Open interest measures the value of outstanding derivatives positions that have not been closed. Its increase suggests traders are maintaining more exposure to HIP-3 markets rather than merely generating short-lived transaction volume.
The combination of high volume and rising open interest points to deeper participation. It may also create additional demand for HYPE because the token plays a central role in the broader Hyperliquid ecosystem.
CoinMarketCap data cited in the original analysis gives Hyperliquid an 18% share of the decentralized trading segment. That position makes it one of the largest venues competing for the expansion of onchain derivatives.
Real-world asset perpetuals have broadened the platform beyond cryptocurrency markets. Traders can use such contracts to gain price exposure without directly owning the referenced traditional asset.
These products can increase accessibility, but they also carry risks. Perpetual contracts use leverage, do not necessarily grant ownership rights, and may depend on external price feeds to track the underlying asset accurately.
Can HYPE reach $115?
HYPE recently moved close to the long-standing $100 price target, bringing a major psychological resistance level into focus.
Round-number thresholds often attract profit-taking because traders place sell orders around prominent levels. As a result, HYPE could experience a pullback after testing or briefly exceeding $100.
The former resistance area near $88 may provide the first meaningful support during such a correction. A successful retest would indicate that buyers remain willing to enter at higher levels and could establish a foundation for the next advance.
The medium-term upside target is approximately $115. The projection uses the length of HYPE’s previous rally to estimate the possible size of its next bullish leg.

A move from $100 to $115 would represent a further gain of 15%. Reaching that target would require the token to overcome profit-taking and maintain demand as its year-to-date increase approaches 300%.
If HYPE falls below $88, the immediate bullish structure would weaken, and the market could enter a longer consolidation. Rising open interest also introduces liquidation risk if highly leveraged traders crowd into long positions.
For now, HIP-3’s expanding volume, growing open interest, and broader momentum behind tokenized markets support the bullish outlook. The decisive near-term test is whether HYPE can convert $100 from resistance into support and extend its advance toward $115.
A coalition of US state lawmakers has asked the US Supreme Court to step into a jurisdictional fight involving Kalshi, a prediction markets platform, and New Jersey gaming regulators. In an amicus brief filed this week, the National Council of Legislators from Gaming States (NCLGS) argues that a ruling favoring Kalshi could severely restrict state authority over sports betting-like products offered through prediction markets.
The filing supports a petition by New Jersey’s Attorney General and gaming authorities seeking a writ of certiorari. According to the court documents, the petition—submitted on Sept. 2—asks the Supreme Court to consider whether state authorities or federal agencies have control over prediction market companies. The dispute stems from an appeal after a decision by the US Court of Appeals for the Third Circuit.
Key takeaways
- NCLGS filed an amicus brief urging the Supreme Court to uphold New Jersey’s position in the Kalshi case.
- The lawmakers warn that a ruling for Kalshi could “render[] states powerless” to regulate sports betting conducted via prediction markets.
- The brief frames gaming regulation as a state responsibility, while not directly settling the argument about federal CFTC jurisdiction for federally regulated event contracts.
- Kalshi has not filed an official response yet, though the company has previously indicated it should not be subject to a patchwork of state regulators.
NCLGS asks for Supreme Court intervention
On Tuesday, the NCLGS submitted its amicus curiae filing to the US Supreme Court. The group backed New Jersey’s request for the nation’s highest court to take up the case, which centers on how far state governments can regulate prediction market platforms that offer contracts tied to real-world events.
The lawmakers’ argument is grounded in the practical impact that they say could follow from a Supreme Court outcome. In their view, if Kalshi’s “self-described ‘sports betting’ activities” are treated as outside the scope of state oversight, other entities operating in heavily regulated gambling markets would likely seek the same legal classification.
In a passage included in the brief, NCLGS warned that businesses could change their offerings to obtain similar treatment, forcing states to reconsider the regulatory frameworks they currently use to govern this “vice activity.” The brief also emphasizes potential “substantial harm and confusion,” characterizing the prospect of reduced state power as disruptive to existing regulatory regimes.
What’s at stake: state power vs. federal oversight
At the heart of New Jersey’s petition is a jurisdictional question: whether regulation should be determined primarily by state gaming authorities or by federal regulators—particularly the Commodity Futures Trading Commission (CFTC). The Supreme Court has been asked to resolve an uncertainty that affects how prediction market products fit within existing legal categories.
NCLGS’s filing takes a broad position that “gaming-related matters” should remain with individual states. However, the brief does not fully engage with a competing line of reasoning raised in the dispute: that certain event contracts may be covered by the CFTC’s exclusive jurisdiction when traded on federally regulated markets.
That tension matters for market participants because it goes beyond the Kalshi case. If the legal boundaries are redrawn in a way that favors federal preemption, states could lose much of their ability to regulate not only prediction market platforms but also the surrounding ecosystem of operators that might attempt to structure offerings under the same umbrella.
Timeline and procedural posture
New Jersey’s petition for certiorari was filed on Sept. 2. It follows an appeal decision from the US Court of Appeals for the Third Circuit—an appellate step that typically signals a case has already raised substantial legal questions in lower courts.
In the Supreme Court, Kalshi has not yet issued an official response in the docket. The company has until Nov. 9 to file its brief setting out its position. In a statement provided after the initial filing, a Kalshi spokesperson told Cointelegraph that the company could not be “regulated by 50 different regulators,” pointing to concerns about inconsistent oversight across states.
While that comment does not resolve the legal question before the Supreme Court, it highlights the operational reality that accompanies the regulation of prediction markets: compliance regimes can vary significantly from jurisdiction to jurisdiction, and firms may argue that federal standards should govern where federal oversight is already implicated.
Why the case could shape the future of prediction markets
Prediction markets have grown into a broader sector that sits at the intersection of finance, sports, and consumer wagering. That makes jurisdictional clarity especially important. Without it, platforms may face uncertainty over licensing, product design, and whether their contracts are treated as gaming or as something else under federal commodities law.
The NCLGS brief suggests that states view the uncertainty as a direct threat to the ability to manage gambling-related conduct. If the Supreme Court were to adopt a reading that limits state authority, lawmakers argue states would need to rework their regulatory systems—and other operators could try to “amend their business and products” to capture whatever legal advantages come from that interpretation.
Conversely, the federal-jurisdiction argument reflected in the case poses a different concern: that event contracts traded through federally regulated structures may not be subject to separate state regulation, which could otherwise conflict with the CFTC’s regulatory framework.
For traders, developers, and investors watching the space, the outcome could determine how prediction market platforms plan for expansion. It may affect whether firms prioritize state-by-state compliance strategies or rely more heavily on federal frameworks when structuring products.
With the Supreme Court now considering whether to review the dispute, the key next step is Kalshi’s formal Supreme Court brief due by Nov. 9. Readers should watch closely for how the company frames the jurisdictional boundary—especially in relation to federal CFTC oversight—and whether the arguments on state preemption and federal exclusivity converge or remain sharply divided.
Crypto World
Think buying a car in cash is a flex? Why millions of boomers are quietly wasting thousands in savings

Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
Skipping auto financing completely seems like a “financial flex” that many Americans are happy to indulge in. Roughly 1 in 5 baby boomers or older, in fact, pay cash for their car purchases, according to a CDK Global survey (1) — and that ratio rises to nearly 5 out of 10 Gen Z car buyers.
Simply put, car loans seem to be less fashionable among younger Americans.
Top Picks
On paper, this might seem like a smart move. Auto loan rates for super-prime borrowers were roughly 4.55% and 6.30% for new and used cars, respectively, per Experian’s Q1 2026 State of the Automotive Finance Market report (2). So, looking at those rates, skipping the loan agreement might feel like an instant, guaranteed return on investment.
But the move could be costing you thousands of dollars over the long run. Here’s why.
Depreciation and opportunity costs
As of May 2026, a typical new car sold for roughly $49,220, according to Kelley Blue Book (3). Paying that in cash is a big up-front commitment. And unlike stocks or real estate, new cars rapidly shed value. In fact, a new car can be expected to lose roughly 30% of its value in the first two years alone, according to Kelley Blue Book (4). Beyond that point, it continues to depreciate at an annual pace of 8% to 12%.
In other words, you’re on track to lose tens of thousands of dollars in just the first few years of ownership. This depreciation cannot be fully avoided — but financing a portion of the purchase at 4% to 6% can offset some of the exposure.
Meanwhile, the cash you save by financing can potentially earn a higher return in other assets. The S&P 500, for instance, has delivered a roughly 10% annualized return since 1957, according to Fidelity (5).
This is the potential opportunity cost of paying for a car in cash instead of borrowing at a reasonable interest rate.
The case for financing
Paying cash for a car can feel like the financially savvy move. After all, you avoid interest charges and skip another monthly payment. But for boomers with a healthy nest egg, putting $50,000 or more into a depreciating vehicle all at once can also mean giving up access to cash that could be doing more useful work elsewhere.

Kent ‘commuter students’ are swapping residential halls for home

Quantum-Safe Bitcoin Compute Cost Falls 79% to Under $67
Paige DeSorbo on Past Experience With Domestic Violence




-

 Fashion5 days ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech3 days ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Crypto World5 days ago
Circle launches Arc Studio AI agent for building onchain apps
-

 Crypto World3 days ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-
 NewsBeat5 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World1 day ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-

 Crypto World5 days ago
Trading Bitcoin on Robinhood? Why 2% Spread Has Traders Worried
-

 Crypto World6 days ago
Mortgage and refinance interest rates today, Thursday, September 17, 2026
-

 Crypto World5 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Tech3 days ago
Google’s $899 Googlebook is a bet that you’ll buy a new laptop for Gemini
-

 Business3 days ago
Analog Devices (ADI) Bets $1.35 Billion on Chips that Let Machines Think for Themselves
-

 Crypto World3 days ago
Coinbase, Robinhood, Circle Seen as Tokenized-Stock Winners
-

 Crypto World5 days ago
World Money launches in 150+ countries with Stripe
-

 Tech6 days ago
GPT-6 Astra Reached the Nether in Minecraft, Lost Its Stash to a Creeper, and Farmed Potatoes for Hours
-
 Business1 day ago
Oil Price Today (September 23): Crude oil below $100 on hopes of US-Iran talks. What did Trump say?
-

 Crypto World6 days ago
Silver prices recover quickly, hitting weekly high today
-

 Tech4 days ago
Trump suggests rebranding AI with a new name, says he’s also creating an AI Force
-
 NewsBeat5 days ago
US was ‘on brink of war’ with China over false AI report of nukes moving in Middle East
-
 Crypto World5 days ago
CFTC sends crypto market structure rulemaking to White House
-

 Crypto World3 days ago
Bitcoin price holds above $81K as key catalysts line up
You must be logged in to post a comment Login