NYSE and Blockchain.com have agreed to explore distributing tokenized U.S. shares to a global crypto audience. The deal leaves the harder questions for the platform’s launch: whose record proves ownership, who decides who can trade, and how the new market stays tied to the shares beneath it.
Summary
NYSE and Blockchain.com signed a Sept. 23 memorandum covering access to tokenized shares and ETFs, subject to approvals.
Blockchain.com reported more than 44 million confirmed accounts, a distribution figure that is not a count of eligible investors.
The SEC’s separate Sept. 17 exemption caps qualifying venues at 75 Tier 1 and 250 Tier 2 stock symbols.
Third-party stocks under that SEC exemption require 30 days’ issuer notice and cannot trade if the issuer objects.
DTCC’s July 15 production trades used tokens representing securities held at DTC; its wider service targets October.
The New York Stock Exchange and Blockchain.com signed a memorandum of understanding on Sept. 23 to explore giving Blockchain.com customers access to tokenized U.S. stocks and exchange-traded funds. The route would run through NYSE’s planned digital alternative trading system, subject to required regulatory approvals. It is a plan for distribution, not a launch of stock trading to the company’s more than 44 million confirmed accounts.
NYSE is building a market that could operate at all hours and settle trades onchain. Blockchain.com brings a customer network already accustomed to digital assets. The announcement does not identify the final custody chain for each share, say which customers will qualify, or publish the terms under which a token could be converted back into a conventional holding. Those details decide what a buyer owns.
Advertisement
The answer will differ by product. A token can be the security recorded on a company’s shareholder file. It can represent an entitlement to a share held through an intermediary. It can instead be a contract that tracks a share’s price. All three can display a ticker on a phone. Only the first two can potentially carry the underlying shareholder interest, and even there the legal path to voting or dividends needs to be specified. The Securities and Exchange Commission drew those distinctions in a January staff statement on tokenized securities.
BREAKING: SEC grants temporary relief for venues trading tokenized U.S. stocks onchain.
The exemption allows eligible platforms to use permissioned automated market makers and liquidity pools for tokenized NMS stocks, creating a regulatory path for blockchain-based equity… pic.twitter.com/8fGYnNDZNT
The new agreement makes an old stock market question visible in a new format. A blockchain can record a transfer. It does not, on its own, determine which entity owes the holder a dividend, who can correct a mistaken transfer, or whose ledger a company treats as its shareholder record.
Advertisement
The Sept. 23 deal is a distribution agreement, not an open market
The parties called their agreement a memorandum of understanding. Their joint announcement says Blockchain.com’s user base would gain access to tokenized listed equities and ETFs through NYSE’s previously announced digital ATS after necessary approvals. The agreement covers a second business line: ICE Data Services plans to distribute Blockchain.com’s crypto data, while Blockchain.com plans to bring ICE and NYSE exchange data into its app.
That data arrangement could start informing users before they can buy any tokenized stock through the proposed venue. The announcement offers no launch date, approved securities list, country-by-country access rules or account-level eligibility figures. Forty-four million confirmed accounts measure an existing customer base. They do not measure approved brokerage accounts, funded investors, stock orders or future onchain volume.
The distinction matters because earlier ICE announcements already described several pieces of the same developing platform. In January, NYSE parent Intercontinental Exchange outlined a digital trading platform combining its Pillar matching engine with blockchain-based systems for custody and settlement. In March, NYSE named Securitize as its first prospective digital transfer agent able to mint blockchain-native securities for corporate and ETF issuers. The Sept. 23 deal adds a distributor and market data connection to that proposed structure. It does not say Blockchain.com becomes the transfer agent, the securities issuer or the operator of NYSE’s ATS.
NYSE Group President Lynn Martin told lawmakers on Sept. 2 that the planned platform would link digital equities directly to underlying shares and preserve voting rights, dividends and corporate actions. That is NYSE’s stated design. The signed customer terms, transfer records and regulatory approvals would show how it operates for a buyer. It is too early to treat the design statement as evidence that a particular token or distribution channel has gone live.
Advertisement
A crypto.news report on the new NYSE agreement covered the announcement and noted that the companies had not said their arrangement was approved under the SEC’s separate innovation exemption. The useful question now sits underneath the partnership: which existing institutions will keep authority over the shares when trading moves across a blockchain?
A wallet balance is not always the shareholder record
The SEC’s January staff taxonomy provides a route through the claims made for stock tokens. If an issuer or its agent places the security on a blockchain as part of its master shareholder file, moving the token can move the security in that official record. A company could maintain other records alongside the chain, including the holder’s legal name and address. The chain need not publish every detail of the register to be part of it.
There is a second issuer model. A share remains on an offchain master file, while an onchain token acts as an instruction that prompts the issuer or its agent to update that file. The token transfer and the legal ownership update are connected, but they are not literally the same database event. If the offchain update fails or is delayed, the reconciliation process matters more than the timestamp printed by a block explorer.
When a third party tokenizes a share held in custody, the token can represent a security entitlement instead of direct registration on the issuing company’s books. The company’s register may show a nominee or custodian. The customer has a legally defined interest through an intermediary chain, with the right to instruct or receive distributions according to that structure. Ordinary brokerage accounts already use forms of intermediated ownership. A blockchain token can change the transfer method without removing the intermediary.
Advertisement
The third-party synthetic model is different. A firm can issue its own security or contract that follows another company’s share price but gives the buyer no ownership claim against the company whose ticker is displayed. Dividends may be reflected through a contractual adjustment. Voting rights can be absent. The SEC says a buyer in that model may face the third party’s bankruptcy risk without holding the underlying company’s security.
These categories give a practical test for any token a consumer is shown. Find the document stating what the token represents. Identify who holds the underlying share, if anyone. Check whose records are legally authoritative when the token moves. Find the entity obliged to send a dividend or process a proxy vote. The ticker and the blockchain address cannot answer those questions alone.
The distinction has already caused friction. AMC Entertainment’s chief executive objected to an AMC-linked product offered offshore because, he said, the company had not issued or authorized it. Crypto.news examined the AMC and Robinhood dispute, including the difference between a tokenized exposure contract and a claim to the underlying share. That product should not be conflated with what NYSE has proposed. The episode shows why the phrase ‘tokenized AMC stock’ can conceal two different legal relationships.
Advertisement
DTC’s pilot keeps the original share inside the old system
The Depository Trust Company offers another way to locate control. On July 15, its parent DTCC announced production trades involving tokenized representations of assets held at DTC. More than 30 firms participated. The digital conversions ran on a private network and a public network. DTCC said the activity prepared for a tokenization service planned for October.
JUST IN: Ondo launches first tokenized stock representations on DTCC service
The initiative includes CRCLon and SPYon as digital twins of DTC-held securities pic.twitter.com/lx0QmlCYUu
Under that service, DTC participants can convert eligible DTC-held securities between conventional and tokenized forms and receive the digital representations in approved wallets. The underlying assets do not disappear from DTC because a token is issued. The token is a new representation within the securities custody and recordkeeping arrangement. DTC’s account records remain central to the structure.
Advertisement
That is a control choice. If DTC’s official books determine the participant’s interest, the blockchain is a transfer surface integrated with those books. Rules for wallet eligibility, reversals, corporate actions and reconciliation sit around it. The exact design can differ from an issuer keeping its master shareholder file directly onchain, even though both may advertise onchain settlement. A crypto.news report on a proposed regulated custody chain describes how the final customer can hold an entitlement while the official register still names a nominee.
NYSE’s eventual platform could connect to existing depository arrangements and to new digital transfer agents in different ways. Its January outline names multiple blockchains for custody and settlement. Its March Securitize agreement describes minting securities for issuers. The Sept. 23 Blockchain.com memorandum describes distribution. None of those announcements, taken alone, proves that every stock available on the eventual platform will use one identical registration and custody model.
There is a reason to keep the options open. A company that wants its agent to issue a token as the share itself has a different task from a broker seeking a transferable representation of stock already held at DTC. One starts at the corporate register. The other starts with an existing custodial position. Each can produce a tradable digital asset, but an investor’s claim passes through different hands.
The SEC’s statement on tokenized securities says the technology used to record the position does not by itself settle the legal characterization. For the buyer, that is the useful rule. Before asking how fast the token settles, ask where the share is.
Advertisement
The SEC’s new exemption governs a different kind of venue
On Sept. 17, the SEC issued release No. 34-106402, a five-year conditional exemption for certain Tokenized Securities Venues, or TSVs, using permissioned automated market makers and liquidity pools. It also grants conditional dealer-definition relief to specified liquidity providers. The 60-page SEC order is effective through Sept. 17, 2031, subject to modification.
The order does not say all tokenized securities venues are now exempt from exchange regulation. A TSV must meet the order’s particular conditions. It must verify that each eligible tokenized National Market System stock gives holders the same interest and the same dividend, voting and liquidation rights as a traditional share of the same class. It cannot host the primary issuance of the security under this exemption. Access must be permissioned, while the smart contracts used for the model must be public and auditable on a permissionless ledger. Crypto.news previously examined the holder-rights test in the order.
For a third-party tokenization unaffiliated with the company, the venue must give the company written notice and wait at least 30 calendar days before trading starts. A timely objection prevents trading that tokenized stock on that TSV. The requirement does not mean every stock-linked product everywhere needs the issuer’s consent. It is a condition of this specific exemption, which concerns securities carrying rights in the underlying share.
The NYSE agreement points to a planned digital ATS, a regulated venue category named by the partners. The SEC’s September order describes an exempt TSV model built around automated liquidity pools. No public statement in the Sept. 23 memorandum says the NYSE and Blockchain.com arrangement will rely on that order. Treating the exemption as the agreement’s approval would join two different records without evidence.
Advertisement
That separation is the feature’s central finding. The headlines describe a single arrival of stocks onchain. The documents describe at least three routes: an exchange-linked ATS under development, a conditional exemption for a particular pool-based venue, and DTC-backed tokenized entitlements. Each moves an equity claim through a different set of gatekeepers. A buyer needs the specific route, not the umbrella label.
The SEC order contains an unusually plain disclosure requirement. An exempt TSV cannot claim to be SEC-registered or imply the agency endorsed it. Its public notice must state that the venue is not registered as an exchange. Securities law bans on fraud and manipulation remain in force, but the venue does not acquire the full obligations of a registered exchange by being permitted to operate under an exemption. That is a meaningful distinction for a buyer weighing the safeguards attached to the trading venue.
The cap is 325 symbols, but volume is the tighter gate
The SEC divided eligible stocks under its TSV exemption into two tiers. A venue can trade no more than 75 Tier 1 symbols and 250 Tier 2 symbols. Add them and the maximum is 325 different symbols per TSV, subject to the rest of the order. The aggregate says nothing about how many stocks NYSE’s future ATS could list because NYSE has not said it will operate as an exempt TSV.
Each eligible stock also has a cap tied to trading in the conventional market. For Tier 1, a TSV’s average daily share volume cannot exceed 0.25% of the underlying stock’s average daily share volume in the prior month. For Tier 2, the limit is 2.5%. The figures in the SEC’s order are percentages of shares traded, not percentages of a company’s outstanding shares or market value.
Advertisement
Put both percentages against the same example of one million shares traded per day on the conventional market. A Tier 1 token would have room for 2,500 shares of average daily TSV volume. A Tier 2 token would have room for 25,000. The tenfold difference comes from the SEC’s tier treatment, not a forecast of investor demand. Real caps move with each stock’s prior-month volume, and affiliated TSVs must aggregate their activity under the order’s conditions.
If a venue exceeds a stock’s threshold after its first instance, it must stop trading that tokenized stock for three months. A venue may stop earlier to avoid breaching the cap. The rule makes the exemption suitable for a monitored opening of a market; it is not a promise that an exempt pool can absorb unlimited global orders around the clock. At a large enough scale, a successful venue could hit a ceiling built into its permission to operate.
The SEC explains why it imposed the limits. Automated market maker prices depend partly on the ratios of assets inside a pool. They may depart from prices on the conventional stock market. Keeping the pool small relative to the underlying share’s trading volume is intended to limit any disruption while the regulator observes the model. The price a buyer sees at 2 a.m. can be real for that pool while differing from the last conventional market price. The order itself treats that possibility as a market design problem.
Around-the-clock trading still needs an off switch
NYSE has advertised a digital platform designed for 24-hour trading. A clock without a closing bell does not mean a market without intervention. In its TSV order, the SEC requires the exempt venue to stop trading a tokenized stock at the same time the primary listing exchange halts or suspends trading in the underlying share. Reasons include a market-wide circuit breaker, material news or a listing problem. The venue must tell its users about the stoppage.
Advertisement
The off switch reveals who governs the token market in that model. The primary listing exchange’s decision travels into the onchain venue. A security does not become independent of its issuer, listing rules and national market protections when its trading record moves to a blockchain. How a separate ATS implements its own halt and reopening procedures will be set by the rules governing that venue; the TSV order should not be copied over to it without checking its filings.
Hours raise a second issue. The underlying company’s earnings release, dividend timetable and proxy process remain tied to corporate and securities law. An onchain pool can quote a price during a weekend, but its access to fresh price discovery, market makers and the ordinary exchange session will differ by hour. NYSE’s plan calls for continuous trading. It has not shown what spreads, depth or price protections a specific token will have on a Sunday.
Execution also depends on who supplies liquidity. The SEC allows certain firms supplying their own tokenized shares to an exempt pool to rely on conditional dealer relief. Their trading incentives and any arrangements with the venue must be disclosed under the order. The company whose shares are tokenized, the venue that controls access and the firm quoting against customers are separate actors. Calling the whole arrangement ‘decentralized’ would obscure those roles.
Issuer control and investor access pull in different directions
NYSE has a substantial case for its design. Martin’s September testimony says the company wants the token and conventional equity to be the same security in different forms, with the same rights. The SEC’s exemption separately requires equivalent rights and lets companies stop unaffiliated third-party tokens from trading under it. A holder may prefer a slower or more restricted path that can actually deliver a vote and a dividend over a token that offers only price exposure.
Advertisement
The counterargument is not simply that issuers should lose control. Distribution partners want investors in more countries to reach U.S. securities through an interface they already use. Blockchain.com executive Peter Smith made that access argument in the Sept. 23 announcement. An issuer notice requirement, permissioned access and volume limits could reduce the number of listings or buyers under the exempt TSV route. The question is which constraints protect ownership rights and which reflect a particular market design. Crypto.news covered the issuer veto dispute before the SEC’s order took effect.
There is evidence that the distinction matters commercially. NYSE’s agreement discusses its global distribution audience, while its prospective venue remains subject to approvals. DTCC’s tokenization service begins with DTC participants and approved wallets, a different customer entry point. The SEC’s TSV order permits a public chain for smart contracts but still requires the venue to approve participants. Public ledger access does not give every wallet holder permission to trade U.S. shares.
The SEC has heard objections from established market firms about granting special relief to venues outside the traditional exchange framework. Its order responds with disclosures, records, trading limits and a five-year term. Advocates of an open financial system may reasonably ask whether those limits narrow the audience too much. Issuers and investors may reasonably ask what happens to rights and market integrity if they are loosened. The records support both questions; they do not yet measure the cost of either choice in a live, large-scale U.S. stock token market.
One observation could challenge the concern that onchain trading merely adds gatekeepers. If a live platform shows verifiable ownership records, reliable transfers across approved venues, effective voting instructions and lower all-in costs for investors, the extra technology may simplify a chain of intermediaries. A second observation could challenge the access claim: accounts may be numerous while approved investors and actual trading stay small. Both tests require live disclosures, not launch language.
Advertisement
The launch question is who can correct a share transfer
At the point of a disputed transfer, the competing promises of tokenization become concrete. An investor may see a final blockchain transaction while a custodian, transfer agent or issuer’s master file shows a different owner. A mistaken corporate action may credit the wrong wallet. A key may be lost. A sanctioned account may need to be blocked. The documents defining which record controls and who can amend it decide how such cases are handled.
Issuer-sponsored stock can make the chain itself part of the master file. A custodial token can make the chain an entitlement record linked to shares held elsewhere. NYSE’s intended platform may support more than one settlement path, while DTCC is developing tokenized representations within its existing custody structure. The precise legal and technical link has to be documented for every product made available. It cannot be assumed from a partnership announcement.
The SEC’s TSV order requires a venue to explain its tokenization process, assess the legal status and technical integrity of each security, and disclose how it verified equivalent holder rights. It requires information about smart contracts, onchain and offchain functions, access rules, trading interruptions and affiliated trading. These notices would make it possible to test a venue against its claims once one operates under the order. They are not proof that NYSE’s proposed ATS will use the same design.
What happens next is checkable. NYSE must disclose the approvals and operating rules for its digital ATS before its proposed Blockchain.com distribution route can be assessed as a live market. The partners need to name the securities available, eligible jurisdictions and the legal interests delivered to users. DTCC’s planned October service launch will offer another view of how tokenized positions are kept in sync with shares held in conventional custody. The SEC will collect comments on its separate exemption as venues test it.
Advertisement
For a person buying a tokenized share, the shortest useful question remains the hardest one: if the wallet, venue and shareholder record disagree, whose entry wins?
What to watch
NYSE’s ATS filings: Look for the operating rules, approved trading hours and settlement design of the digital venue named in the Sept. 23 memorandum.
The first stock terms: Check whether a token is the share itself, a custodial entitlement, or a price-linked contract, and who handles votes and dividends.
Country-level eligibility: Compare Blockchain.com’s 44 million confirmed accounts with the jurisdictions and users actually permitted to trade U.S. securities.
Advertisement
DTC’s October launch: Watch for the planned wider tokenization service and details of conversion between conventional and tokenized positions.
Exempt TSV notices: Track issuer objections, eligible symbols, affiliated liquidity and any volume pauses under SEC release No. 34-106402.
FAQ
Can Blockchain.com users trade tokenized NYSE stocks now?
The Sept. 23 memorandum sets out a plan for access through a proposed NYSE digital ATS. The companies made that plan subject to necessary regulatory approvals and did not announce a launch date.
Does a stock token always make its buyer a shareholder?
No. An issuer-backed token may be the security, a custodial token may represent an interest in a held share, and a synthetic token may only track its price. The legal terms determine the buyer’s rights.
Advertisement
How many tokenized stocks does the SEC exemption allow?
An exempt TSV can trade up to 75 Tier 1 symbols and 250 Tier 2 symbols, for 325 in total, subject to other conditions. Those caps do not automatically apply to NYSE’s planned ATS.
Can a company block a third party from tokenizing its shares?
Under the SEC’s TSV exemption, the issuer has 30 calendar days after written notice to object to trading a third-party tokenized version of its stock on that venue. Other products and venues require separate legal analysis.
Will tokenized stocks include votes and dividends?
Stocks traded under the SEC’s TSV exemption must convey the same voting, dividend and liquidation rights as equivalent conventional shares. A synthetic product can follow a stock price without conveying those shareholder rights.
Does the blockchain replace DTCC or transfer agents?
It depends on the model. DTCC’s service represents assets held at DTC, while an issuer or its transfer agent may place the official shareholder file partly or wholly onchain. Neither design follows automatically from displaying a token in a wallet.
Advertisement
Can a tokenized stock keep trading during a halt in its underlying share?
An exempt TSV must stop trading the token concurrently with a halt or suspension on the primary listing exchange. A different venue’s controls must be read from its own rules.
What should an investor check before buying a tokenized share?
Identify the legal issuer, the location of the underlying share, the official ownership record, the route for voting and dividends, and the venue’s access and halt rules. This is educational analysis, not investment advice.
Disclaimer: This article is for information and educational purposes only and does not constitute financial or investment advice. Figures reflect regulatory filings and reporting available at the time of writing and change with each disclosure. Nothing here is a recommendation to buy, sell, or hold any security or asset. Always do your own research. Information is accurate as of September 24, 2025.
Securitize (SECZ) shares jumped more than 15% Friday, extending a sharp recovery just as the U.S. Securities and Exchange Commission (SEC) opened a new legal pathway for tokenized stock trading.
The company, which builds infrastructure for real-world asset (RWA) tokenization and serves as transfer agent for BlackRock’s tokenized BUIDL fund, a blockchain-based money market fund, traded at $16.53. Shares are up 77% over the past five trading days and 158% over the past month.
The Rule Behind the Rally
The exemption follows a stretch of rapid growth for tokenized real-world assets, from funds and private credit to equities represented onchain. On September 17, the SEC issued a five-year Innovation Exemption. It lets tokenized securities venues operate without registering as an exchange.
SECZ has risen over the past 5 days. Image Source: Trading View
The exemption also frees certain liquidity providers from registering as dealers. This applies when they supply tokenized stock to automated market maker (AMM) pools.
SEC Chair Paul Atkins framed the exemption as a temporary bridge.
Advertisement
“in a permissioned environment today while the commission considers the need for additional action to facilitate onchain trading”
The order builds on a January statement from the SEC and the Commodity Futures Trading Commission (CFTC). That statement classified tokenized securities and said tokenization changes a security’s form, not its legal status.
Securitize’s Bet on Onchain Equity
Securitize went public on the New York Stock Exchange (NYSE) in July through a merger with Cantor Equity Partners II. It tokenized $295 million of its own SECZ shares on Solana and Avalanche the same day. That made it the largest issuer-sponsored tokenized stock launch on record.
Securitize’s six-month, year-to-date, and one-year returns all sit near 50%. Its one-month gain alone is 158%, meaning almost the entire year’s advance happened in recent weeks.
Advertisement
Regulatory clarity removes one obstacle for tokenization platforms. However, it does not guarantee investor demand for a business still working toward consistent profitability. Therefore, whether this rally holds may depend on that answer.
The U.S. government has reportedly begun considering ways to support dollar-denominated stablecoin projects overseas as officials look to expand international dollar use and create another source of demand for U.S. Treasury securities.
Summary
Bloomberg reports U.S. officials are considering overseas stablecoin projects to strengthen global dollar use abroad.
Treasury, State and DFC could support private-sector ventures, according to people familiar with discussions internally.
Treasury says stablecoin providers already hold nearly $200 billion in bills and short-maturity government securities.
GENIUS Act reserve rules tie compliant stablecoin growth to cash, Treasuries and Treasury-backed instruments directly.
DFC now has expanded equity authority and a $205 billion investment cap for international projects.
Bloomberg reported on Sept. 23 that the Trump administration is discussing possible public-private stablecoin ventures involving agencies including the Treasury Department, State Department and U.S. International Development Finance Corporation. People familiar with the discussions said the initiative remains under consideration, and no specific country, company, funding amount or launch date has been disclosed.
The reported proposal has not yet appeared as a formal program in public releases from the three agencies. Existing official policy, however, already treats stablecoins as a potential channel for extending dollar use and increasing demand for short-dated U.S. government debt.
Advertisement
U.S. stablecoin policy already links tokens with Treasury demand
Treasury officials have publicly made the Treasury-demand argument for more than a year.
When President Donald Trump signed the GENIUS Act in July 2025, Treasury Secretary Scott Bessent said dollar stablecoins could strengthen the dollar’s role as the world’s reserve currency and create additional Treasury demand because eligible reserve assets include government securities. His statement described stablecoins as an internet-based dollar payment rail, though future market growth remains uncertain.
Treasury Deputy Secretary Francis Brooke gave a more current measure on Sept. 22. Speaking at the Treasury Market Conference, Brooke said stablecoin providers already own nearly $200 billion in Treasury bills and other securities close to maturity. He added that Treasury “may see stablecoin providers continue to grow and add to their holdings” as GENIUS Act rules are completed.
The $200 billion figure covers the stablecoin sector as a source of Treasury demand and does not represent new purchases tied to the Bloomberg-reported overseas initiative. No such government-backed foreign project has been announced.
Advertisement
A Treasury Borrowing Advisory Committee presentation from February had already examined the same mechanism. The analysis found that stablecoin growth could increase demand for short-term Treasury issuance when adoption comes from offshore users who were not previously holding dollars. The presentation estimated Tether and Circle had increased T-bill holdings by $70 billion since 2022 and said T-bills represented 53% of their assets using data through September 2025.
The committee presentation described a possible market outcome, not a commitment by Treasury to promote any particular issuer or stablecoin.
GENIUS Act sets the reserve structure behind the plan
The GENIUS Act provides the legal foundation that makes Treasury demand part of the stablecoin discussion.
Advertisement
Permitted payment stablecoin issuers must maintain reserves at least one-to-one against outstanding tokens. Eligible assets include U.S. dollars, certain bank deposits, short-term Treasury securities, qualifying repurchase agreements and money-market funds holding permitted reserve assets.
Treasury proposed another set of implementing rules on Aug. 17 defining when a payment stablecoin is considered issued, offered or sold in the United States. The department expects the statute’s main issuance restrictions to take effect Jan. 18, 2027 unless final regulations trigger an earlier date under the law.
The framework contains a separate route for foreign issuers. U.S. law permits certain overseas payment stablecoin companies to operate under comparable foreign supervisory systems once Treasury determines that the jurisdiction provides regulation comparable to the federal framework.
That foreign-issuer pathway is separate from Bloomberg’s report about the government potentially supporting stablecoin projects overseas. One concerns eligibility for U.S. distribution; the reported initiative concerns expanding dollar stablecoin use in foreign markets.
Implementation is still underway. Several federal regulators missed the law’s original one-year deadline for final rules, leaving proposals at different stages while the statutory framework moves toward activation. U.S. regulators missed key GENIUS Act rulemaking deadlines during 2026.
Tether and Circle show how stablecoin demand reaches Treasuries
The Treasury-demand mechanism can already be seen in reserve disclosures from the two largest dollar stablecoin issuers.
Tether reported roughly $141 billion in direct and indirect U.S. Treasury exposure at the end of March 2026. Its Q2 attestation later showed about $184.6 billion of USDT outstanding and $187.75 billion of total assets, with the company saying most reserves remained in government-backed instruments and short-term liquidity facilities.
Advertisement
The latest Q2 release did not give the same detailed Treasury total as Tether’s first-quarter disclosure, so the $141 billion figure should not be treated as its current September balance.
Circle presents a similar structure through USDC. Its second-quarter SEC filing showed that approximately 84% of USDC reserves were held in the Circle Reserve Fund as of June 30, with the rest primarily held as bank cash. The reserve fund invests in short-maturity U.S. government securities and related instruments.
Circle’s public data listed $74.6 billion of USDC in circulation as of Sept. 21. A Sept. 18 SEC filing for BlackRock’s Circle Reserve Fund confirmed that Circle entities hold shares in the fund as part of reserves associated with Circle-issued stablecoins. The filing noted that fund assets can rise or fall as stablecoins are minted and redeemed.
Those reserve structures help explain why U.S. policymakers frequently connect stablecoin adoption with Treasury demand. The scale of any additional demand from a government-backed overseas expansion would depend on adoption, issuer reserve composition and whether users are moving into dollar stablecoins from assets they already hold in dollars.
Advertisement
DFC could provide a public-private investment route
Bloomberg identified DFC as one agency that could participate if the administration moves forward with overseas stablecoin ventures.
DFC has legal tools that could support public-private investments, although it has not announced a stablecoin project tied to the reported discussions.
Congress expanded the agency’s authority in December 2025. DFC said its reauthorization raised its maximum investment exposure to $205 billion, created a $5 billion revolving equity fund and increased its permitted minority equity ownership to 40%. The law extended the agency through 2031 and expanded the countries where it can invest.
DFC describes itself as the U.S. government’s international investment arm and can use loans, equity, guarantees, insurance and investment funds alongside private companies. It has already created joint-venture structures in sectors including transport, critical minerals and infrastructure.
Advertisement
On Sept. 16, the agency approved more than $8 billion of new projects covering infrastructure, technology, energy and other strategic investments. The package included DFC’s largest digital infrastructure investment to date, involving African fiber and data-center operator WIOCC Group, but it did not contain a stablecoin initiative.
Any future stablecoin investment would still have to move through DFC’s project review process. The agency says transactions can require due diligence, internal approvals and congressional notification before commitment or closing.
Overseas adoption remains a reported proposal, not a launched program
The reported discussions fit with existing administration statements about using privately issued digital dollars to extend U.S. currency reach.
Treasury’s own research has described stablecoin providers as an emerging source of Treasury demand. Its February analysis said offshore growth among users who do not already hold dollar assets could produce incremental demand for short-term government securities.
Advertisement
The White House currently estimates the stablecoin market at around $300 billion in one September economic analysis. The same research notes that reserve composition determines how much stablecoin growth ultimately flows into Treasury securities instead of bank deposits or other eligible assets.
Foreign adoption would therefore not automatically translate dollar-for-dollar into new Treasury purchases. Some reserves may sit in cash, bank deposits, repo transactions or money-market funds, while users converting existing dollar assets into stablecoins may create less incremental dollar demand than users moving from another currency.
Treasury’s latest public remarks nevertheless show that officials are actively tracking stablecoin providers as Treasury investors. Brooke said on Sept. 22 that the department monitors structural demand from stablecoin companies alongside banks, money-market funds, foreign investors and the Federal Reserve.
The Bloomberg-reported initiative has no disclosed list of target countries, private-sector partners or funding commitments. Treasury, State and DFC have not publicly detailed a timetable for launching an overseas stablecoin partnership, while Treasury’s immediate regulatory work remains focused on completing GENIUS Act implementation ahead of the federal stablecoin regime’s expected start.
The FBI has brought investigators, foreign law-enforcement partners and crypto-security specialists together in San Antonio for its latest Virtual Asset Technical Exchange as U.S. cryptocurrency-related complaints exceed $11 billion in reported annual losses.
Summary
The FBI’s Virtual Asset Technical Exchange reportedly brought hundreds of investigators and crypto specialists together.
TRM Labs confirmed attendance, while Predicate said CEO Nikhil Raghuveera presented on stablecoin compliance topics.
FBI data shows cryptocurrency-linked complaints caused more than $11 billion in reported losses during 2025.
Chainalysis estimates sanctioned entities received $104 billion in crypto globally during 2025, rising 694% year-over-year.
TRM Labs attributes $643 million in first-half 2026 crypto thefts to North Korea-linked actors alone.
CoinDesk reported that the invitation-only gathering took place in September and represented the ninth year of a forum previously known as the Virtual Currency Symposium, based on accounts from three past attendees. The FBI declined to comment on the event, leaving much of its current public record to participant disclosures and company confirmations.
One independent public reference provides a more precise timetable. Recoveris, a digital-asset investigation and recovery company, listed the FBI Virtual Asset Technical Exchange in San Antonio for Sept. 2–3 on its 2026 conference schedule.
Advertisement
FBI crypto crime forum brings investigators and industry together
The September program reportedly drew several hundred participants, with private-sector vendors and partners capped at roughly 50, according to people familiar with the gathering who spoke to CoinDesk. Attendees ranged from senior FBI officials and frontline investigators to overseas law-enforcement officers, compliance specialists and blockchain-forensics companies.
TRM Labs confirmed its attendance to CoinDesk. Predicate confirmed that co-founder and CEO Nikhil Raghuveera presented at the event on stablecoin compliance and the GENIUS Act. Sources cited by the publication said Chainalysis, the Security Alliance and Treasury Department bureau FinCEN were represented, though Chainalysis and the FBI declined to confirm their participation publicly.
The gathering reportedly included presentations, panels, product demonstrations and discussions on tracing illicit funds. Topics ranged from terrorist financing and cartel activity to scams, human trafficking, child sexual abuse material, violent attacks against crypto holders and activity linked to North Korea.
One attendee described the meeting as a law-enforcement forum instead of an industry conference: “This is not a crypto event. It is a law enforcement event.”
Advertisement
The public record indicates the forum predates the FBI unit now responsible for coordinating much of the bureau’s digital-asset expertise. Token Recovery has previously discussed attending the gathering when it operated under the Virtual Currency Symposium name, while public participant material places the 2024 edition in Austin.
FBI crypto investigations now sit inside a dedicated unit
The FBI formally created its Virtual Assets Unit in 2022 after cryptocurrency had become part of investigations across ransomware, online fraud, child exploitation, terrorist financing and activity linked to hostile states.
The bureau announced that the unit became operational on Feb. 7, 2022. It described the VAU as a central hub combining staff from its criminal and cyber divisions to provide intelligence, technical support and operational assistance across FBI investigations.
Its responsibilities include blockchain analysis, virtual-asset seizure support and training for agents working cases in which funds move through digital currencies. The FBI later described the unit as a specialized team that centralizes cryptocurrency expertise while supporting field offices and partner agencies.
Advertisement
The scale of reported crime involving digital assets has increased since the unit began operating.
The FBI reported that its Internet Crime Complaint Center received 181,565 complaints involving cryptocurrency during 2025, with reported losses exceeding $11 billion. Total IC3 complaints reached 1,008,597, while cyber-enabled crimes produced nearly $21 billion in reported losses.
Investment fraud accounted for almost half of cyber-enabled scam losses. Cryptocurrency investment fraud alone generated more than $7.2 billion in reported losses during 2025, according to the bureau’s annual report. The figures come from complaints filed with IC3 and therefore do not represent a complete measurement of every crypto-related crime committed during the year.
North Korea and Drift featured in the threat discussions
North Korean cyber operations were among the subjects covered at the San Antonio gathering, according to CoinDesk’s sources. One presentation reportedly examined the April attack against Solana-based Drift Protocol.
Current blockchain-forensics data puts the Drift loss at approximately $285 million. TRM Labs reported that attackers spent weeks preparing the operation before draining assets on April 1 in roughly 12 minutes. The firm linked the campaign to North Korean actors based on its on-chain investigation, while its initial report said the specific subgroup attribution remained under investigation.
TRM said attackers socially engineered Drift Security Council signers into pre-signing transactions that later granted critical administrative permissions. The attacker then used a fabricated token called CarbonVote Token as manipulated collateral before withdrawing real assets from the protocol.
Drift itself said it was working with law enforcement and third-party forensic firms following the exploit while developing a recovery framework for affected users.
Advertisement
TRM’s subsequent first-half review attributed approximately $643 million, or roughly 66% of cryptocurrency stolen during the first six months of 2026, to North Korea-linked activity. Drift and the $292 million KelpDAO attack accounted for around $577 million combined.
Sanctions and state-linked activity deepen the enforcement workload
The forum’s reported focus on nation-state activity comes as blockchain analytics firms record a sharp increase in cryptocurrency moving through sanctioned entities.
Advertisement
Chainalysis estimated that sanctioned entities received roughly $104 billion in cryptocurrency during 2025, up 694% from the previous year. The firm’s preliminary data placed total value received by identified illicit cryptocurrency addresses at at least $154 billion, up 162% year over year.
Chainalysis cautions that its illicit-volume calculation is a lower-bound estimate because new addresses can be identified after transactions have already taken place. Legitimate cryptocurrency transaction volume remains far larger than the illicit activity identified by the company.
Russia, Iran and North Korea drove much of the state-related activity measured by the firm. Chainalysis attributed the increase to cryptocurrency being used not only for laundering but for cross-border trade, sanctions evasion, procurement and state-supported financial infrastructure.
More recent security data show the hack environment continuing to evolve after the San Antonio meeting. TRM Labs reported in September that 2026 had recorded roughly 333 crypto hacking incidents involving approximately $1.73 billion in stolen assets at the time of its analysis.
Advertisement
Security firms increasingly describe compromised credentials, administrative access and social engineering as central risks alongside smart-contract bugs. TRM’s first-half data counted 207 hacks, the largest six-month incident total in its records, while operational and infrastructure compromises generated a disproportionately large share of losses.
The FBI has not published a public agenda, attendee roster or post-event report for the September Virtual Asset Technical Exchange. Its official material continues to direct victims and companies toward IC3 and local field offices for reporting, while the Virtual Assets Unit provides blockchain analysis, seizure support and technical expertise for investigations across the bureau.
Bitget’s CEO Gracy Chen said preliminary investigation points to North Korean hackers behind the exchange’s reported $351.6 million security breach on Thursday. Speaking during a live Q&A on X shortly after the incident, Chen said investigators identified IP addresses they believe align with VPN services used by a DPRK-linked group.
Chen also said Bitget does not believe the breach involved an insider. She added that investigators were still mapping which parts of the exchange’s infrastructure were compromised and how the attackers gained access.
Key takeaways
Bitget CEO Gracy Chen said preliminary findings link the attack to IP addresses associated with VPN choices used by a DPRK group.
Chen said the exchange does not think the incident was carried out by an insider.
Bitget indicated hackers moved funds directly, rather than forging user withdrawal requests.
Withdrawals remained suspended at the time of publication, while Bitget works with partners on recovery efforts.
CEO points to VPN-linked IP addresses
In the Q&A, Chen told viewers that security investigators had flagged similarities between this incident and past DPRK-linked activity. She specifically referred to “some IP addresses” that match the VPN services reportedly used by the group.
Chen’s remarks described the attribution as preliminary, framed around technical indicators rather than a final, court-grade conclusion. Still, her comments reinforce a broader pattern the crypto industry has seen across multiple high-profile incidents, where infrastructure-level traces and operational “fingerprints” are used to connect attacks to specific threat actors.
Chen also said the investigation is ongoing, including efforts to determine which systems were affected and the precise entry point attackers used. That matters for users and market participants because identifying the initial access vector typically influences what remedial actions are prioritized—such as credential resets, segmentation changes, or controls around administrative interfaces.
Advertisement
How the breach reportedly worked
Beyond attribution, Chen offered details about the mechanics of the theft. She said hackers breached Bitget’s systems and transferred funds directly instead of forging user withdrawal instructions.
According to Chen, attackers “did not forge user withdrawal requests,” and she said they did not obtain Bitget’s private keys for any cold wallet or hot/warm wallet. Those distinctions are important because they suggest the compromise may not have relied on the same controls-behavior that some other incidents have shown, even if the ultimate outcome—unauthorized transfers—was severe.
Chen said investigators were still determining which systems were compromised. Until that scope is clear, it remains difficult for external observers to assess whether this was limited to particular services (for example, withdrawal-related infrastructure) or whether the breach potentially affected other operational components. For users, that uncertainty is reflected in the exchange’s decision at the time of publication to keep withdrawals suspended.
Bitget’s reported unauthorized transfers affected portions of its hot and warm wallet infrastructure, according to the exchange’s earlier disclosures. Withdrawals were still suspended at the time the CEO’s comments were reported.
Advertisement
Recovery efforts underway, but amounts not disclosed
During the Q&A, Chen said that some of the stolen funds had been recovered. She did not provide an amount, but said Bitget is working with blockchain foundations and other partners on recovery efforts.
Without a disclosed figure, observers will likely focus on whether recovery is partial or extensive—and, crucially, whether the attackers’ remaining funds are successfully identified and potentially blocked or reclaimed. The effectiveness of these efforts can vary significantly depending on factors such as how quickly assets are frozen, how the funds are routed through intermediaries, and whether counterparties and analytics teams are engaged promptly.
The broader market context also matters. If attribution strengthens—especially when aligned with prior patterns linked to DPRK-associated groups—it may influence how institutions assess counterparty risk and how exchanges harden controls related to suspicious network behavior and wallet-operation workflows.
DPRK links follow a pattern of major thefts
Chen’s comments come amid a long-running attribution debate in the crypto space, where North Korea-linked groups have frequently been referenced in connection with large-scale cyber thefts and laundering activity.
Advertisement
In earlier reporting, Cointelegraph described an estimated $2.02 billion in crypto theft attributed to North Korean actors in 2025, including a roughly $1.5 billionBybit hack that the FBI attributed to North Korea. Cointelegraph also linked those broader estimates to “South Korea gets rich from crypto” reporting that framed North Korean activity in the context of weapons-related incentives.
Chen’s statement that the “pattern looks very much like what the North Korean team did before” suggests Bitget is interpreting technical and behavioral indicators through that existing lens. However, the exchange’s own caveat—she described findings as preliminary and said investigators were still working out the full compromise path—means readers should expect updates as more information becomes available.
For investors and traders, the immediate concern is not only the size of the breach, but the robustness of the exchange’s controls and the completeness of remediation. For builders and security teams, the incident underscores a recurring theme: even when private keys remain uncompromised, attackers may still succeed by compromising operational systems that can authorize or execute transfers.
Next, the key developments to watch are Bitget’s investigation findings on exactly which systems were breached, whether the exchange expands its recovery estimate beyond “some” funds, and when—if at all—withdrawals resume after the affected hot/warm infrastructure is stabilized.
Advertisement
Risk & affiliate notice: Crypto assets are volatile and capital is at risk. This article may contain affiliate links. Read full disclosure
Japanese government bond yields have climbed to levels not seen in decades after the Bank of Japan raised interest rates last week, adding another source of pressure for cryptocurrencies already dealing with rising US Treasury yields and renewed Federal Reserve rate hike expectations.
Summary
Japan’s 10 year bond yield rose to 3.075%, its highest since 1996, after the BOJ raised its policy rate to 1.25%.
Higher Japanese borrowing costs could pressure yen funded trades, although there are no clear signs of a disorderly carry trade unwind.
Bitcoin already faces pressure from US Treasury yields above 5%, a stronger dollar and growing expectations for another Fed rate hike.
Japan’s rising domestic yields could encourage institutions to keep more capital at home as returns on JGBs become more competitive.
Reuters reported on Sept. 24 that Japan’s 10 year government bond yield rose 10 basis points to 3.075%, its highest level since August 1996, while the five year yield gained 10 basis points to a record 2.375%.
The move came during Japan’s first trading session since the BOJ raised its policy rate from 1% to 1.25% on Friday. Japanese markets had remained closed through Wednesday because of public holidays.
Advertisement
Selling spread across the yield curve, with the 20 year JGB yield climbing 8 basis points to 3.9% and the 30 year yield rising 6 basis points to 4.13%.
BOJ Governor Kazuo Ueda signaled that more rate hikes could follow, while concerns over domestic inflation have kept pressure on bonds. The yen weakened after the decision, prompting Japanese authorities to conduct rate checks in the currency market several hours later.
“Interest rates are being reviewed globally, and Japan’s interest rates are particularly low,” Masayuki Koguchi, executive chief fund manager at Mitsubishi UFJ Asset Management, told Reuters.
“So when the market finds a negative market cue, the selloff accelerates,” he added.
Japan bond yields could put yen funded trades under pressure
Rising Japanese rates do not provide a direct signal for Bitcoin or other cryptocurrencies, but traders have been watching Japan because of its role in funding global carry trades.
Advertisement
Investors have historically been able to borrow yen at low rates and move that money into assets offering higher returns. As Japanese borrowing costs rise, some of those positions can become less attractive.
Crypto.news previously reported that analysts were watching a possible squeeze on yen funded trades if the central bank continued raising rates.
Bitget Wallet chief marketing officer Jamie Elkaleh said at the time that the Fed remained the dominant central bank signal for Bitcoin because it sets the dollar liquidity and real yield backdrop, while the BOJ represented a risk that markets could be underestimating.
So far, however, Japan’s latest move has not produced clear signs of a disorderly carry trade unwind.
Advertisement
The yen weakened after the BOJ decision instead of strengthening. A classic carry trade reversal becomes more problematic when the Japanese currency rises because investors who borrowed yen can face higher costs when closing or servicing those positions.
The situation therefore differs from the yen carry trade episode of August 2024, when leveraged positions across global markets were reduced as Japanese monetary policy and currency moves forced investors to reassess cheap yen funding.
Higher domestic yields could still affect where Japanese institutions put their money.
Earlier in September, Japan’s 10 year bond yield briefly crossed 3%, prompting BlackRock to examine whether Japanese institutions could begin keeping more capital at home.
Advertisement
Yen hedged 10 year US Treasuries were yielding roughly 2% for Japanese investors at the time, compared with around 3% on Japanese government debt.
BlackRock used a hypothetical 5% reallocation of Japan’s roughly $1.1 trillion in US Treasury holdings to show that around $55 billion could move toward Japanese assets. The calculation was presented as a scenario, not a forecast of actual selling.
Fitch Ratings similarly said higher domestic yields could encourage Japanese institutions to retain more capital at home, though it did not predict a large liquidation of existing overseas bond holdings.
US rates remain the more immediate pressure on cryptocurrencies
Japan’s bond selloff comes as Bitcoin and the cryptocurrency market are already dealing with another rise in US borrowing costs.
Advertisement
US Treasury yields jumped Wednesday after stronger than expected business activity revived inflation concerns.
S&P Global’s flash US Composite PMI Output Index rose to 58.4 in September from 56, reaching its highest level since July 2021.
Fed funds futures subsequently priced a 66% probability of another rate hike in October, up from 53% earlier Wednesday, according to Reuters.
Pressure on Treasuries grew after a $70 billion auction of five year notes received weak demand. The benchmark 10 year Treasury yield rose nearly 14 basis points to 5.106%, its highest level since 2007 and its biggest one day move since April 2025.
Advertisement
Two year yields climbed more than 11 basis points to 4.891% after briefly touching 4.947%.
Bitcoin has already been feeling the pressure from bond yields during September as investors reassessed inflation, oil prices and the possibility of further Fed tightening.
The dollar reached its highest level in nearly two months on Wednesday as expectations for another Fed rate hike grew, according to Reuters.
Bitcoin has remained under pressure even when crypto specific demand provided some support. On Sept. 1, BTC traded around $77,500 as rate concerns weighed on the market despite positive spot Bitcoin ETF flows.
Advertisement
What could Japan’s bond selloff mean for Bitcoin?
The immediate risk from Japan depends largely on whether rising rates begin to affect yen funded positions or encourage more Japanese capital to remain in domestic markets.
Neither outcome has developed into a major crypto market event so far.
The yen’s weakness following the BOJ decision reduces the immediate case for a repeat of the rapid carry trade unwind seen in 2024. There is no clear evidence that Japanese investors are selling overseas assets on a scale that is directly affecting cryptocurrencies.
Institutional allocations depend on currency hedging costs, liquidity requirements, duration targets and regulatory requirements, making the effect of higher JGB yields difficult to isolate.
Advertisement
The US remains the more visible source of pressure for crypto markets, with Treasury yields above 5%, the dollar near a two month high and traders raising expectations for another Fed hike.
Japan adds a separate risk for traders to watch because borrowing costs are moving higher from historically low levels while domestic bond yields become more competitive with overseas assets.
Katsutoshi Inadome, senior strategist at Sumitomo Mitsui Trust Asset Management, told Reuters that local reports involving Economic Minister Minoru Kiuchi and reflationist economists had raised concerns that the BOJ could remain behind the curve in dealing with higher prices.
Prime Minister Sanae Takaichi’s first economic blueprint, released in July with an emphasis on economic growth, had previously unsettled Japanese bond markets and pushed yields higher. Selling in super long bonds eased earlier this month as traders began pricing a faster pace of BOJ rate hikes.
Copper futures touched a fresh record of $6.95 a pound on September 22. The move revived talk that the industrial metal could start closing the gap with gold as a store of value.
The rally caps a year in which the two metals have moved in opposite directions.
Copper Outpaces Gold’s Flat Year
This year’s nearly 20% climb puts copper on track for one of its strongest years on record. Over the past year the gain widens to more than 46%. The rally has been buoyed by Michael Burry’s copper bet and tightening supply.
Copper is up 22% in the last 6 months. Image Source: Trading View
Gold has barely moved by comparison, adding just 0.02% over the same stretch.
That gap hides gold’s wilder ride. The metal spiked above $5,600 an ounce in late January 2026 on safe-haven demand. It then crashed within days and has spent months clawing back toward flat.
Advertisement
Copper’s strength has different roots. Shanghai warehouse stocks of copper cathode fell to 43,900 tonnes, the lowest level since 2023. London Metal Exchange (LME) inventories available to the market fell to 133,725 tonnes.
Earlier in September, a stalled US tariff plan briefly knocked almost 8% off the price. The metal has since erased that pullback and gone on to set fresh records.
Not Quite Digital Gold Yet
CNN reported that tightening supply, tariff uncertainty and demand tied to artificial intelligence (AI) are pushing copper toward record levels.
Burry raised a related point last week, noting that new copper deposits take roughly 18 years to reach production. AI data centers, by contrast, add fresh demand within two to three years. That gap was central to his pick of a copper miner over AI stocks.
Advertisement
None of this makes copper a monetary metal like gold, which central banks still hold as a reserve asset. Gold’s global stock is worth close to $30 trillion, dwarfing copper’s much smaller market.
Still, the 2026 divergence suggests AI-driven industrial demand is reshaping which commodities investors treat as scarce.
Washington now holds the next catalyst. A long-delayed Commerce Department ruling on tariffs for refined copper imports is still pending. Traders expect the decision to move prices sharply once it lands.
For now, copper is winning the growth argument even if gold still wins on size.
Britain’s largest banks have completed what UK Finance described as the world’s first interbank transactions using tokenized deposits, testing blockchain based commercial bank money across mortgage and person to person payments.
Summary
Britain’s biggest banks have completed the first interbank transactions using tokenized deposits, covering mortgage and person to person payment use cases.
Lloyds, NatWest and Barclays completed two remortgage transactions, while a separate test involving HSBC simulated an online marketplace payment.
UK Finance plans to establish a company and governance framework for the project, with three digital bonds due to be issued and settled using tokenized deposits in early 2027.
According to UK Finance, Lloyds Banking Group, NatWest and Barclays carried out two remortgage transactions using tokenized deposits, while a separate group of three banks that included HSBC tested a person to person payment linked to a simulated online marketplace purchase.
The transactions form part of UK Finance’s Great British Tokenised Deposit initiative, which was launched to test whether digital representations of sterling bank deposits can move between different financial institutions. Previous bank projects had largely operated within individual systems, limiting their use for transactions involving customers at separate banks.
Advertisement
UK banks test tokenized deposits across separate institutions
Tokenized deposits represent conventional commercial bank deposits on a blockchain or another distributed ledger. The money remains a liability of the bank that issued it and retains the legal status and regulatory protections attached to an ordinary deposit.
Banks have spent years experimenting with blockchain systems for deposits, bonds, stocks and other financial assets, but separate infrastructure developed by individual institutions created problems when assets needed to move between them.
UK Finance designed the current pilot around interoperability between banks, with Barclays, HSBC, Lloyds Banking Group, NatWest, Nationwide and Santander participating. Quant, EY and Linklaters have supported the initiative.
The latest transactions put that model into practice through two different use cases.
Advertisement
For the online marketplace test, programmable deposits allowed money to remain reserved in a buyer’s bank account until the agreed conditions of the transaction were met. Funds were released to the seller only after confirmation that the goods had been received.
No physical goods changed hands because the transaction was simulated.
Jana Mackintosh, UK Finance’s managing director for Payments and Innovation, said the setup showed how programmable deposits could lower fraud risks in online transactions.
Advertisement
A similar mechanism was used for the two remortgage transactions. Funds were locked during the property process and released automatically when the transaction was completed.
The mortgage use case had been built into the project from its earlier stages, alongside person to person marketplace payments and settlement of digital assets. UK Finance previously said tokenized deposits could improve payment speed and fraud protection while retaining the protections associated with conventional bank deposits.
Tokenized deposits keep money inside the banking system
The tests come as UK regulators work through how different forms of digital money should operate alongside conventional bank deposits.
Tokenized deposits differ from stablecoins because they represent money held within the commercial banking system. Stablecoins are generally issued by private companies against reserves and create a separate claim on the issuer.
Advertisement
An April crypto.news report examining the difference between tokenized deposits and stablecoins noted that tokenized deposits retain their status as bank liabilities, with the regulatory and supervisory framework attached to commercial bank money.
The Bank of England has encouraged banks to experiment with tokenized deposits, while its framework for digital money leaves room for regulated stablecoins as another form of payment.
Deputy Governor Sarah Breeden said in May that the central bank wants a system in which traditional deposits, tokenized bank deposits, regulated stablecoins and potentially a retail central bank digital currency can operate alongside each other.
The Bank expects financial institutions to continue developing tokenized deposits and has been working on infrastructure that would allow the deposits to be used for payments between banks instead of remaining limited to customers of the same institution.
Advertisement
At the time, UK regulators were examining how tokenized securities, settlement systems and collateral could fit into regulated markets, with 16 firms preparing services through the Bank of England and Financial Conduct Authority Digital Securities Sandbox.
The central bank has since changed parts of its approach to stablecoins. Its final policy dropped proposed limits on individual stablecoin holdings and replaced them with an initial £40 billion issuance limit per systemic token.
Under the revised framework, issuers can hold up to 70% of reserves in short term government debt, while the remaining 30% must be held in non interest bearing Bank of England deposits. The central bank had previously proposed individual holding limits partly because officials were concerned that large flows from commercial bank deposits into stablecoins could affect bank funding and credit provision.
Digital bonds are next for the tokenized deposit project
UK Finance now plans to establish a company and develop a rulebook and governance framework as the Great British Tokenised Deposit project moves beyond its pilot phase.
Advertisement
Participating banks plan to issue three digital bonds in the first quarter of 2027 that can be traded and settled using tokenized deposits, Mackintosh told Reuters.
The planned transactions would add a securities settlement use case to the mortgage and person to person payments already tested.
A regulated digital cash leg has been one of the issues facing the UK’s tokenized bond market. The government is separately preparing its Digital Gilt Instrument, or DIGIT, with the first transaction expected by the end of the first quarter of 2027.
The first digital sovereign bond is expected to be issued through HSBC’s Orion distributed ledger platform inside the Bank of England and FCA Digital Securities Sandbox. The UK government has said further digital gilt sales could follow depending on the results of the first issuance.
Advertisement
A separate review of the DIGIT project identified onchain cash settlement as a remaining infrastructure issue, with regulators considering tokenized deposits, regulated stablecoins and central bank money as possible settlement assets.
Lloyds has already tested tokenized deposits in other settings. In August, the bank said it had completed three live transactions through the Bank for International Settlements led Project Agorá, covering sterling, euros and Swiss francs. One test linked foreign exchange conversion, payment and settlement into a single cross currency transaction flow.
Earlier in 2026, Lloyds issued tokenized sterling deposits on the Canton Network and used them to purchase a tokenized UK government bond from Archax, which the bank described as the first UK use of tokenized deposits on a public blockchain.
UK Finance says other markets are studying the project
Interest in the UK model has spread beyond the participating banks, according to Mackintosh.
Advertisement
“In the last 12 months, other jurisdictions have been speaking to us in earnest about what we’ve done, trying to understand how they can now catch up,” she said, citing discussions with counterparts in Europe.
Work on similar interbank infrastructure is underway in the United States. The Clearing House, a banking association and payments company, announced an interbank tokenized deposit project in June.
UK regulators are meanwhile developing rules and infrastructure for tokenized securities alongside the banking sector’s payment experiments. The Bank of England and FCA said in May that firms had asked for more certainty around prudential treatment, tokenized collateral and settlement instruments as financial institutions move distributed ledger projects toward live markets.
Visa has found that U.S. consumer interest in stablecoins rose from 36% to 56% when survey respondents were presented with hypothetical bank-level fraud protection and deposit insurance.
Summary
Visa found U.S. stablecoin adoption intent rose from 36% to 56% with hypothetical bank-level protections.
64% of Americans said provider trust matters more than the technology behind payment methods themselves.
56% of U.S. respondents had never heard of stablecoins before receiving definitions in Visa’s survey.
36% of Americans encountered international transfer scams, while 44% feared AI deepfakes impersonating family members.
Visa says stablecoin settlement volume has surpassed a $20 billion annualized rate as of September.
Visa’s Money Travels 2026 report, released on Sept. 23, examined how consumers view stablecoins, remittances and payment security. Morning Consult conducted the research for Visa between Feb. 24 and March 2, surveying 2,192 U.S. adults and 45,445 respondents across 20 markets globally.
The 56% figure describes stated willingness under a hypothetical set of protections, not current stablecoin use or an observed adoption rate. Visa said respondents received definitions of stablecoins before answering questions, while the survey relied on self-reported responses.
Advertisement
JUST IN: Visa says consumer safeguards could significantly boost stablecoin adoption in the U.S.
The share of Americans interested in using stablecoins rises from 36% to 56% when consumer protections are included, highlighting the role of safeguards in broader adoption. pic.twitter.com/yOJt47auH5
Visa stablecoin adoption intent rises with added protections
Without the hypothetical safeguards, 36% of U.S. respondents said they would consider using stablecoins. That figure increased to 45% when the payment method was offered through an existing financial provider, according to Visa. Adding bank-level fraud protection and deposit insurance pushed stated interest to 56%.
Advertisement
Provider identity ranked ahead of the technology itself for many respondents. Visa found that 64% of Americans said their trust in a payment method depended more on the company offering it. Traditional commercial banks received a 61% trust reading for digital currency services, while global payment networks received 60%.
Stablecoin familiarity remained limited despite growing use of the assets in payment infrastructure. More than half of U.S. respondents, or 56%, said they had never heard of stablecoins before the survey. Visa said some consumers who were familiar with them incorrectly assumed stablecoins move in price like Bitcoin.
Across all 20 markets, 69% of respondents said trust in a new method of moving money depended more on its provider than the underlying technology. The report found that 45% of U.S. respondents would accept a 24-hour transfer delay if it provided stronger fraud protection.
Deposit insurance in the Visa survey remains hypothetical
Visa specifically warned that the protection scenario should not be read as describing current U.S. stablecoin coverage. Its methodology note states that stablecoins are not presently covered by deposit insurance such as FDIC protection.
Advertisement
Federal regulators are still implementing the GENIUS Act framework. An FDIC proposal published in April would establish reserve, capital, redemption and risk-management requirements for payment stablecoin issuers under its supervision. The proposal says deposits held as stablecoin reserves would not receive pass-through insurance for payment stablecoin holders.
Federal Reserve staff made the distinction again in a Sept. 4 research note. The note said payment stablecoins must carry 1:1 reserve backing under the GENIUS Act, while the law does not make the stablecoins themselves federally insured deposits.
The regulatory framework is still moving through implementation. The OCC’s 2026 proposal covers reserve composition, liquidity, capital, redemption and oversight requirements, while a separate interagency proposal addresses customer identification requirements for permitted payment stablecoin issuers.
Remittance scams are shaping payment preferences
Security concerns extended beyond stablecoins in Visa’s findings. Some 36% of U.S. respondents said they had encountered scams connected to international money transfers, with fake messages, impersonation attempts and fraudulent investment schemes among the reported tactics.
Advertisement
Artificial intelligence appeared in part of that fraud exposure. Visa found that 24% of respondents had received AI-generated messages that appeared genuine, while 44% expressed concern about deepfakes being used to impersonate family members. Across all markets, one in four remittance users reported encountering fraud exposure.
Financial pressure around remittances remained visible in the same study. Roughly one in five senders said they reduced their own spending to support family members abroad. Vira Platonova, global head of Visa Direct, described remittances as “a lifeline” and said Visa’s research pointed to trust as a central concern for users.
Visa is expanding its stablecoin infrastructure
While the new report measures consumer attitudes, Visa has continued building stablecoin services for banks, fintech firms and payment companies. On Sept. 8, the company said more than 160 stablecoin-linked card programs operated on its network, with payment volume from those programs rising nearly 200% year over year.
Visa placed its annualized stablecoin settlement volume above $20 billion at that point, more than 15 times the level reported a year earlier. In related coverage, crypto.news reported on Visa’s expansion to 160 stablecoin-linked card programs and the accompanying settlement figures.
Advertisement
The current figure follows a rapid expansion earlier in 2026. Visa said in April that its settlement pilot had reached a $7 billion annualized run rate after adding Arc, Base, Canton, Polygon and Tempo, bringing supported blockchains to nine. Avalanche, Ethereum, Solana and Stellar were already part of the program. Visa stablecoin settlement pilot across nine blockchains had reached the $7 billion rate by late April.
July brought another product launch when Visa introduced the Visa Stablecoin Platform for financial institutions, fintechs and crypto businesses. The beta platform supports minting, redeeming, holding and transferring Open USD, alongside wallet infrastructure and approval controls.
Visa said the platform initially remains available to selected beta clients. Its current product page says Open USD access carries volume and geographic limits, while API access is still listed as coming later.
Join Our Telegram channel to stay up to date on breaking news coverage
The Commodity Futures Trading Commission is reviewing nearly one million ether perpetual futures trades on Kalshi that occurred in almost identical amounts and accounted for more than $5 billion in volume over the past month.
A $5,500 cluster
An analysis of public data reportedly found that more than one third of trades in the market in recent weeks were clustered around $5,500.
The cluster prompted allegations of wash trading, meaning trades without genuine economic purpose that can create a misleading impression of market activity. Kalshi denies the allegations. The company said hundreds of distinct traders participated and that the repeated trade sizes came from market makers keeping fixed resting orders in the book, which faster traders repeatedly hit. Kalshi said self trading is mechanically blocked and coordinated wash trading is prohibited and monitored.
Advertisement
The CFTC is weighing the activity before deciding whether to open an enforcement investigation, a person familiar with the matter reportedly said. The agency said it could not comment on whether an investigation is underway.
Jump Trading and Wintermute were reportedly among the firms involved in the rapid transactions. Jump said it trades for profit, uses self match prevention tools and does not coordinate its activity with other traders. Wintermute’s response was not known.
Stakes for Kalshi’s expansion
Kalshi launched crypto perpetual futures, contracts with no expiry date, in May and has since sought regulatory approval to offer similar contracts tied to individual US stocks. The review lands with that application pending, and with more than a third of the market’s recent trades tied to a single price level, it raises questions about how much of the young market’s volume is organic.
Join Our Telegram channel to stay up to date on breaking news coverage



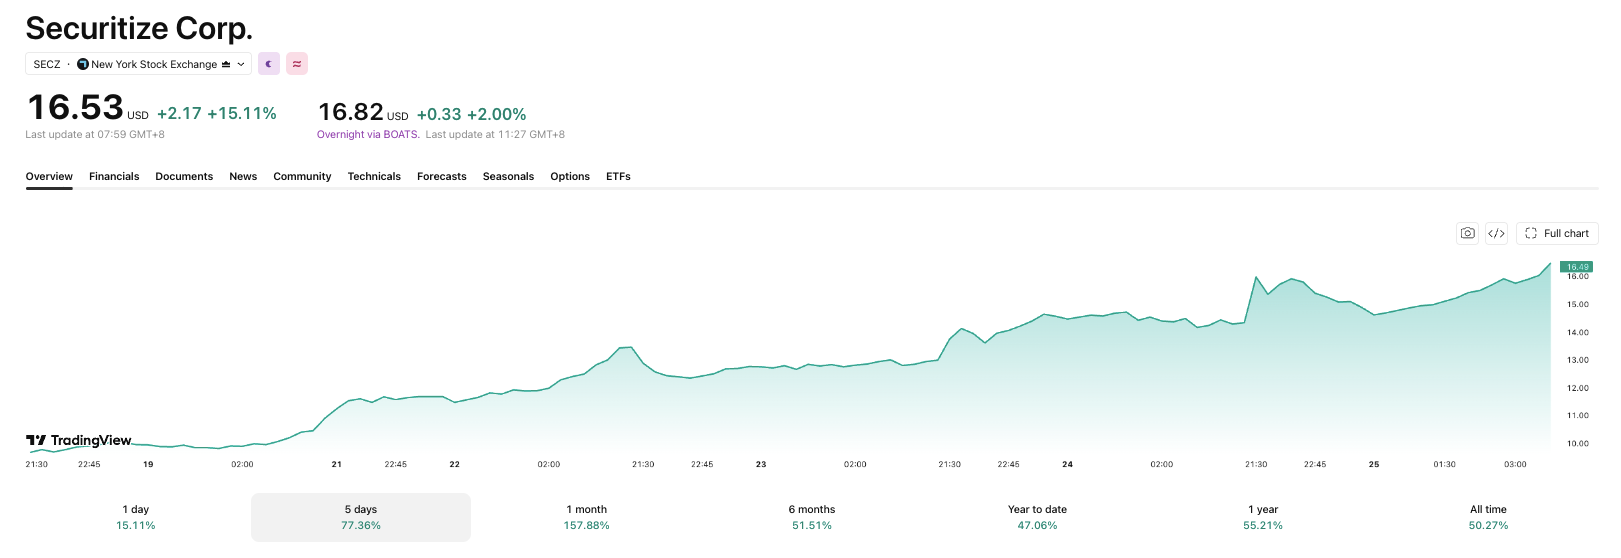

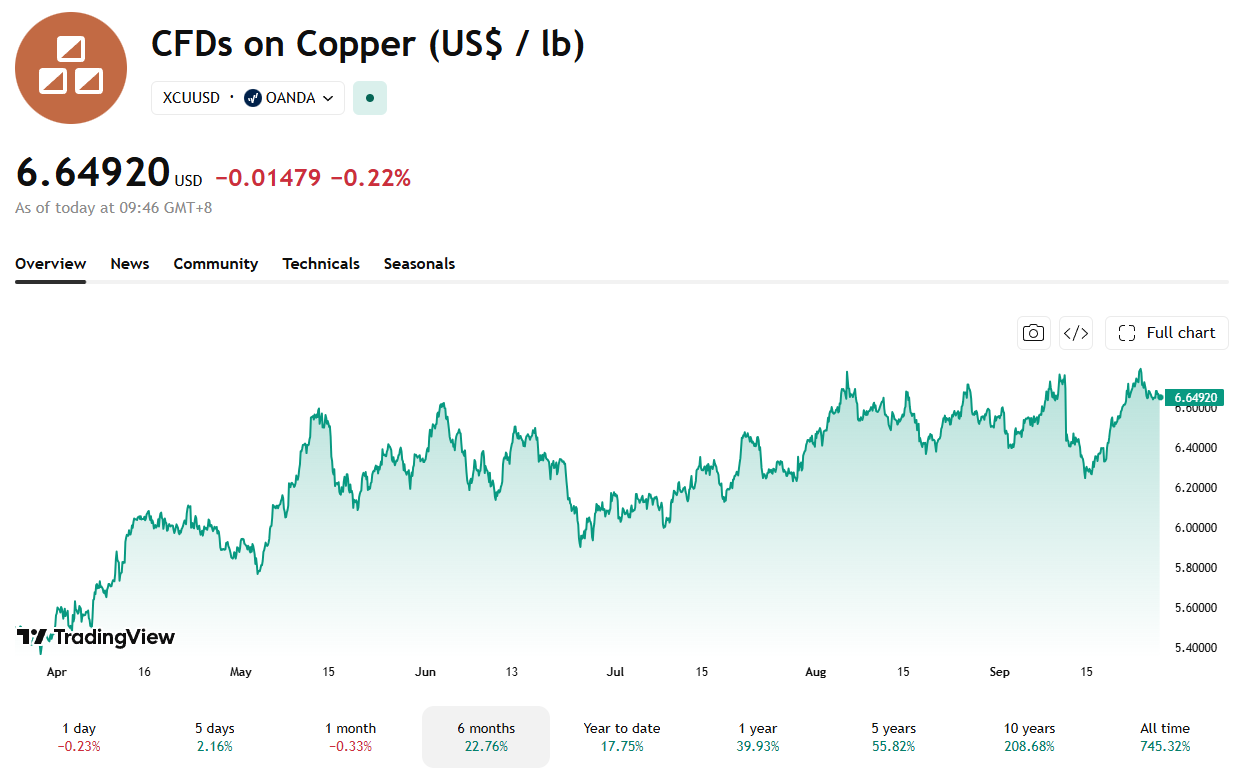













































You must be logged in to post a comment Login