
Crypto World
The 10x Bitcoin Rally Isn't Coming. CryptoQuant CEO Predicts a Calmer Cycle

CryptoQuant CEO Ki Young Ju has laid out what he expects from Bitcoin’s (BTC) current bull cycle. He also sees the following bear market as different from past ones.
Ju ties that outlook to a change in who owns Bitcoin and the kind of capital it now attracts. His outlook arrives with the asset trading near its highest level since January.
Ju Reads a Calmer Cycle in the On-Chain Data
Ju expects gains of 3 to 5 times this cycle rather than another 10x-plus parabolic rally. A gentler bear market would follow, in his view.
He credited Bitcoin’s larger market and growing institutional ownership. Retail hot money, he noted, powered past cycles and their 80% crashes.
Ju pointed to on-chain data as support. The Market Value to Realized Value (MVRV) ratio never fell below 1 this cycle.
“Some investors took losses, but holders as a whole never went underwater,” he said. “Even the PnL Index’s 365-day moving average, which typically lags at turning points, is forming a meaningful inflection right now.”
Ju also flagged a rise in realized cap and a halt in selling by OG whales. Futures whales, meanwhile, built large long positions near the bottom.
“None of this means Bitcoin has a ceiling. It means the trade-off has changed. Giving up the 10x parabola also means giving up the 80% crash, and that is exactly what invites patient, long-horizon capital instead of hot money,” he wrote.
Follow us on X to get the latest news as it happens
Doing the Math From Bitcoin’s June Low
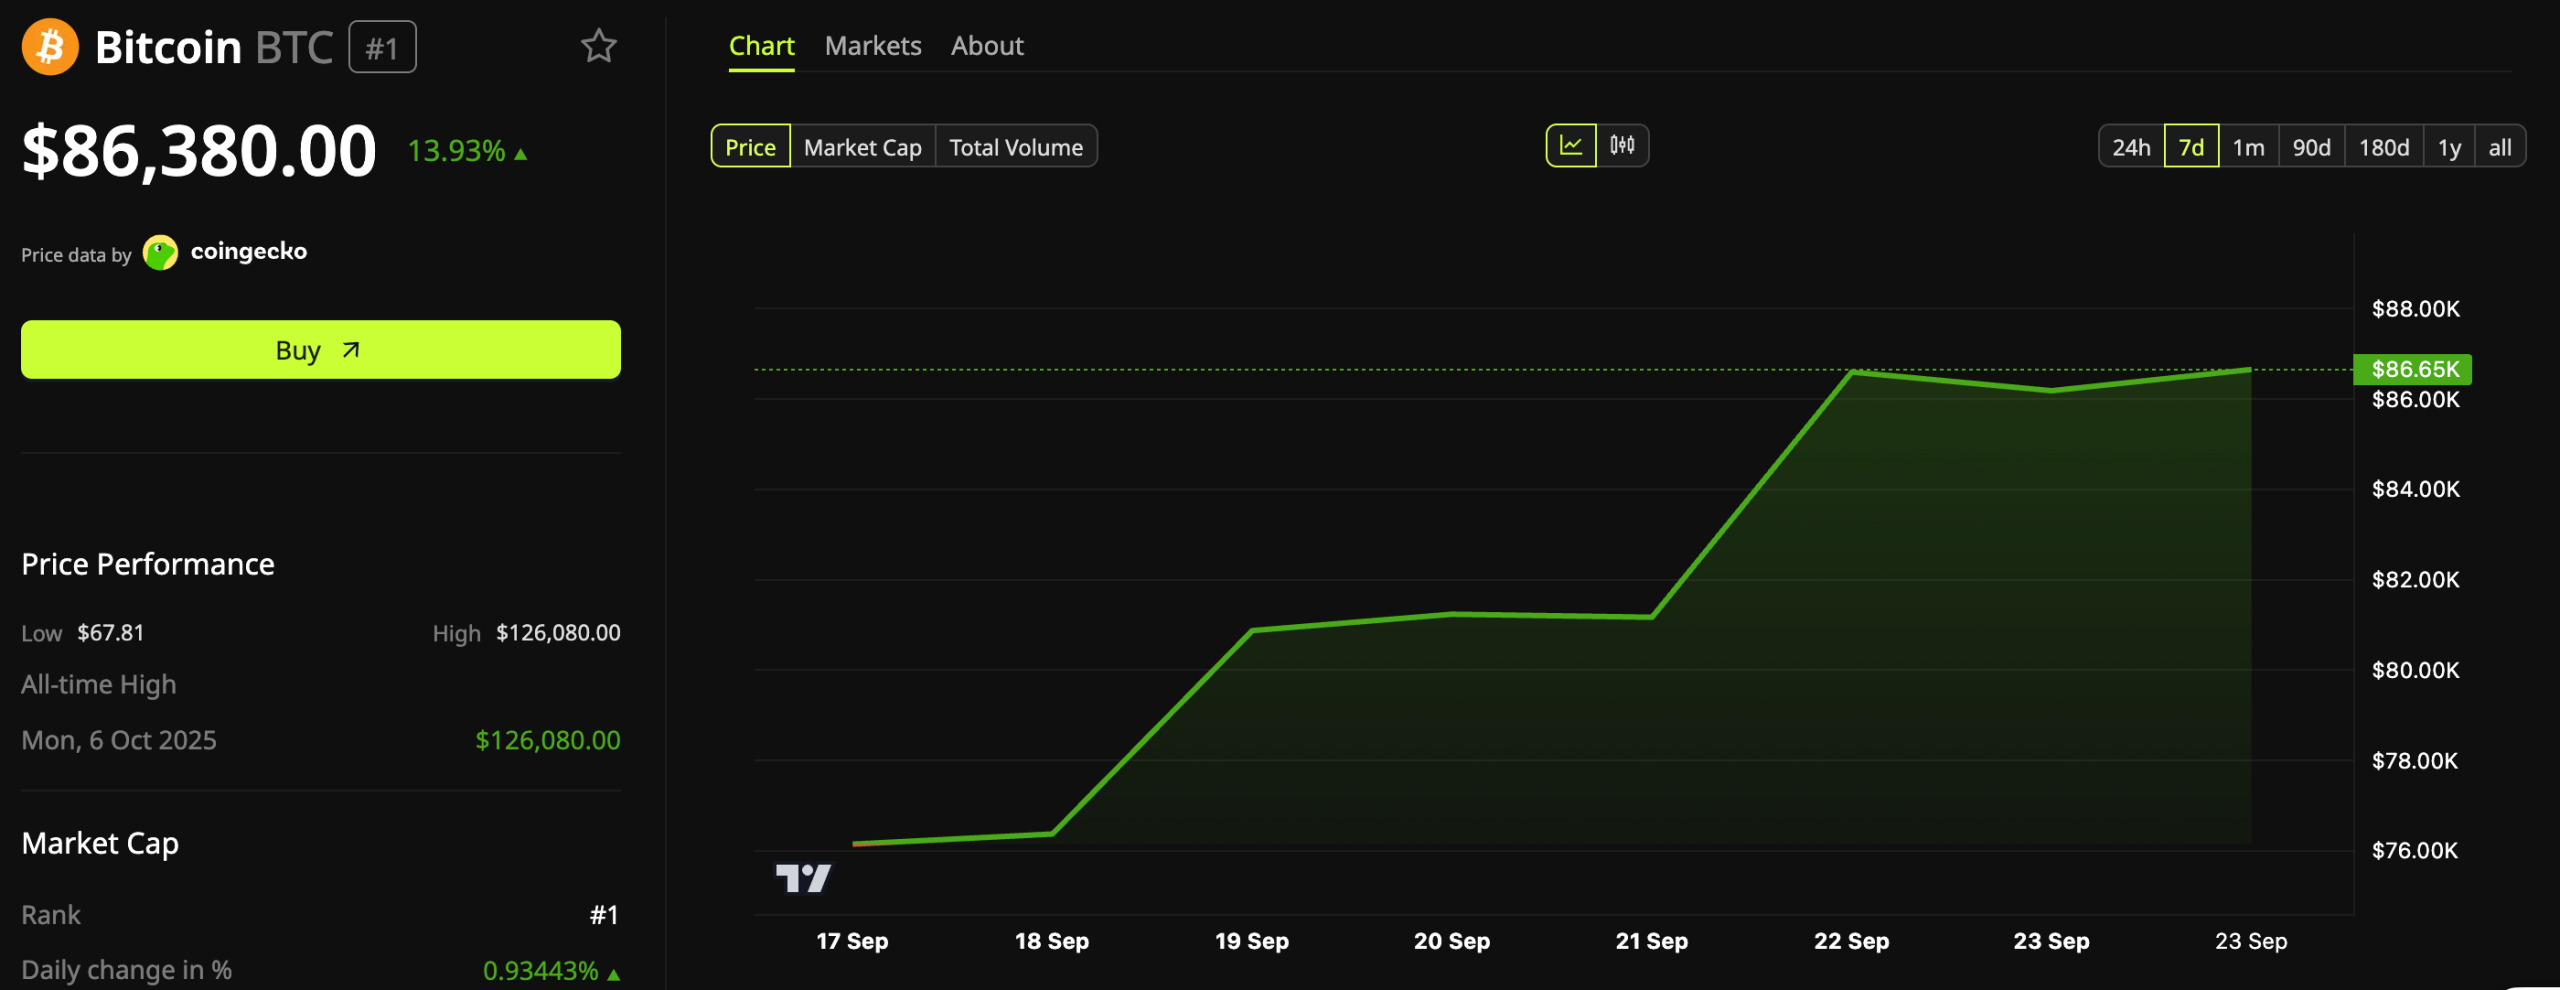
Bitcoin’s September rally gives his view some footing. The asset reached $87,395 on September 21, its highest price since late January.
That move followed Bitcoin’s first weekly close above the 50-week moving average since November 2025. Galaxy’s Alex Thorn has described reclaiming that average as strong confirmation of past bear market lows.
Before that close, Bitcoin had traded below the average for 45 straight weeks. The lowest point of that stretch came in late June, when the price fell to near $58,000.

Bitcoin has since gained about 49%, trading at $86,380 by press time. Measured from those lows, a 3x move would equal roughly $174,000, about 38% above the $126,080 record from October 6, 2025.
A 4x move would equal about $232,000, and a 5x move would equal about $290,000. Those levels fall between two calls from VanEck’s Matthew Sigel, who has forecast $100,000 for next year and $500,000 by 2029
Subscribe to our YouTube channel to watch leaders and journalists provide expert insights
The post The 10x Bitcoin Rally Isn't Coming. CryptoQuant CEO Predicts a Calmer Cycle appeared first on BeInCrypto.

The U.S. Commodity Futures Trading Commission has warned federally regulated prediction markets that contracts settling on what named people say, attend or do may face a presumption of being readily susceptible to manipulation.
Summary
- CFTC staff says mention markets carry heightened manipulation risks because outcomes depend on individual conduct.
- Designated contract markets must show strong safeguards before listing mention contracts under existing federal rules.
- Gabriel Perez disgorged $107,539 after using nonpublic presidential speech information to trade event contracts profitably.
- George Santos paid $35,000 after the CFTC found manipulative trading tied to his attendance contract.
- Kalshi still lists Trump speech markets, while mention contracts remain excluded from proposed margining plans.
The CFTC’s Division of Market Oversight issued the staff advisory on Sept. 22, covering contracts based on specific words or phrases, event attendance, public appearances and interactions between individuals. The guidance applies directly to designated contract markets and describes only limited circumstances in which such products may satisfy existing federal market-integrity requirements.
Unlike a new Commission rule, the advisory is informational and expressly says it creates no new legal obligations. Exchanges remain responsible for complying with the Commodity Exchange Act, including Core Principle 3, which requires designated contract markets to list only derivatives that are not readily susceptible to manipulation.
CFTC says mention markets can be presumed manipulable
Mention markets differ from contracts based on election results, economic releases or regulated sporting outcomes because settlement can depend on conduct controlled by one named person or a small group, according to the advisory. The regulator cited examples involving speeches, earnings calls, social-media posts, event appearances, photographs and personal interactions.
CFTC staff said a person controlling an outcome could deliberately trigger it, prevent it from occurring or know the result before traders outside that person’s circle. A podcast host, for example, could say a word tied to a contract payout, while people with access to scripts, prepared remarks or guest lists might possess material nonpublic information before settlement.
For that reason, the Division of Market Oversight said it may view mention markets as “presumptively readily susceptible to manipulation.” The phrase represents staff’s regulatory view under Core Principle 3 and does not mean every contract in the category is automatically prohibited.
A designated market could rebut that presumption in limited cases by showing that its contract design and controls sufficiently reduce manipulation risks. Staff identified independent verification and substantial public scrutiny as central considerations when evaluating those products.
The advisory asks exchanges to examine whether the person controlling settlement faces legal, professional, fiduciary, confidentiality, contractual or organizational duties that discourage deliberate interference. Exchanges should separately consider whether outside traders could influence the individual through payments, social pressure, inducements or other forms of interference.
Public settings receive particular attention. CFTC staff said formal events involving public figures may provide stronger independent verification, while conduct occurring privately or involving non-public people can be harder to verify and monitor. Even a public speech may present concerns when a contract turns on an incidental word with little connection to the substance of the event.
Recent cases show how insiders can control outcomes
The advisory follows two CFTC enforcement cases involving traders whose own access or conduct affected event-contract outcomes.
On Aug. 28, the regulator ordered former White House teleprompter operator Gabriel Perez to disgorge $107,539.02 and pay a $65,000 civil penalty after finding that he used advance access to President Donald Trump’s speeches to trade presidential mention contracts. Perez received a three-year trading ban.
Between December 2025 and February 2026, Perez had access to presidential speeches before delivery because of his federal employment, according to the CFTC order. The Commission found he misappropriated that information and generated more than $107,500 in trading profits. The CFTC credited KalshiEX for assisting the investigation.
As previously reported, the White House speech betting case involving advance access to Trump’s remarks ended with Perez agreeing to more than $172,000 in disgorgement and penalties after the regulator completed its investigation.
A separate July case involved former Rep. George Santos. The CFTC found that Santos traded contracts on whether he would attend the 2026 State of the Union while making public statements about his own attendance plans.
The regulator said contract prices moved in directions favorable to Santos after several of his social-media statements. Its settlement required him to disgorge $17,569.98, pay a $17,500 civil penalty and accept a three-year trading ban.
Kalshi later imposed its own permanent suspension. Kalshi’s lifetime ban on Santos over the State of the Union market followed the federal enforcement action and covered his access to the exchange directly or indirectly.
Kalshi keeps some mention markets live under tighter scrutiny
The new guidance does not amount to an industrywide ban on mention contracts.
As of Sept. 23, Kalshi still displayed markets tied to what Trump would say during United Nations meetings, including contracts covering terms such as AI, NATO and ceasefire. Another contract covering Trump’s United Nations General Assembly speech had recorded nearly $194,000 in volume in the available snapshot.
CFTC filing records show Kalshi previously self-certified amendments covering contracts asking whether a specific word would be said by a person, including a separate template tied to Trump. Those amendments were recorded as certified in June.
The Sept. 22 advisory means future Part 40 submissions involving such products are expected to contain more detailed, contract-specific manipulation analysis. Staff encouraged platforms to identify potential controllers and known insiders, then calibrate position limits, reporting requirements, recordkeeping and surveillance controls around those risks.
Staff said independent obligations placed on the person controlling an outcome do not replace the exchange’s own market-surveillance duties. Exchanges seeking to list a mention contract are expected to explain how their rules can detect manipulation, attempted manipulation and misuse of nonpublic information.
Kalshi has already reduced its exposure to some parts of the category. CFTC review of mention markets prompted Kalshi to pull sports mention contracts in August while political and corporate versions remained available.
A separate development arrived on the same day as the new CFTC advisory. Kalshi Klear requested approval for a margin framework covering selected event contracts, but mention and culture markets were excluded from the proposed eligible group, according to its filing coverage.
Prediction-market rulemaking remains unfinished
The mention-market advisory sits alongside a separate CFTC rulemaking process covering event contracts more generally.
The Commission proposed amendments to Regulation 40.11 in June that would create a formal process for assessing contracts involving areas Congress specifically identified, including gaming, terrorism, assassination, war and activities unlawful under federal or state law. The proposal includes a 90-day review process and contract-specific public-interest factors.
CFTC data said trading volume on federally registered prediction markets surpassed $25 billion during 2025. The regulator described event contracts as a growing part of derivatives markets while noting that the figure remained small beside the roughly $31 trillion notional value of the overall futures market it regulates.
The Commission has not published a final version of the June prediction-market proposal as of Sept. 23. Its current 2026 final-rule list does not show a completed Regulation 40.11 rulemaking, leaving the Sept. 22 staff advisory operating under existing Core Principle 3 and Part 40 requirements.
The federal framework is developing while courts consider separate disputes over state gambling authority. On Aug. 28, the Ninth Circuit ruled that Kalshi had not shown Nevada’s regulation of its sports event contracts was likely displaced by the Commodity Exchange Act, allowing Nevada’s sports-related enforcement to continue while other issues returned to the lower court.
As previously reported, the Ninth Circuit’s Nevada ruling on Kalshi’s sports prediction contracts did not invalidate the CFTC’s prediction-market rules or decide how every category of event contract must be treated.
Polymarket’s U.S. operation is part of the federally registered market structure through QCEX. CFTC records show amendments to the Polymarket U.S. rulebook were certified in April, while QCEX has continued filing event products with the regulator during 2026.
For mention markets specifically, the next compliance step falls on designated contract markets when they submit new products or amendments under Part 40. The Sept. 22 advisory says staff expects each filing to provide a detailed evaluation of the manipulation factors and describe the controls intended to address them.
Apple’s App Store has once again been used as a delivery channel for a crypto theft operation. According to an investigation by blockchain security firm SlowMist, a malicious iOS app named FomoPeek was linked to nearly $580,000 in stolen crypto, with the attackers using kernel-level exploits to break out of Apple’s sandbox and reach sensitive wallet data.
SlowMist says the compromise targeted specific app versions, while a later release removed the malicious components. The incident highlights a persistent risk for mobile users: even when an app is distributed through official stores, flaws at the operating-system level can enable attackers to access data that should remain protected.
Key takeaways
- SlowMist links FomoPeek to about 579,984 USDT stolen after the app contained kernel exploits capable of escaping iOS sandbox protections.
- Only certain versions were affected: SlowMist points to releases on Sept. 9 and Sept. 12, with version 1.3 released on Sept. 17 removing the malicious modules.
- The malicious code targeted protected data: researchers report access to iOS Keychain data and files belonging to other apps.
- Onchain tracing shows cross-network movement: funds were routed through multiple blockchains and later consolidated through several addresses and services.
What SlowMist found inside the FomoPeek app
In its threat intelligence analysis, SlowMist said FomoPeek included multiple malicious modules designed to exploit iOS vulnerabilities. The goal, according to the report, was to gain elevated privileges and escape the constraints of Apple’s application sandbox.
Once the app achieved this elevated access, SlowMist reports it could reach Keychain data as well as files belonging to other apps. For users, that matters because Keychain entries often store credentials and other sensitive material used by wallets and related services—data that normally remains isolated from third-party applications.
SlowMist said the malicious components were part of the app releases issued on Sept. 9 and Sept. 12. The firm added that version 1.3, released on Sept. 17, removed the harmful elements.
Release timing and the window of exposure
SlowMist’s timeline indicates the attack depended on users installing (or keeping) the affected FomoPeek versions rather than a permanently compromised build. The firm said its investigation began after it received reports from users who experienced asset theft and confirmed that at least some of those users had installed one of the vulnerable releases.
This distinction is important for practical risk management. Even if a malicious app is later patched or sanitized, the harm can already be done during the earlier window—especially when the app can exploit kernel weaknesses and access protected data. For mobile users and wallet operators, the lesson is that version-by-version scrutiny can be just as critical as store-level distribution.
Exploit framework details and affected iOS ranges
SlowMist said the exploit framework it observed featured eight attack methods. The report describes intended support for a broad set of iOS versions, including 12.0 to 18.7.2 and 26.0 to 26.1.
The breadth of those ranges underscores why kernel exploitation is so difficult to contain. When an attacker can target multiple configurations, the same malicious app can potentially work across a larger portion of the installed base, increasing the likelihood of successful compromise.
Onchain analysis: nearly $580,000 in stolen crypto
Beyond the app-side findings, SlowMist analyzed the associated blockchain activity. The firm identified a primary hacker address tied to the incident that received approximately 579,984 USDT.
According to SlowMist, the address became active on Sept. 15—after the initial affected releases—suggesting the theft activity followed the period during which users could have installed vulnerable versions. SlowMist further said the stolen funds were spread across multiple blockchain networks before being consolidated through additional addresses and services.
SlowMist reported that portions of the funds were routed toward services including FixedFloat, KuCoin, and cce.cash, while other portions were dispersed through additional addresses that the firm continued to trace.
For investors, traders, and compliance teams, this pattern is typical of efforts to obscure fund trails: attackers frequently move value across networks, fragment flows through intermediaries, and then consolidate proceeds in ways that make attribution harder.
Attempts to get responses
Cointelegraph said it reached out to Apple, SlowMist, and OKX for comment. The outlet reported that it did not receive a response before publication.
SlowMist’s investigation was conducted together with the OKX security team, according to the report. The collaboration points to how incident response in crypto increasingly blends onchain forensics with software security research—especially when attacks originate in mainstream distribution channels like app stores.
Users who installed FomoPeek on iOS versions before the reported removal on Sept. 17 should consider reviewing wallet permissions and checking whether any accounts show unauthorized activity. The key uncertainty going forward is whether additional malicious versions or related packages exist outside the specific releases SlowMist identified—and whether Apple or the broader mobile security community will accelerate defenses against kernel-exploit delivery through app-store software.
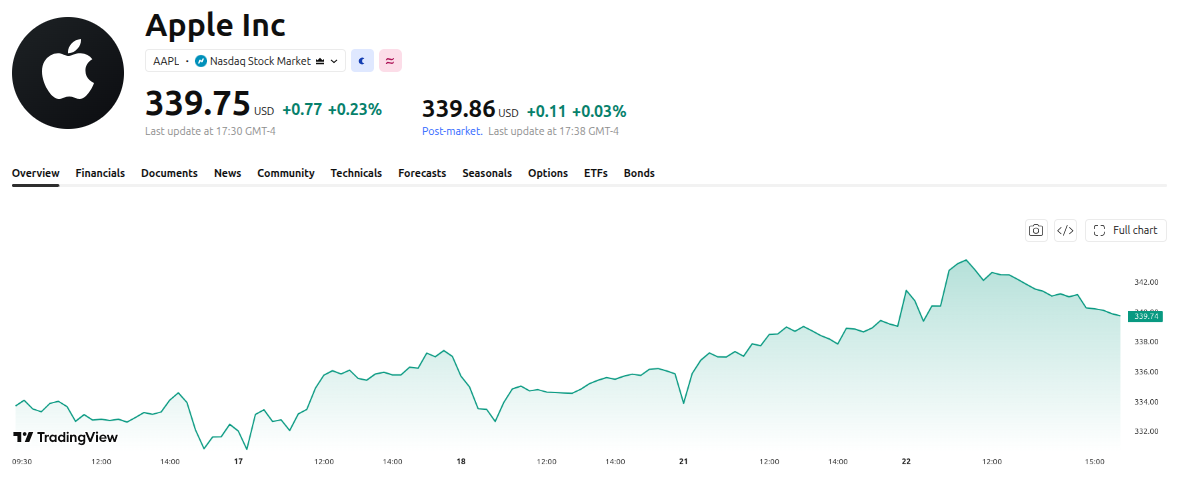
Apple shares reached a fresh all-time high on September 21, 2026. The stock touched nearly $345 intraday before settling near $339.
NVIDIA, meanwhile, trades near record levels, even as its forward valuation multiple has compressed sharply from earlier this year.
What’s Really Driving Apple’s Record-Breaking Rally
A forward price-to-earnings ratio measures a stock’s current price against analysts’ projected future earnings. It offers a snapshot of how expensive a company looks relative to expected growth. That distinction matters for understanding what’s happening between these two tech giants right now.
Apple’s rally reflects renewed confidence in its hardware and services ecosystem. Strong demand for the latest iPhone models, particularly the iPhone 18 Pro and the upcoming foldable iPhone Duo, has extended delivery times and lifted upgrade-cycle expectations.

Improvements to on-device Siri AI and a smooth CEO transition have further reassured investors that Apple can monetize artificial intelligence without the massive capital spending required by hyperscalers.
The stock has climbed more than 36% over the trailing 12 months, according to TradingView data, pushing its market cap above $5 trillion.
Services revenue and high-margin software continue expanding Apple’s cash-generation machine, giving investors a steadier growth story than many of its AI-exposed peers currently offer.
Follow us on X to get the latest news as it happens.
Why Has NVIDIA’s Valuation Compressed So Much?
NVIDIA’s fundamentals remain exceptional on paper. Recent quarterly revenue exceeded $96 billion, up more than 100% year over year, with data-center sales driving the bulk of that growth.
Yet NVIDIA’s forward price-to-earnings ratio has fallen sharply from levels above 25x earlier this year, even as shares trade near record territory.
Investors appear to be pricing in risks around potential slowdowns in AI capital expenditure, competition from custom chips, memory-cost pressures, and the sheer scale of expectations already embedded in current forecasts.
This de-rating has occurred even as NVIDIA shares remain well above prior-year levels and are still up meaningfully in 2026. The stock simply hasn’t kept pace with the explosive rise in its own earnings power, creating a valuation gap rarely seen for the company in recent years.
The divergence highlights two very different investor mindsets at work. Apple is being rewarded for steady, high-quality growth and capital discipline. NVIDIA is being scrutinized for whether its extraordinary growth rate can hold, even though that growth remains genuinely robust today.
Whether NVIDIA’s more modest multiple represents a buying opportunity or an early warning will likely depend on upcoming hyperscaler earnings and capital-spending guidance in the months ahead.
Subscribe to our YouTube channel to watch leaders and journalists provide expert insights
The post Why Is NVIDIA Getting Cheaper While Apple Hits New All-Time Highs appeared first on BeInCrypto.
A malicious iOS app distributed through Apple’s App Store has been linked to nearly $580,000 in stolen crypto after researchers found it contained multiple kernel exploits capable of escaping Apple’s sandbox and accessing sensitive wallet data.
According to an investigation published by blockchain security firm SlowMist, the app, called FomoPeek, introduced two malicious modules that could exploit iOS vulnerabilities, gain elevated privileges and access Keychain data and files belonging to other apps.
SlowMist said the affected versions were released on Sept. 9 and Sept. 12, while version 1.3, released Sept. 17, removed the malicious components.
SlowMist said its investigation, conducted with the OKX security team, began after it received reports from users who had suffered asset theft and found that some had previously installed the affected FomoPeek versions.
The exploit framework included eight attack methods and declared support for iOS versions ranging from 12.0 to 18.7.2 and 26.0 to 26.1.
SlowMist’s onchain analysis identified a primary hacker address associated with the incident that received about 579,984 USDT. The firm said the address became active on Sept. 15 and that the stolen funds involved multiple blockchain networks before being consolidated and transferred through several addresses and services.
SlowMist said portions of the funds were transferred toward services including FixedFloat, KuCoin and cce.cash, while other funds were dispersed through additional addresses that the firm continued to trace.
Cointelegraph reached out to Apple, SlowMist and OKX for comment but did not receive a response before publication.
Related: Hugging Face hack exposes the open-weight AI cybersecurity paradox
US President Donald Trump previously tapped David Sacks as his AI and crypto czar before Sacks stepped down from the role earlier this year after reaching his service limit as a special government employee.
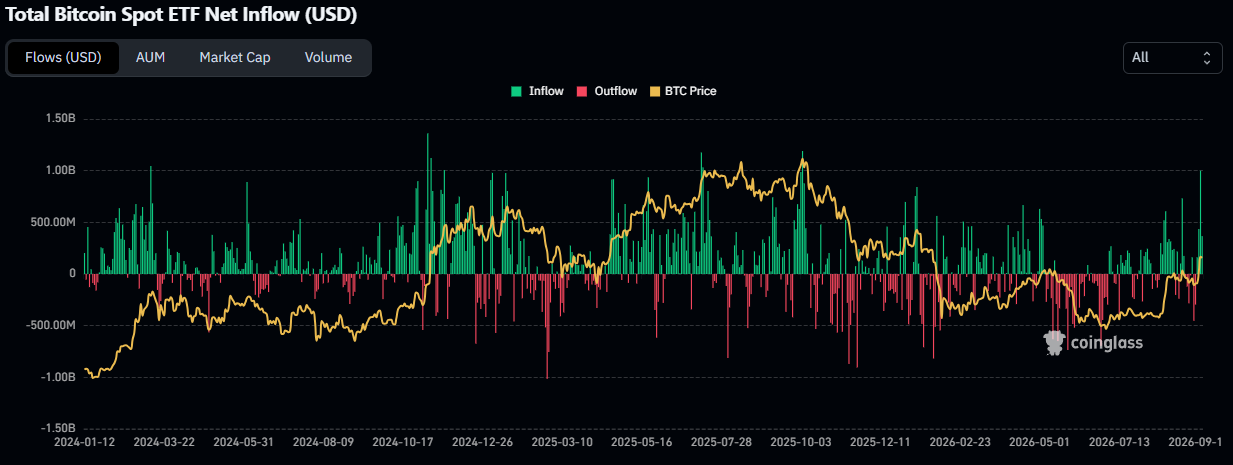
Bitcoin (BTC) exchange-traded funds (ETFs) absorbed nearly $1 billion on Monday, Sept. 21. But BTC had already jumped earlier that day on a short squeeze, CoinGlass data shows.
Bitcoin briefly topped $84,000 that day, its first trip to that level since Jan. 31. The move liquidated $262.3 million in short positions within an hour.
The Squeeze Came Before the ETF Money
That timing raises a real question about which move actually came first. Spot ETF flows are reported once daily, reflecting trades placed during the US cash session, which opens hours after Asian and European markets are already trading.

BTC’s climb came from the day’s short squeeze, which had already pushed the price higher before any same-day ETF buying could take place. That sequence suggests the derivatives market, not ETF demand, supplied the initial spark.
Outflows in the Dip, Inflows in the Rally
This would not be the first time flows tracked price rather than leading it. Spot Bitcoin ETFs posted net outflows on five of six trading days between Sept. 9 and Sept. 16, per CoinGlass. BTC was pulling back over that stretch.
Flows didn’t turn sustainably positive again until Sept. 17, when BTC’s price resumed climbing. Cumulative inflows have since topped $56.98 billion, and total net assets across all Bitcoin ETFs now stand at $107.86 billion.
Fund concentration tells a similar story. The BlackRock iShares Bitcoin Trust (IBIT) holds 785,640 BTC. That’s more than four times the 176,510 BTC held by the Fidelity Wise Origin Bitcoin Fund (FBTC). That single dominant fund looks more like capital chasing a trend than broad, independent conviction buying.
Flows May Not Spark the Rally, But They Can Extend It
None of this means ETF demand is irrelevant. Creating new ETF shares requires market makers to buy real BTC. So sustained inflows can still add real buying pressure to a rally already underway, even without starting it.
The data available cannot settle whether ETFs are capable of starting a rally on their own. What it shows for this leg is that the futures market moved first, and Wall Street’s money showed up after.
The post Bitcoin ETFs Pull In $1 Billion Monday: Are They Driving This Rally or Chasing It? appeared first on BeInCrypto.
Crypto World
Solana starts testing upgrade that could cut finality from 12.8 seconds to 150 milliseconds
A planned upgrade to make Solana even faster has moved to a testnet, where developers will try to cut the time a payment takes to become irreversible from about 13 seconds to 0.15 seconds.
That moment is known as finality. Exchanges wait for it before crediting deposits, bridges wait before releasing money on another blockchain and merchants need it to know that a payment cannot be taken back.
The upgrade, called Alpenglow, is now being introduced on Solana’s public test network, a copy of the blockchain that uses tokens with no monetary value. Developers can test the migration, find problems and restart the network without putting users’ money at risk.
Solana currently uses a system called TowerBFT to reach consensus, the process through which validators agree on which transactions belong in the permanent record. Validators record their votes on the blockchain and stack enough of them across 32 slots before a block becomes final.
Alpenglow replaces that system with a voting protocol called Votor. Validators send votes directly to one another and can settle on a block after one or two rounds, removing the long chain of onchain votes.
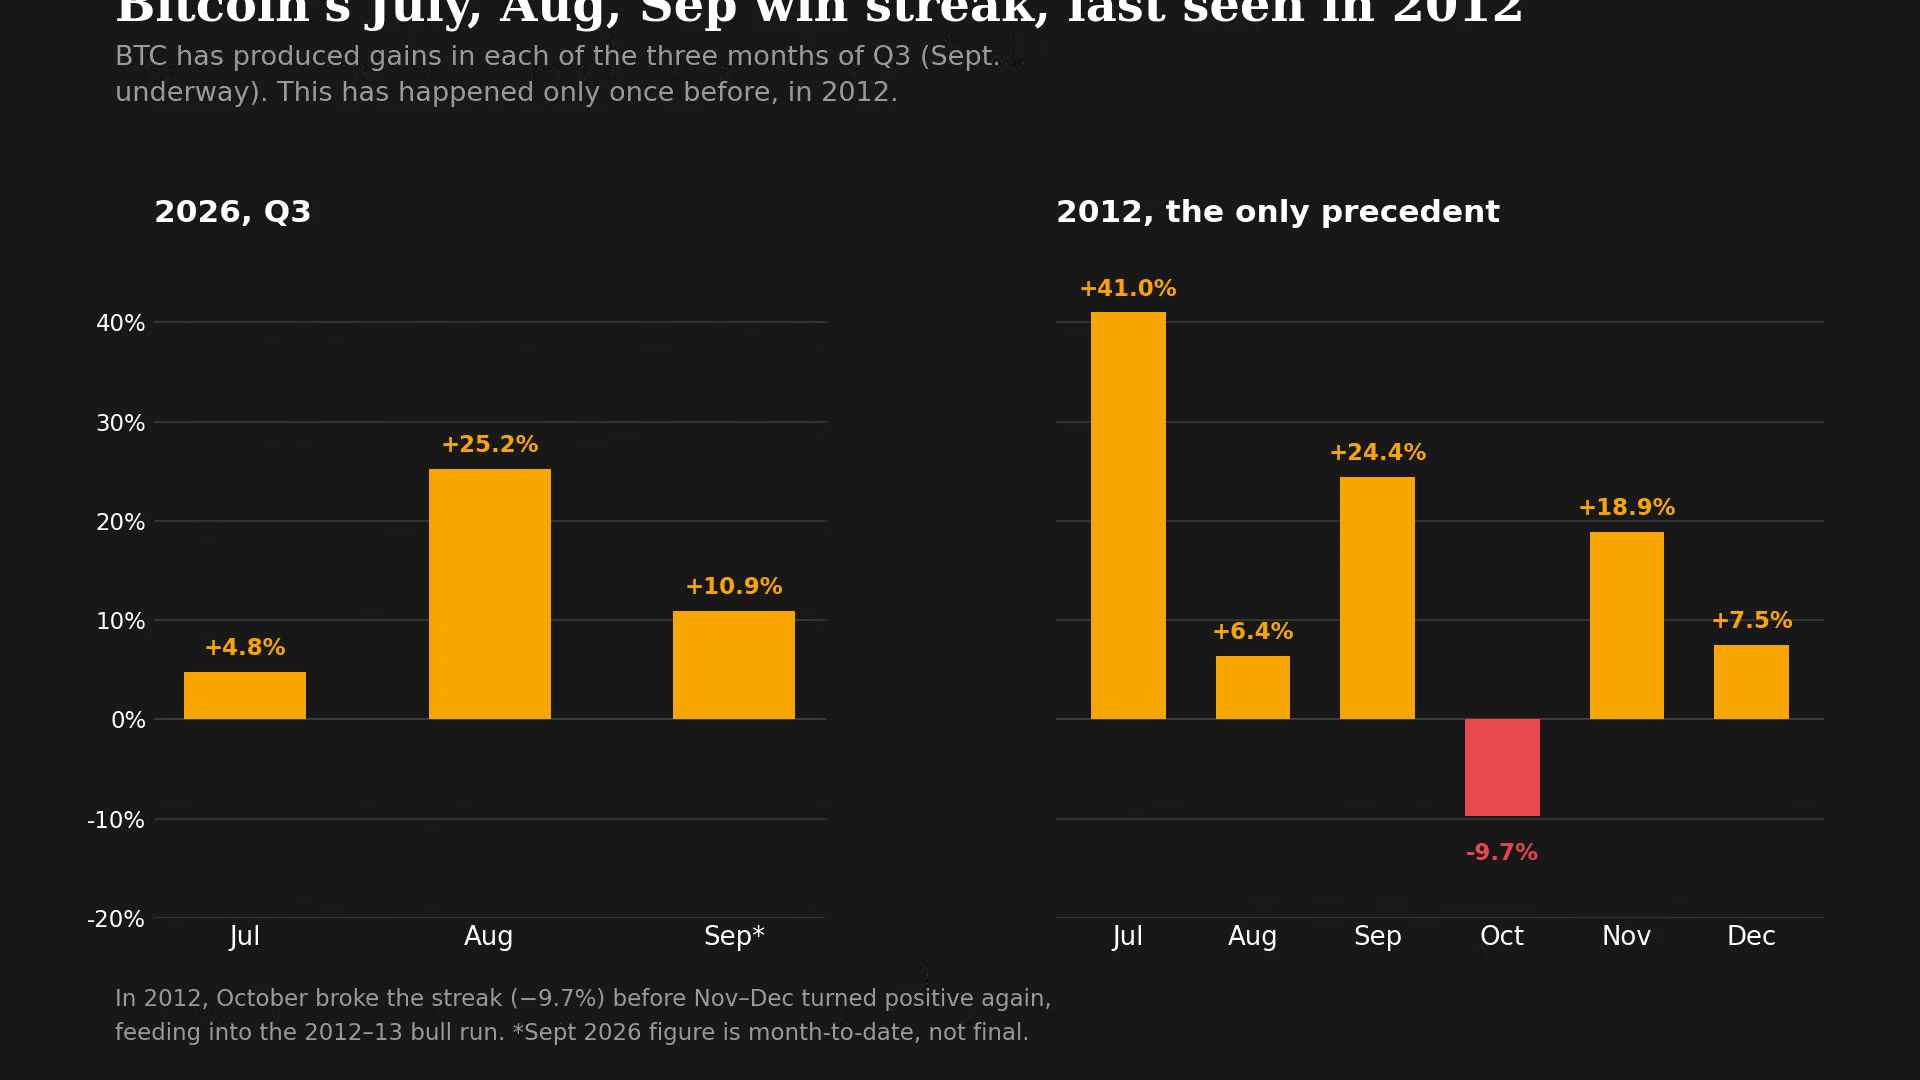
Whether this year follows a similar path – a red October followed by a big bull run – or takes a different route entirely, isn’t something the 2012 precedent can settle on its own. The sample size is too small. Bitcoin has been trading from at least late 2010 and since then, this pattern has shown up only once. So, there isn’t enough repetition to draw a meaningful conclusion about what happens next.
Still, the setup is noteworthy because of its rarity, the outsized rally that followed the 2012 example and bitcoin’s broader four-year market cycle. Some cycle models point to a potentially bullish phase beginning around October or November, although historical cycle patterns are approximate rather than fixed calendar rules
The magnitude of any rally may also be smaller than in bitcoin’s early years. In 2012, bitcoin was a thinly traded asset worth barely $10, and its market could be moved by a relatively small number of buyers.
Today, bitcoin is part of a multi trillion dollar market with substantial institutional participation, deep spot and derivatives liquidity across dozens of venues, and a broad range of directional and relative-value strategies, including options, futures and basis trades. Those markets did not exist at comparable scale in 2012, making a rally of similar percentage magnitude much harder to achieve today.
BlackRock has put a fresh institutional spotlight on the long-running idea that artificial intelligence could translate into real demand for digital assets. In a new research paper, the world’s largest asset manager argues that broader AI adoption—especially agentic, machine-to-machine activity—could act as a structural catalyst for blockchain-based infrastructure, including stablecoins and other on-chain programmable instruments.
The report, titled “The Machine-Native Economy,” also points to a second potential pathway: the compute market itself. BlackRock suggests that as AI companies increasingly manage and optimize access to processing capacity, tokens could emerge as a way to represent claims on compute resources—potentially enabling trading and collateral use—thereby widening the scope of what digital assets could support beyond payments.
Key takeaways
- BlackRock frames AI—particularly autonomous agent systems—as a “structural catalyst” for digital asset adoption.
- The firm argues stablecoins are likely to lead transactional use for high-frequency, low-value machine-to-machine payments.
- BlackRock sees an emerging opportunity for tokenized access to AI compute, potentially used for transfer, pledging, and collateral.
- The research emphasizes the practicality gap in existing payment rails for automation tasks that require authorization, credentialing, or fast finality.
Why BlackRock thinks AI will change payment demand
BlackRock’s central payments argument is that the shift from human-led commerce to agent-driven transactions may stress existing payment systems. In the paper’s view, even where today’s rails can support some automation, they may still require human involvement around key operational steps such as account setup, credentialing, and authorization. That friction could be amplified when transactions happen continuously—without a human operator to manage exceptions, timing, or settlement requirements.
The report also highlights economics and throughput. Merchant fees can make very small transfers uneconomic, while settlement and finality characteristics can differ across providers. For AI agents that transact around the clock and at potentially sub-cent value levels, these constraints could make traditional rails less suitable.
Against that backdrop, BlackRock argues that digital assets—especially stablecoins—are better aligned with machine-to-machine needs. The paper states that stablecoins, native cryptocurrencies, and tokenized real-world assets could support high-frequency payments, but it goes further by asserting that stablecoins are the most likely to dominate actual transactional usage.
“Several types of digital assets may support agentic commerce, but stablecoins are likely to lead transactional use,” the authors wrote.
Compute tokens: a second lane for digital asset demand
Beyond payments, BlackRock’s paper attempts to broaden the mental model for where blockchains could fit into an AI-driven economy. It argues that demand for compute—the processing capacity required to train and run AI systems—could create a new market for digital assets.
As AI workloads grow, BlackRock suggests AI firms may try to lock in costs and manage provider risk. In such a scenario, claims on compute capacity could potentially be represented using tokens. Those tokenized claims could be transferred between parties, used as collateral, or traded, effectively turning compute access into a more modular asset class within a digital settlement layer.
The paper further proposes that AI agents could participate in these markets automatically, purchasing compute resources as needed. If that automation becomes widespread, the authors argue it could also broaden institutional participation—positioning compute as a new opportunity for the broader digital asset ecosystem.
How this thesis echoes—and pressures—industry narratives
BlackRock’s framing aligns with an argument that has circulated across parts of the crypto industry: AI doesn’t replace crypto so much as it increases the need for programmable financial tools. That view has been expressed publicly by Coinbase CEO Brian Armstrong, who pushed back on calls for crypto to pivot away from its core value proposition. In July, Armstrong argued that AI is a megatrend that increases the demand for programmable money rather than traditional banking rails, implying that agentic activity could make crypto more relevant rather than less.
BlackRock’s research can be read as an institutional translation of that same theme—moving the conversation from speculative “AI + crypto” narratives to specific infrastructure functions: machine-native payments and tokenized access to compute.
What existing tools suggest about agent payments
While BlackRock’s paper is forward-looking, it also arrives as crypto-native companies build tooling aimed at enabling autonomous payments. Multiple projects highlighted in earlier coverage have focused on letting AI agents automatically pay for online services or initiate recurring transfers.
For example, Cointelegraph previously noted that Coinbase introduced its x402 protocol to support agent-driven payments. Tempo has also been linked with a Machine Payments Protocol designed to support payments for machine-driven workflows. The same pattern appears in Circle’s agent wallet and USDC payment tooling, and in OKX’s work on an Agent Payments Protocol intended to support recurring payments and escrow-like arrangements released after a task’s completion.
These products don’t prove BlackRock’s compute-token thesis, but they do show momentum around the narrower payments piece of the argument—especially around payments designed for autonomy, timing, and reduced human intervention.
What to watch next
If BlackRock’s thesis is directionally right, the most important developments to monitor will be real-world volumes of machine-to-machine transactions using stablecoins or other on-chain payment rails, and whether tokenized representations of compute access move from conceptual proposals into operational markets. The next step will likely determine whether “AI as infrastructure demand” becomes a measurable adoption driver—or remains a compelling institutional hypothesis.
Bitcoin and Ethereum options carrying roughly $18.1 billion in notional value have moved toward their Sept. 25 quarterly expiry with calls outweighing puts across both markets, according to Coinbase Markets.
Summary
- Bitcoin and Ethereum options worth roughly $18.1 billion are scheduled to expire and settle Friday.
- Bitcoin options carry a 0.66 put-call ratio, while recent trading volume shows 0.37, Coinbase reports.
- Ethereum options show 0.61 open-interest put-call ratio, with recent trading volume at 0.55, Coinbase says.
- Bitcoin call open interest clusters near $90,000 and $100,000 strikes ahead of Friday’s quarterly settlement.
- Ether call interest is concentrated between $3,000 and $4,000 as September contracts approach expiration Friday.
Coinbase Markets said Bitcoin’s open-interest put/call ratio stood at 0.66, while its 24-hour volume ratio was lower at 0.37. Ether showed an open-interest ratio of 0.61 and a 24-hour volume ratio of 0.55. Coinbase described both books as call-heavy, with recent trading even more tilted toward calls, particularly for Bitcoin.
A separate Deribit-sourced snapshot taken at 03:53 UTC on Sept. 23 showed $16.13 billion of Bitcoin inverse-option open interest scheduled for Friday and $2.16 billion in Ether, putting the combined figure near $18.29 billion. Differences from Coinbase’s $18.1 billion reading can arise as prices and positions change between snapshots.
Bitcoin options put $90,000 and $100,000 strikes in focus
Bitcoin accounts for most of Friday’s expiry. Deribit-sourced data showed $9.61 billion in BTC call open interest against $6.52 billion in puts for Sept. 25, producing a 0.68 put/call ratio at the later snapshot.
Coinbase identified $90,000 and $100,000 as two areas where Bitcoin call open interest is concentrated. With BTC trading near $86,500 early Wednesday, the $90,000 strike sat roughly 4% above spot while $100,000 remained nearly 16% higher. Market data showed Bitcoin trading between roughly $86,149 and $86,791 during the Sept. 23 session.
The call concentration does not establish that Bitcoin will reach either strike before expiry. Open interest counts outstanding contracts but does not reveal whether each trader bought or sold the call, while many options positions form part of spreads, hedges or market-making strategies.
Put/call ratios below one show that calls outnumber puts under the selected measure. Coinbase’s 0.37 ratio for recent BTC options volume points to considerably more call than put trading, but volume by itself does not identify the ultimate directional exposure of all participants.
The market has nevertheless moved closer to the largest upside strikes since Coinbase’s previous quarterly-expiry update. Bitcoin surged from around $76,000 on Sept. 17 to above $86,000 this week, reaching an eight-month high above $87,000 on Sept. 21.
Bitcoin’s move toward $90,000 has been supported by renewed spot demand and short covering, although analysts said continued buying would be required to sustain the advance.
Ether options build toward $3,000 to $4,000 calls
Ether’s Friday book is smaller in dollar terms but carries a similar call-heavy structure. Deribit-sourced data showed approximately $1.34 billion in ETH call open interest against $820.1 million in puts for Sept. 25, matching Coinbase’s reported 0.61 open-interest put/call ratio.
Coinbase said ETH call interest is spread through the $3,000-$4,000 range. Ether was trading close to $2,760 early Sept. 23, putting $3,000 approximately 8.7% above spot. The $4,000 strike remained around 45% higher. Market data showed ETH had traded between roughly $2,750 and $2,766 during Wednesday’s session after closing near $2,753 on Tuesday.
Ether has gained sharply since the middle of last week. The asset traded near $2,416 on Sept. 16 before moving through $2,600 and reaching an intraday high above $2,805 on Sept. 21.
Reuters reported that ETH had broken above a technical resistance level near $2,661.52, with its technical analysis identifying $3,050 as one potential upside level if momentum continued. The projection is a chart-based scenario and does not establish where ETH will trade into expiry.
Ethereum’s earlier breakout above the $2,550 area opened attention toward higher resistance levels after buyers defended support near $2,400.
Friday’s expiry has grown since Coinbase’s Sept. 15 snapshot
Friday’s notional amount has increased since Coinbase Markets published its earlier Q3 positioning data.
On Sept. 15, Coinbase placed combined Bitcoin and Ethereum options open interest for the quarterly expiry at roughly $16.6 billion. Bitcoin accounted for approximately $14.73 billion, with Ether at $1.92 billion. At the time, BTC’s put/call ratio stood at 0.52 and ETH’s at 0.57.
Bitcoin accounted for nearly 89% of the $16.6 billion Q3 options expiry in that earlier snapshot. Coinbase then identified Bitcoin’s max-pain level near $72,000 and Ether’s around $2,200.
By Sept. 23, Coinbase’s combined figure had moved to roughly $18.1 billion while the reported put/call ratios had risen to 0.66 for Bitcoin and 0.61 for ETH. A higher put/call ratio means puts have increased relative to calls compared with the earlier snapshot, even though calls still dominate overall open interest.
The increase in notional value should not automatically be interpreted as an equivalent amount of new money entering the market. Notional open interest changes with the number of outstanding contracts and the value assigned to the underlying assets, while Bitcoin and Ether prices have risen sharply since Sept. 15.
PerpFinder’s Deribit-sourced methodology notes that USD open-interest figures represent contract quantities valued using forward prices. They do not measure option premiums paid, margin posted or the amount of cash that will change hands at settlement.
Bitcoin and Ether quarterly options settle at 08:00 UTC
The Sept. 25 contracts form part of Deribit’s quarterly expiry cycle. Deribit states that quarterly BTC and ETH options expire on the last Friday of March, June, September and December at 08:00 UTC.
For Friday’s expiry, the settlement process uses the relevant Deribit index over the period immediately before expiration. PerpFinder’s methodology states that the delivery price is based on the appropriate index’s time-weighted average between 07:30 UTC and 08:00 UTC.
The size of the expiry can lead traders and market makers to adjust hedges as option deltas change when spot prices move closer to major strikes. The presence of large open interest at $90,000, $100,000, $3,000 or $4,000 does not require spot prices to move toward those levels.
Deribit reports that its platform handles roughly 85% of BTC and ETH options activity, making its quarterly expiries a large component of the crypto derivatives market. Its August statistics showed $56.13 billion in Bitcoin options turnover and $7.14 billion in Ether options turnover during the month.
Friday’s quarterly contracts are scheduled to expire at 08:00 UTC on Sept. 25. The final notional open interest, put/call ratios and strike concentrations can continue changing until traders close, roll or add positions before settlement.

BITCOIN: THIS WEEKEND CHANGES HISTORY!!!!!!!!!!!!!!
Dead lawns will spring back to life if 4 simple gardening tasks done now

Spain battles climate change on several fronts




-

 Fashion5 days ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech2 days ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Crypto World4 days ago
Circle launches Arc Studio AI agent for building onchain apps
-
 NewsBeat4 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World2 days ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-

 Crypto World4 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Crypto World4 days ago
Trading Bitcoin on Robinhood? Why 2% Spread Has Traders Worried
-

 Crypto World6 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 Crypto World4 days ago
World Money launches in 150+ countries with Stripe
-

 Business2 days ago
Analog Devices (ADI) Bets $1.35 Billion on Chips that Let Machines Think for Themselves
-

 Crypto World5 days ago
Mortgage and refinance interest rates today, Thursday, September 17, 2026
-

 Crypto World5 days ago
Silver prices recover quickly, hitting weekly high today
-

 Crypto World2 days ago
Coinbase, Robinhood, Circle Seen as Tokenized-Stock Winners
-

 Tech5 days ago
GPT-6 Astra Reached the Nether in Minecraft, Lost Its Stash to a Creeper, and Farmed Potatoes for Hours
-
 NewsBeat4 days ago
US was ‘on brink of war’ with China over false AI report of nukes moving in Middle East
-

 Crypto World2 days ago
Bitcoin price holds above $81K as key catalysts line up
-
 Entertainment6 days ago
Grey’s Anatomy Showrunner Teases Changes After Cast Exits
-
 Crypto World4 days ago
CFTC sends crypto market structure rulemaking to White House
-

 Crypto World1 day ago
Meta Jumps 11% As Muse Shines and Investors Show an Appetite for Advancing AI
-
 Business5 days ago
Newsom accelerates AI oversight, advances ‘kill switch’ plan
You must be logged in to post a comment Login