
Crypto World
U.S. commodities firms can invest in tokenized assets, use blockchain records: CFTC

They may not even have to maintain offchain versions of the records if the firm is using a private network. If the blockchain is public and permissionless, the document said, the regulated business “should establish systems and controls that enable it to retain and produce such records under any circumstances, including in the event of an emergency or other disruption to the network.”
The CFTC has been hurrying to erect new policies, whether by stating an updated, crypto-friendly view on existing regulations or writing new rules. The process has been especially urgent after the U.S. Senate’s failure last week to advance the Digital Asset Market Clarity Act that would have set up a U.S. regulatory regime for the industry, including granting the CFTC powers over the crypto spot markets — which remains a regulatory hole for the sector.
“I’m pleased to see staff update these frequently asked questions consistent with the agency’s ongoing efforts to provide regulatory clarity for the crypto industry,” CFTC Chairman Mike Selig said in a statement.
Read More: CFTC sends crypto rules to White House to review as Congress stalls on Clarity Act

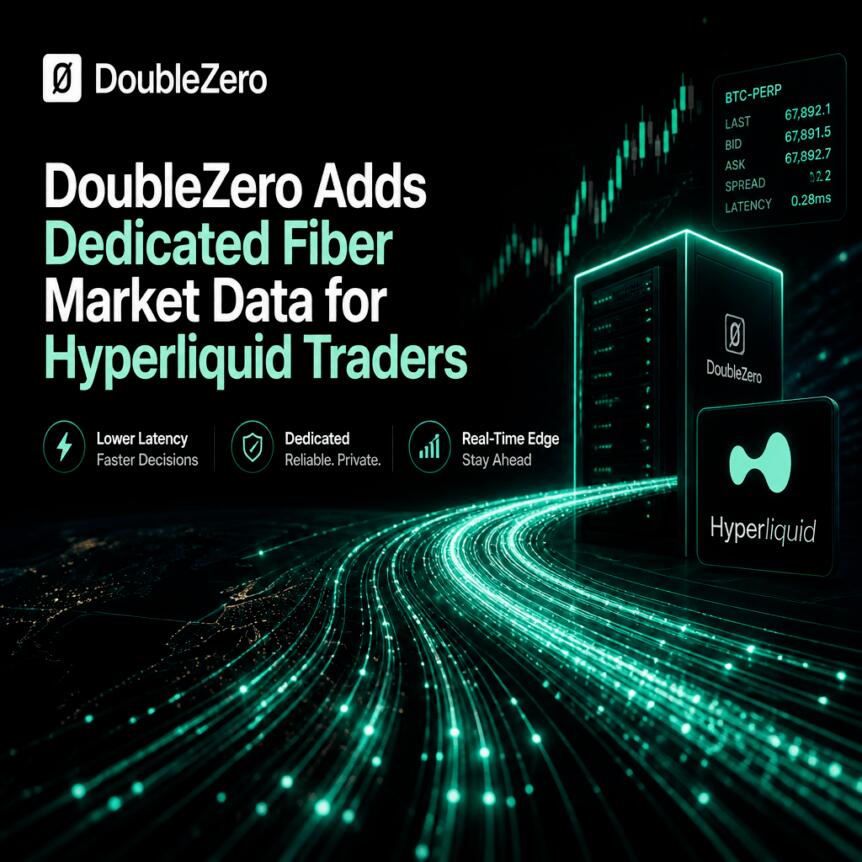
DoubleZero has launched a dedicated fiber-based market data feed for Hyperliquid, aiming to give professional trading firms a more reliable way to consume the decentralized exchange’s full order book. Instead of relying on Hyperliquid’s public APIs, participants can access an ordered, continuous stream of market data over a private network connection—an approach designed for market makers and quantitative desks that prioritize speed and consistency.
The feed covers Hyperliquid’s native perpetual futures markets and also markets run by trade[XYZ], which uses Hyperliquid’s infrastructure to offer perpetual contracts linked to assets including oil, gold, and silver. DoubleZero says the service was developed alongside validator operators and ecosystem partners such as Hyperion DeFi, MAVAN, and Kinetiq.
Key takeaways
- DoubleZero’s Hyperliquid feed delivers the full order book via a fiber network, avoiding the limitations of public API updates.
- The service supports Hyperliquid native perps and trade[XYZ]-hosted markets, including perpetuals tied to oil, gold, and silver.
- DoubleZero cites reduced update frequency and depth in Hyperliquid’s public APIs as a key reason firms may need a dedicated data stream.
- Hyperion DeFi CEO Hyunsu Jung frames the development as “onchain markets adopting” the professional market-data distribution model, not as a direct replacement for traditional exchange infrastructure.
A dedicated order book feed for onchain venues
For many professional traders, the challenge with onchain venues is not just execution—it’s the quality and cadence of market data. DoubleZero’s new offering is positioned as an alternative to stitching together order book views from public API responses or from running one’s own nodes.
In its announcement, DoubleZero said that firms previously seeking a complete picture of Hyperliquid’s order book had to aggregate public data themselves or operate Hyperliquid infrastructure. It also argued that changes to Hyperliquid’s public APIs have reduced both the frequency and the depth of the updates available through those endpoints.
The DoubleZero feed is designed to address that gap. According to DoubleZero, it provides a continuous, ordered stream of market data intended for market makers and quantitative and proprietary trading firms that depend on fast, consistent order book refreshes.
Built with ecosystem partners and validator operators
DoubleZero did not present the initiative as a solo effort. It said the Hyperliquid feed was built with input and support from validator operators and ecosystem partners in the broader onchain ecosystem, including Hyperion DeFi, MAVAN, and Kinetiq.
The feed’s scope is also broader than a single venue’s flagship product. In addition to Hyperliquid’s native perpetual futures markets, it includes perpetual markets operated by trade[XYZ]. Those contracts are linked to assets such as oil, gold, and silver—showing that the data pipeline is intended to serve professional participants operating across multiple perpetual offerings within the Hyperliquid ecosystem.
DoubleZero further said the infrastructure is part of its wider “Edge” market-data service, which is already available for other venues. The Hyperliquid feed is presented as the third location offered through that service, after Solana and prediction market operator Kalshi.
Closer to traditional exchange data distribution—without pretending it’s identical
Hyperion DeFi CEO Hyunsu Jung described the direction of travel as convergence in the market-data layer rather than the trading model. In comments to Cointelegraph, Jung compared DoubleZero’s fiber-based distribution to how traditional electronic exchanges deliver professional market data.
Jung explained that exchanges such as CME and Nasdaq distribute professional data through dedicated networks, enabling automated trading firms to receive a consistent, ordered stream with high speed. In that sense, he said, Hyperliquid data can now be consumed through a similar fundamental model: “publish once, distribute simultaneously over dedicated fiber.”
However, he stressed the important differences remain. Traditional exchanges allow firms to reduce latency by placing trading systems physically closer to the exchange infrastructure that processes orders. Hyperliquid’s execution happens onchain, which means placement advantages still operate at the level of physics and connectivity.
As Jung put it, the “convergence is not Hyperliquid becoming CME.” Instead, onchain markets are adopting market-data infrastructure patterns that professional traders already use. At the same time, he cautioned that the move does not eliminate latency differences—such as the advantage a firm in Tokyo may still hold over a firm in New York.
Why this matters for professional traders and market makers
Dedicated order book data feeds can be consequential for firms that treat the order book as the primary signal. When update cadence slows or when public endpoints provide less depth, traders face a trade-off: either accept higher uncertainty in their models or invest additional effort into alternative data paths.
DoubleZero’s positioning suggests the latter option is becoming more practical as onchain venues mature. By distributing ordered market data over fiber rather than through public API calls, the service aims to deliver the predictability that quantitative systems often require to manage strategies, risk controls, and routing decisions.
It also highlights a shift in how professional onchain participation may evolve. Instead of relying solely on “build your own stack” approaches—such as running nodes or aggregating public data—firms can increasingly buy into infrastructure layers designed specifically for low-latency, consistent streaming.
For investors and observers, the broader takeaway is that the competitive edge between trading venues may increasingly depend not only on smart contract execution or liquidity incentives, but on the surrounding operational tooling: data transport, ordering guarantees, and the practical latency realities of trading systems.
What readers should watch next is how widely this approach is adopted across onchain venues and whether additional venues follow the same pattern of dedicated, ordered distribution. Equally important is whether Hyperliquid’s public API changes continue to push more high-frequency and market-making activity toward fiber-based or provider-managed data channels.
Bitget said unauthorized transfers affected a limited number of hot wallets, while cold wallets and most platform assets remained unaffected.
Bitcoin has reached an eight-month high before retreating toward $85,000, as U.S. spot ETFs have drawn about $1.7 billion in two days and futures traders have added more than $2 billion in new positions.
Summary
- U.S. spot Bitcoin ETFs took in $999 million on Sep. 21 and $714.7 million on Sep. 22.
- BTCS adviser Wojciech Kaszycki sees a rally that began with spot demand but is attracting leverage.
- He puts the next test at $90,000, where holders may sell after recovering earlier losses.
- Kaszycki says treasury companies should pace purchases and avoid borrowing against their Bitcoin.
Wojciech Kaszycki, strategy adviser to Warsaw-listed Bitcoin treasury company BTCS S.A., told crypto.news that ETF inflows, futures open interest and funding rates together give a clearer picture of the rally than price alone. In his assessment, cash buying supported the initial move, while borrowed positions have started to accumulate on top of it.
“Simple test: who is buying, and with what money,” Kaszycki said. He described ETF demand as cash entering funds, while leveraged futures positions can be closed by force if prices turn against traders.
The distinction has become more pressing after Bitcoin reached $87,392 on Sep. 21, its highest price since Jan. 29, according to Bitfinex Alpha. By Sep. 24, it had fallen back toward $84,000, even as U.S. spot Bitcoin ETFs recorded another day of net inflows.
Bitcoin ETF buying has outpaced the rise in open interest
Kaszycki said he looks first for ETF inflows that continue over weeks, rather than a single large trading day. He then compares the change in futures open interest with Bitcoin’s price: if outstanding contracts grow much faster than the price, more of the advance may depend on borrowed money. Funding rates show what traders are paying to keep long positions open.
For the latest move, he cited about $1 billion of U.S. spot ETF inflows on Monday and $700 million on Tuesday. Bitfinex reported the more precise daily totals as $999 million on Sep. 21 and $714.7 million on Sep. 22. Its report on Bitcoin’s buyer range also placed a large concentration of recent purchases between $85,000 and $86,500.
Kaszycki estimated that open interest was up about 7% over a month, with funding around 8% on an annualized basis. He called the funding rate positive but not excessive, while warning that the balance could change if traders keep adding leverage faster than cash buyers enter the market.
“Spot-led start, with leverage now climbing on top,” he said. “That second part is what I’ll be watching next week.”
He contrasted the current setup with August, when, in his account, a rally faded as ETF buying paused. Kaszycki said open interest fell and funding approached zero in early September before the latest fund inflows arrived.
Since Tuesday’s inflow, U.S. funds have recorded another positive session: SoSoValue data cited in coverage of the five-day ETF streak put Sep. 23 net inflows at $346.98 million. Bitcoin nevertheless pulled back from above $87,000, showing that fund subscriptions and the spot price need to be assessed separately.
A move through $90,000 would meet selling, Kaszycki says
Kaszycki sees $90,000 as both a round-number trading level and a test of whether spot buyers can absorb sales. He said holders who bought Bitcoin between $90,000 and $110,000 last year may use a return to that range to sell near their purchase prices. Investors who bought around $63,000 in August may also take profits.
Short liquidations could push Bitcoin higher as traders buy back contracts to close losing positions, he said, but such buying ends once those positions have been cleared. In his view, holding a price above $90,000 would require continuing ETF subscriptions and purchases through corporate or over-the-counter channels.
“What happens to spot flows in the two weeks after we touch it is the story,” Kaszycki said.
For U.S. investors, the daily ETF figures offer one visible measure of demand through listed products. They do not, on their own, identify the end investors placing orders or establish when the funds acquired the underlying Bitcoin. A Sep. 24 examination of buyers after the Fed hike found that the funds took in about $2.65 billion across five sessions through Sep. 23, after losing $746.3 million over Sep. 15 and 16.
Bitcoin treasury purchases depend on the financing price
For companies that hold Bitcoin, Kaszycki favors scheduled purchases over attempts to time each rally or pullback. He said BTCS carries out most of its larger purchases over the counter with market makers. When trading becomes fast, the company reduces the size of individual orders and spreads them out rather than stopping its buying program.
He also described selling put options below the market as one approach BTCS uses: the company receives a premium if the option expires without a purchase, or buys coins at the option’s agreed price if it is exercised. The result depends on the contract terms and Bitcoin’s price at expiry.
Kaszycki placed particular weight on how a listed company pays for additional coins. In his view, issuing shares to buy Bitcoin makes sense only when the shares trade above the value of the Bitcoin the company already holds. Issuing equity below that value, he argued, can reduce the Bitcoin attributable to each existing share.
U.S. treasury companies provide a recent example of the financing choices investors can examine. Strive said it used proceeds from SATA preferred stock to fund a $36.6 million purchase of 469 BTC between Sep. 8 and Sep. 11, according to a report on its treasury purchase. The transaction raised its reported holdings to 25,000 BTC.
Futures liquidations can reach corporate holders quickly
Kaszycki said fund transactions and futures liquidations operate on different schedules. U.S. ETF activity runs through trading-day processes, while leveraged crypto positions can be liquidated within minutes at any hour. A sharp futures sell-off can therefore lower the market value of a corporate Bitcoin holding even when the company has not borrowed against its coins.
Debt-funded companies face a second pressure in his assessment: a falling Bitcoin price reduces the value of their holdings while a declining share price can make new capital harder to raise. He advised companies to avoid margin, perpetual futures and borrowing against their Bitcoin on terms that can trigger a rapid demand for repayment.
“If you must hedge, use options where the maximum loss is the premium you paid,” Kaszycki said. He added that liquidations of other traders’ positions can still force an unleveraged company to record a lower market value for its Bitcoin holdings.
Strive has generated an estimated $85.88 million through sales of its SATA preferred stock over three trading sessions, enough to buy about 1,002 Bitcoin at prices recorded by BitcoinTreasuries.net.
Summary
- BitcoinTreasuries.net estimates that SATA sales raised $85.88 million from Sep. 21 to Sep. 23.
- Its estimated Bitcoin figure is based on trading data, not a confirmed Strive purchase.
- Strive last reported holding 26,355 BTC after buying 1,355 BTC in the prior week.
- Strategy bought 950 BTC in its latest reported week while using cash to repurchase STRC shares.
BitcoinTreasuries.net’s SATA tracker estimates how many shares Strive issues through its at-the-market program by examining trading volume while SATA is at or above its $100 stated value.
It then estimates net proceeds after sales commissions and divides that amount by Bitcoin’s price during the session. The tracker’s figure is therefore an estimate of potential buying power; Strive’s next disclosure would establish any actual purchase and its cost.
Strive’s SATA sales are estimated at $85.88 million
For Sep. 21, the tracker estimates that Strive sold about 284,000 SATA shares and received $27.69 million in net proceeds. At an average Bitcoin price of $86,001, that sum would cover approximately 321.97 BTC.
The largest of the three estimated sessions came on Sep. 22. BitcoinTreasuries.net puts net proceeds at $36.08 million from roughly 370,000 shares, equivalent to about 418.27 BTC at an average price of $86,266.
On Sep. 23, estimated sales of another 226,700 shares produced $22.11 million. The tracker calculates that the proceeds could buy 261.43 BTC at an average price of $84,556. Together, the three daily estimates come to $85.88 million and 1,001.67 BTC.
Those daily share counts are estimates of issuance through the program, rather than a count confirmed in a new company filing. BitcoinTreasuries.net says it calibrates its model against Strive’s subsequent disclosures. Its method also separates potential SATA issuance from ordinary trading between investors, which does not send money to Strive.
The distinction matters because proceeds raised on a given day need not pay for a Bitcoin trade on that same day. Strive also holds cash and can use more than one source of funding. An estimated BTC equivalent should not be added to the company’s reported holdings before Strive discloses a purchase.
Strive’s last filing put its treasury at 26,355 BTC
Strive’s most recent reported acquisition covered Sep. 14 through Sep. 18, when it bought 1,355 BTC for approximately $107.7 million at an average of $79,475 per coin. The purchase lifted its disclosed balance from 25,000 BTC to 26,355 BTC. At the time, its SATA shares outstanding increased by 786,194, while cash and equivalents rose to approximately $229.6 million.
Chief Executive Matt Cole described how Strive raised capital during that reporting period. “Warrant exercises began last week, generating $21.2M in gross proceeds,” he wrote on X. “Including those proceeds, 57.7% of total capital raised came from SATA proceeds.”
The company had reached 25,000 BTC a week earlier after acquiring 469 BTC for approximately $36.6 million. Strive said proceeds from SATA funded that purchase. Its Sep. 14 filing also showed that SATA shares outstanding rose by 402,541 during the period, while its effective common share count increased by 34,206.
Earlier in September, Strive added 1,375 BTC for approximately $109 million. That purchase took its balance to 24,531 BTC, following an acquisition of 1,800 BTC in late August. The successive company filings show completed purchases; the Sep. 21–23 tracker readings concern a later period for which the supplied figures remain estimates.
Strategy bought Bitcoin while repurchasing STRC
Strategy, the largest public corporate Bitcoin holder, disclosed a different use of its cash in the week ended Sep. 20. According to its SEC filing, it bought 950 BTC for $75.7 million at an average price of $79,670, taking its holdings to 846,000 BTC. Strategy reported an aggregate acquisition cost of about $63.8 billion, or $75,416 per coin.
During the same week, Strategy spent $174 million repurchasing approximately 1.77 million shares of its STRC preferred stock. As crypto.news reported on Sep. 21, Strategy made no sales through its at-the-market programs for that period. It paid for both the Bitcoin and the STRC repurchases from existing USD Cash, which fell from roughly $1.30 billion to $1.05 billion.
A week without new STRC issuance does not establish that Strategy can no longer raise money through its securities programs. Its earlier filing showed that it sold MSTR common shares at the end of August and directed $369.7 million of the proceeds toward 4,603 BTC. The Sep. 20 filing establishes only how Strategy financed its latest reported transactions.
Strive also owns Strategy’s preferred stock. Its filings showed a holding of 505,000 STRC shares through Sep. 18, valued at approximately $49.7 million on that date. Strive’s own preferred shares, SATA, carried a 13% annualized dividend rate for September, compared with 12% for STRC, according to the companies’ disclosures reviewed in earlier preferred-stock coverage.
U.S. investors can check the next SEC disclosures
Both Strive’s ASST common shares and SATA preferred shares trade on Nasdaq, according to its SEC filing. The securities give U.S. investors different claims on the same company: common shareholders own equity, while SATA holders have the preferred rights set out in its terms. Strive reports changes in its Bitcoin balance, cash, and outstanding share counts in its filings.
The next Strive filing can establish whether the company bought Bitcoin after Sep. 18 and how many SATA shares were outstanding at the end of the new reporting period. Its last filing also recorded 505,000 STRC shares held and $229.6 million in cash and equivalents as of Sep. 18.
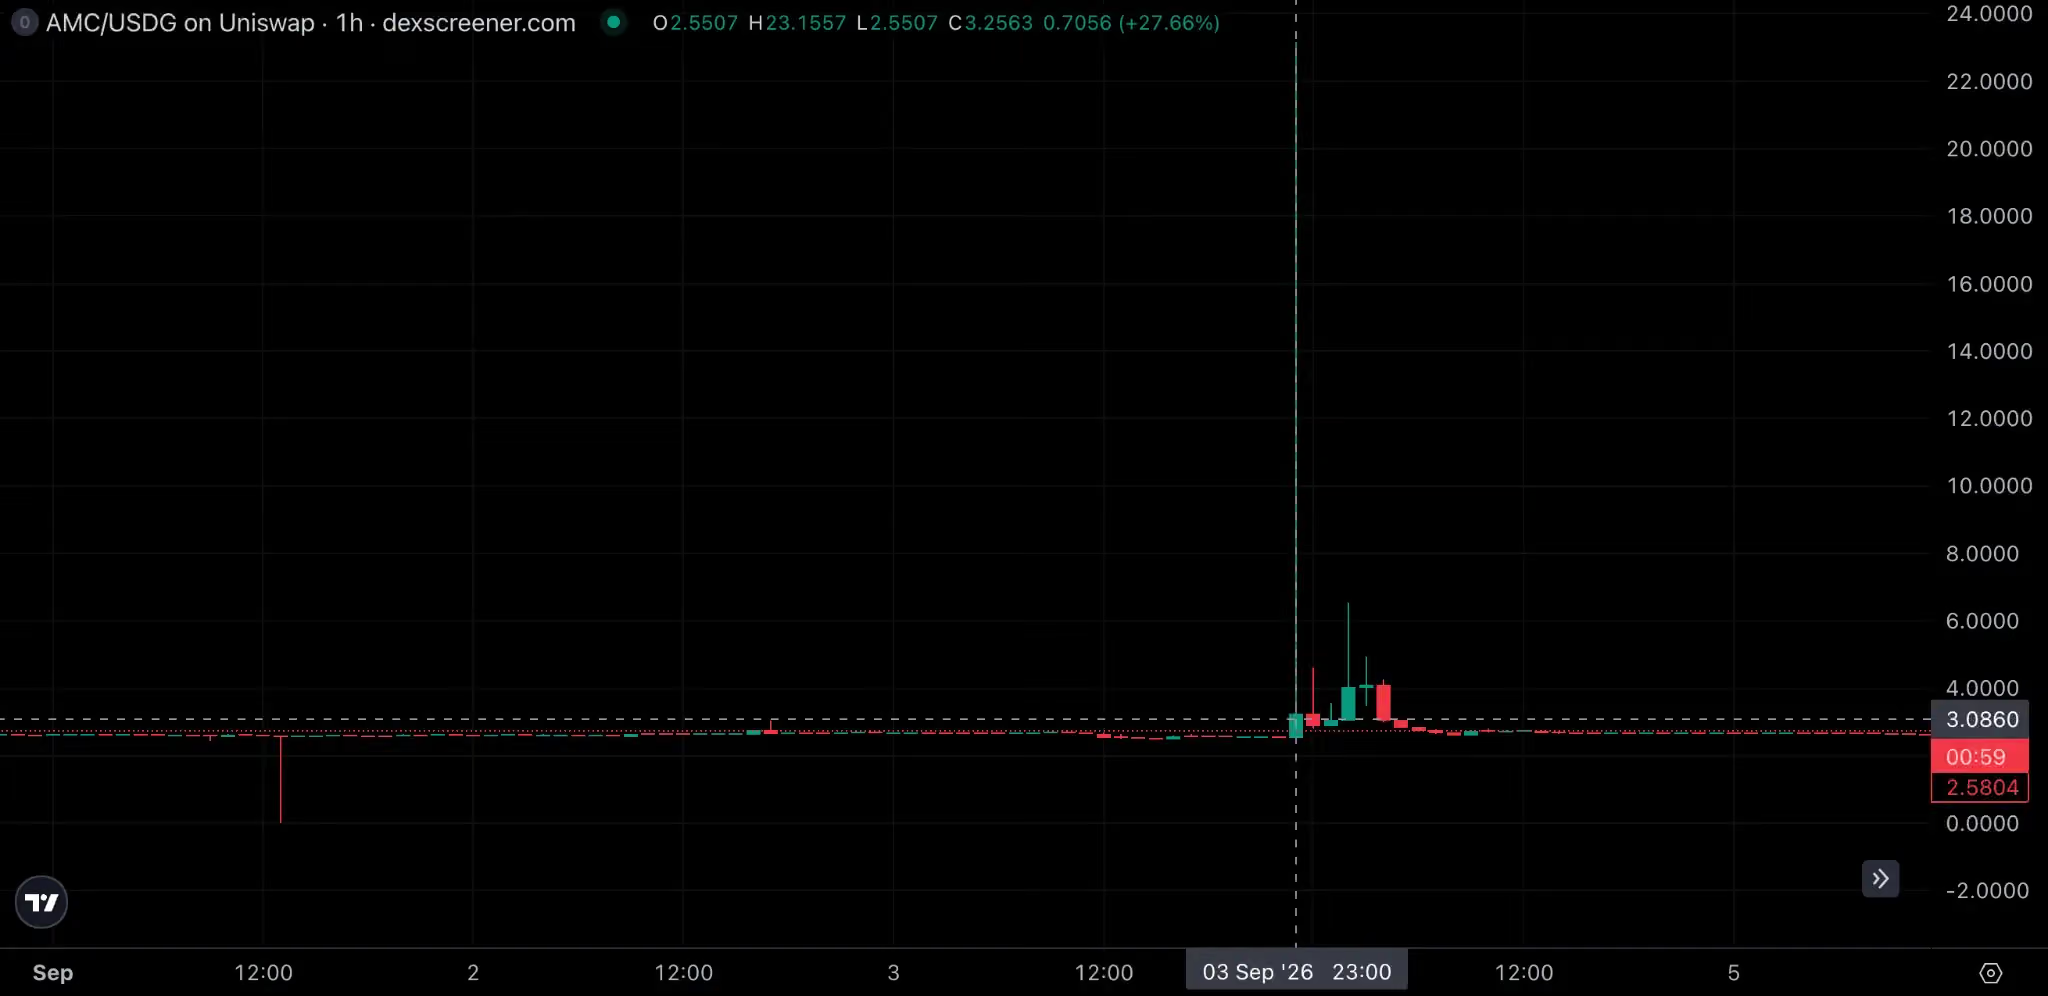
However, a different picture emerges when the underlying market is closed. Leading up to midnight on Thursday, September 3, Robinhood’s AMC token went from $2.55 to as high as $23.16, which is nine times the $2.54 AMC had closed on NYSE seven hours earlier, before coming back down to $3.26 within the same hour. Volume through the pool during the hour was $10.5 million.

Wrapped tokens such as Robinhood’s AMC are often structured as claims against offshore issuers, which collateralize the tokens with the underlying shares. Theoretically, if the issuer ensures that underlying stock positions and the claims are matched 1:1, the price should align, but in practice, the two instruments are traded separately and can thus diverge. Arbitrageurs, such as high-frequency trading firms and market-making desks, step in to keep markets in line, lock in arbitrage profits, and close any dislocations. The same mechanism keeps depositary receipts aligned with their underlying shares, and ETFs with their net asset value.
In Robinhood’s case, however, the Jersey issuer names only one authorized participant able to create and redeem. The spike fell well inside the hours when it was permitted to do so, but the participant did not mint or burn any tokens at the time. Onchain data shows 47 mints on Friday, Sept. 4, every one between noon and 7 p.m. ET, comfortably inside the cash session, half a day after the token had depegged and recovered.
Tokenization platform Ondo Finance was shopped to prospective buyers after the sudden death of its founder and CEO, Nathan Allman, earlier this year, according to three people with knowledge of the matter.
The outreach occurred sometime after Allman’s death on May 25, according to two of the people who spoke on condition of anonymity, as the matter is private.
But who, exactly, was behind the attempts to sell Ondo Finance remains unclear.
In early August, Allman’s estate filed suit against Ondo’s acting CEO Ian De Bode, alleging an unlawful power and money grab and sparking a bitter corporate control fight.
Nathan Allman died unexpectedly and without a will at 32, creating uncertainty over the fate of his controlling stake in Ondo Finance and his massive trove of ONDO tokens. After a probate process, his estate was awarded to his parents, 77-year-old Kathleen Allman and 82-year-old Lawrence Allman.
The Federal Reserve has released two proposed GENIUS Act rules covering the assets that must back payment stablecoins and the approval process for banks seeking to issue them through subsidiaries.
Summary
- Fed-supervised issuers would have to fully back their payment stablecoins with permitted reserve assets.
- The reserve proposal also covers capital, risk controls, and firms that hold backing assets.
- Insured state member banks would need Fed approval before a subsidiary could issue payment stablecoins.
- Public comments are due 60 days after the proposals appear in the Federal Register.
The Federal Reserve Board said in a Sep. 24 release that it is seeking public comment on two proposals for payment stablecoin issuers under its supervision. One sets operating requirements for issuers and firms holding their reserves; the other sets out how an insured state member bank would apply to issue stablecoins through a subsidiary.
The proposals would put detailed rules behind parts of the GENIUS Act that affect U.S. banks and stablecoin companies. They remain open to revision, and the 60-day comment period will begin when the notices are published in the Federal Register. The Fed has not set a calendar deadline in its release.
How the Fed would regulate stablecoin reserves
Under the first proposal, a Fed-supervised issuer would have to hold permissible assets that fully back its outstanding payment stablecoins. The Fed identified short-term U.S. Treasury bills and certain other high-quality, liquid assets as examples of eligible reserves. Full backing means the issuer must hold assets against the tokens it has issued, rather than rely on a smaller pool of reserves.
The draft would also set standardized capital requirements addressing credit and operational risks tied to payment stablecoins. Separate risk-management standards would govern how issuers run the activity. According to the Fed, the same proposal would introduce rules for firms it supervises that safeguard the assets backing stablecoins.
For a U.S. token holder, the reserve rules concern the assets behind a stablecoin issued by a firm within the Fed’s remit. The proposal does not turn a payment stablecoin into an insured bank deposit. Its requirements apply to the covered issuer and its reserve arrangements, while the Fed’s second proposal addresses a bank’s request to enter the business.
The first draft would also clarify which stablecoin and related activities Fed-supervised banks may undertake. That provision sits alongside the issuer and reserve rules, giving banks a proposed regulatory basis for activities beyond an application to create a stablecoin-issuing subsidiary.
How banks would seek stablecoin approval
The second proposal applies specifically to insured state member banks seeking Fed approval for a subsidiary to issue payment stablecoins. Under the Fed’s application draft, the bank would file the application with its appropriate Federal Reserve Bank. The bank, rather than the proposed subsidiary, would be the applicant.
Applicants would submit a business plan, financial information, and other material the Fed needs to assess the proposed operation. The filing would have to describe the plan, state what approval the bank is seeking, and explain why it should be granted under the factors in the GENIUS Act. The draft also sets procedures for hearings, appeals, and final decisions.
Timing is a material part of the bank proposal. The Fed would notify an applicant within 30 days whether its filing is substantially complete and identify additional information needed if it is not. Once an application is substantially complete, the GENIUS Act gives the Fed 120 days to decide; under the law, a complete application is deemed approved if the Fed does not decide within that period.
A material change could affect that clock. The Fed’s draft says a substantial change to a proposed issuer’s business plan, ownership, or financial condition may require more information and a new submission date. It also asks for comment on applications involving several banks in a stablecoin consortium, including whether a single filing could cover participating insured state member banks in some circumstances.
Those questions have a practical U.S. banking context. On Sep. 1, Bank of America, Citi, Goldman Sachs and 18 other financial institutions committed to establish a stablecoin company, according to a September report on the bank consortium. The group targeted a U.S. dollar token in the first half of 2027 and said it intended to meet applicable GENIUS Act requirements. Its announced plan does not establish that the venture would use the Fed application route described in this proposal.
Where the GENIUS Act rulemaking stands
The Fed’s proposals join rulemaking already underway at other U.S. agencies. In August, crypto.news covered Treasury’s proposed definitions for when payment stablecoins are issued, offered, or sold in the United States. Treasury’s questions concern which activity falls under U.S. licensing and distribution restrictions, while the Fed’s new drafts address issuers it supervises and applications from insured state member banks.
The Office of the Comptroller of the Currency has been working on a separate framework for issuers under its authority. As reported in August, Comptroller Jonathan Gould set a November target for final OCC rules after industry feedback. Its proposal covers matters including reserves, redemptions, custody, supervision and issuer applications. The OCC timetable does not set a completion date for the Fed’s newly released proposals.
Treasury has identified Jan. 18, 2027, as the expected effective date for the GENIUS Act’s main issuer restrictions. The statute also provides for an earlier start 120 days after the responsible federal regulators issue their final implementing rules. Federal agencies missed the law’s July 18, 2026, deadline for completing those rules, leaving several proposals at different stages of review.
For the two Fed notices released on Sep. 24, interested banks, issuers, and other members of the public can submit comments during the 60-day period following Federal Register publication. The application proposal identifies the Fed’s online proposal system, mail, and email as ways to file responses, with submissions identified by its docket number.
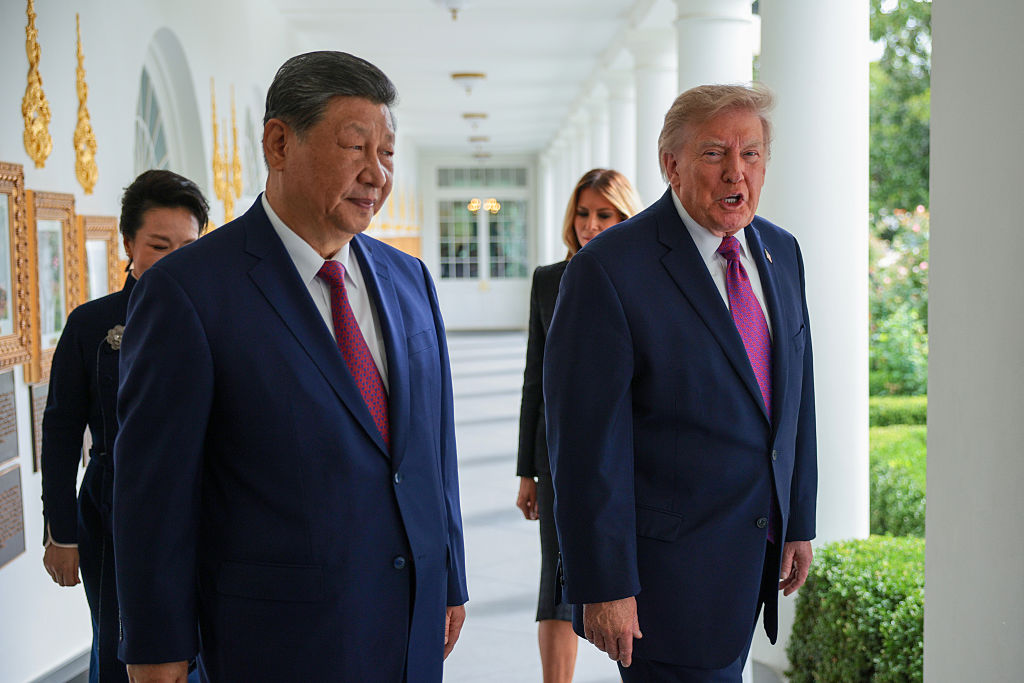
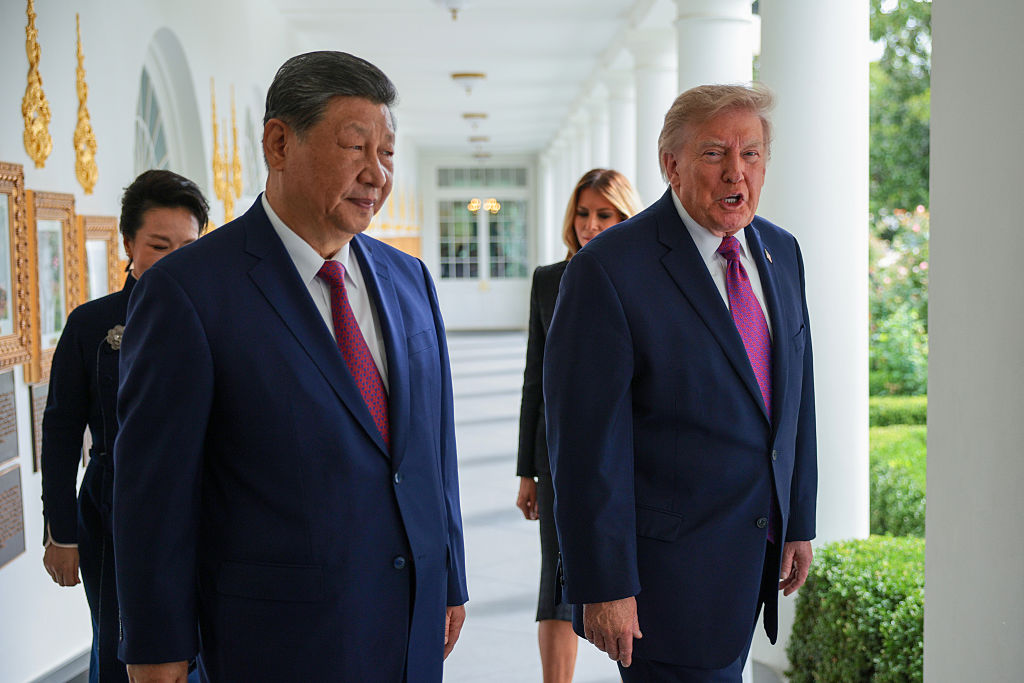
Amid a fast-growing international debate over regulating artificial intelligence, President Trump and Chinese President Xi met at the White House for several hours on Thursday ahead of a state dinner where several of the biggest players in A.I. were set to attend.
“We had a great meeting,” Trump said later that afternoon at the Southern Portico, where he gave Xi a tour of the South Lawn Helipad.
“He’s an expert on stones, and he loves good granite,” Trump said of Xi.
The day began with remarks from both Trump and Xi at the grand foyer of the White House. Afterward, Trump and Xi participated in a military review at the Rose Garden and took part in hours of meetings before Trump led a tour of parts of the White House.
While both leaders mentioned AI in their opening remarks, Xi stressed that the development of AI always needs to be “under human control.”
Trump was set to host a state dinner for Xi Thursday evening, joined by a slate of tech leaders. Amazon Executive Chairman Jeff Bezos, Google CEO Sundar Pichai, OpenAI CEO Sam Altman and Tesla CEO Elon Musk were set to attend the dinner, a White House official confirmed.
According to Chinese state media, President Xi raised the issue of Iran during the bilateral meeting, saying that he hoped the US and Iran would resume negotiations and that China would support the two countries recommitting to the 14-point memorandum of understanding reached months ago.
On Taiwan, Xi said he hopes the U.S. would maintain its position of opposing Taiwan independence. The U.S. has not officially endorsed Taiwan’s independence, but has previously sold weaponry to the island and is widely viewed as a key player if China were to ever invade the self-ruling island.
Earlier on Thursday, Xi urged more cooperation between the two countries. During his remarks, he called for more direct flights between the U.S. and China and invited 100,000 American students for cultural exchange in the next five years. And continuing a longtime diplomatic tradition stretching back to the Nixon era, he announced two pandas, Ping Ping and Fu Shuang, will be delivered to Zoo Atlanta in the coming days.
“China and the United States must hold the line of no conflict and no confrontation between us, and we can certainly find the right path for two great countries to get along on this planet we both call home,” Xi said.
This is the first time a Chinese leader has made a second formal state visit to America. The last time Xi conducted a formal state visit in Washington, D.C. was at the invitation of President Obama in September 2015, three years after he succeeded as the General Secretary of the Chinese Communist Party.
Trump and Xi first met in 2017, during Trump’s first term, at the President’s home base of Mar-a-Lago, Florida. The pair last met in May during a two-day state visit by Trump to Beijing, where the U.S. and China delegations discussed a range of topics including tariffs, rare mineral trade, as well as the Strait of Hormuz. The two leaders used the visit to announce the launch of a so-called Board of Trade intended to lower tariffs on products that aren’t considered a national security risk. In June, the Office of the United States Trade Representative asked the public to weigh in on which types of products would benefit from this new mechanism. The Administration has offered few updates on the board since then.
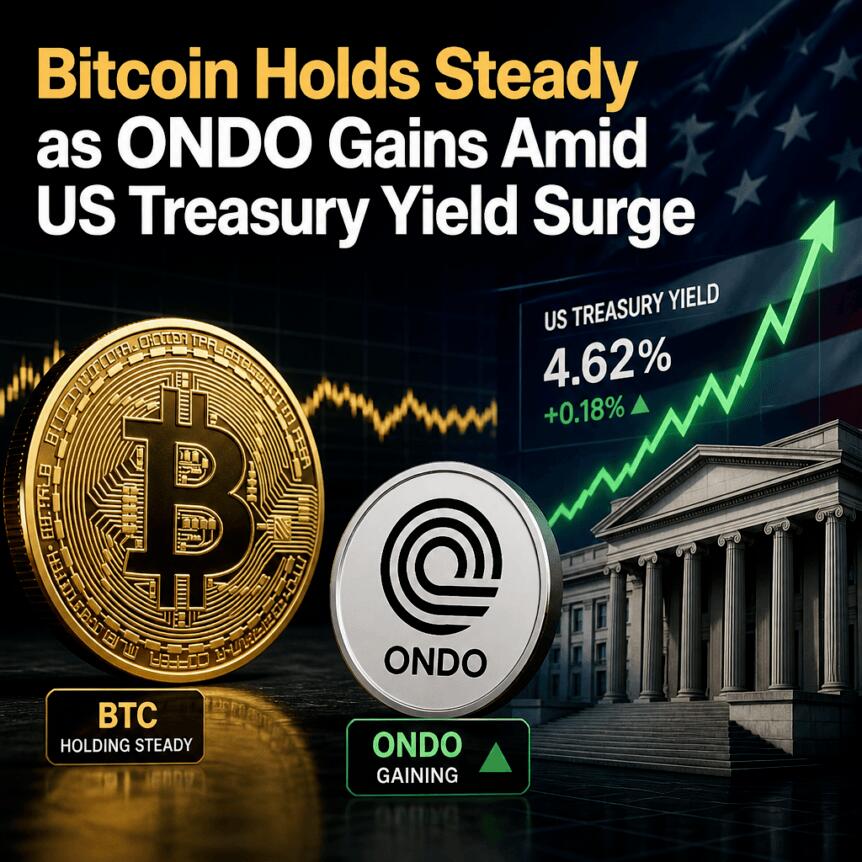
Bitcoin’s performance during US hours was marked by sharp interest-rate-driven swings, as the yield on the US 10-year Treasury note pushed to its highest level in nearly two decades. BTC briefly slipped below $83,000 before stabilizing around the mid-$84,000s, underscoring how quickly macro headlines are feeding into crypto sentiment.
Among altcoins, Ondo’s token stood out. ONDO reclaimed the $0.50 area for the first time since December 2025, moving higher as BlackRock-backed Ondo Intelligent Portfolios launched on both Ethereum and BNB Chain.
Key takeaways
- Bitcoin dipped briefly below $83,000 before attempting to regain $84,500 as US Treasury yields rose.
- The US 10-year yield reached 5.18%—its highest since July 2007—while the 30-year yield hit 5.46%.
- ONDO returned to $0.50, supported by the launch of BlackRock-linked Ondo Intelligent Portfolios.
- The new Ondo offering supports non-US users and deploys portfolio settlement via CoW Protocol and CoW DAO.
- FX pressure in Japan, highlighted by a prominent macro voice, adds another layer of risk to Treasury-market sensitivity.
Treasury yields rise again as BTC struggles to hold key levels
Thursday’s volatility aligned closely with a renewed move higher in US bond yields. According to TradingView data cited in the report, the 10-year Treasury yield rose more than 4 basis points to 5.18%, the highest level since July 2007. The 30-year yield also climbed to 5.46%, reclaiming highs last seen in 2004.
One catalyst mentioned for the day’s bond-market dynamics was a scheduled US Treasury buyback of up to $6 billion in bonds maturing in roughly 20 to 30 years—part of a broader effort to improve liquidity in long-dated debt markets. Even with that planned operation, yields still pushed higher, reflecting persistent demand for safety assets at higher return levels rather than easing conditions for risk markets.
Higher yields tend to pressure non-yielding assets like Bitcoin by increasing the opportunity cost of holding risk. However, the report also notes that BTC has continued its August rally and has challenged earlier bearish expectations tied to Bitcoin’s traditional four-year cycle.
Japan’s yen weakness could feed back into US yields
Beyond the US, the article points to growing sensitivity in international bond and currency markets. It notes that global bond markets weakened while the Japanese yen faced renewed pressure.
Mohamed A. El-Erian, president of Queen’s College Cambridge, wrote on X that the yen has weakened back toward 159 per US dollar and is approaching a zone where FX intervention has historically occurred. He added that Japanese foreign exchange intervention often involves selling US securities to buy yen, which could in turn add yield pressure to a Treasury market already described as sensitive.
For crypto traders, this matters because currency-driven moves can reinforce rate volatility. If intervention risks rise, the knock-on effect can be higher US yields, tighter financial conditions, and renewed caution toward assets that compete with yields for capital.
ONDO rebounds to $0.50 as Ondo Intelligent Portfolios go live
While Bitcoin traded in a narrow but uneasy band, ONDO showed a clear bid. CoinGecko data cited in the report indicates ONDO rose back to the $0.50 level in the last 24 hours, a psychologically important break as the token hadn’t traded there since December 2025.
The rally came despite political uncertainty around the US cryptocurrency regulatory environment, with the article referencing the failure of the CLARITY Act to pass a procedural vote in the US Senate. (That development can influence broader risk appetite, even if it is not directly tied to tokenized-real-world-assets.)
More directly, ONDO’s move was tied to a product launch: the report says BlackRock-backed Ondo Intelligent Portfolios started trading on Thursday. It also highlights the positioning of the offering: while many tokenized real-world asset products focus on tokenizing individual stocks or commodities, this new structure is designed to let non-US users purchase tokenized shares in diversified portfolios.
Ethereum and BNB Chain deployment, with settlement via CoW Protocol
The article specifies that the Ondo Intelligent Portfolios tokens went live on both Ethereum and BNB Chain. Settlement is handled through CoW Protocol and CoW DAO, per a statement attributed to CoW’s X account.
Three portfolio tokens were named as tracking model strategies developed by BlackRock for Ondo: BLKHIon (High Income), BLKDIGon (Diversified Growth), and BLKGRWon (High Growth). The launch ties ONDO’s near-term narrative to demand for regulated-style portfolio access rather than single-asset tokenization alone—an important distinction for investors watching the RWA sector’s maturation.
For ONDO holders, the market impact to watch is whether this product-driven momentum can sustain beyond the initial listing effect. RWA tokens can be sensitive to onboarding and liquidity conditions, so traders often look for follow-through in volume and sustained trading activity after the first days of a launch.
Looking ahead, investors should monitor whether rising Treasury yields persist after the recent move to 5.18% on the 10-year, and whether yen weakness continues to escalate FX-intervention risk. On the RWA side, the key question is how quickly Ondo Intelligent Portfolios build traction with non-US users and whether Ethereum and BNB Chain liquidity supports durable demand for the $0.50 reclaim.
DoubleZero has launched a dedicated market data feed for Hyperliquid, giving professional trading firms access to the decentralized exchange’s full order book over fiber rather than through its public APIs.
The feed includes Hyperliquid’s native perpetual futures and markets operated by trade[XYZ], which uses Hyperliquid’s infrastructure to offer perpetual contracts tied to assets including oil, gold and silver. The Hyperliquid feed was developed with validator operators and ecosystem partners including Hyperion DeFi, MAVAN and Kinetiq.
DoubleZero said the service delivers a continuous, ordered stream of market data for market makers, quantitative trading firms, and proprietary trading firms that need faster, more consistent order book updates.
Previously, firms seeking a complete view of Hyperliquid’s order book had to assemble the data themselves through public API responses or operate their own Hyperliquid nodes. DoubleZero said changes to Hyperliquid’s public APIs have reduced the frequency and depth of updates available through them.
DoubleZero operates a global fiber network designed to move data quickly between participants in blockchain networks and other distributed systems. Hyperliquid is the third venue available through its Edge market-data service, following Solana and prediction market Kalshi.
Related: Bitwise launches first Lighter ETP amid Hyperliquid rivalry
Onchain market infrastructure starts to resemble traditional exchanges
Hyperliquid’s market data infrastructure is beginning to resemble what traditional electronic exchanges use as professional trading moves onchain, according to Hyperion DeFi CEO Hyunsu Jung.
Jung told Cointelegraph that CME, Nasdaq and other major exchanges distribute professional market data over dedicated networks, allowing automated trading firms to receive a consistent stream of ordered data at high speeds.
“Hyperliquid data can now be consumed through the same basic model: publish once, distribute simultaneously over dedicated fiber,” he said.
However, significant differences remain. Traditional exchanges allow trading firms to place their systems close to the infrastructure that processes trades, while Hyperliquid executes trades onchain. DoubleZero’s service only delivers market data; it does not place or execute trades for firms.
“So the convergence is not Hyperliquid becoming CME,” Jung said. “It is onchain markets adopting the market-data infrastructure that professional trading firms already use.”
“It does not eliminate latency differences,” Jung said. “A firm in Tokyo will still have a physical advantage over one in New York.”
Magazine: Kyle Samani predicts SOL flippening, claims ‘no one’ uses ETH
5 surprising attractions at GOLF’s Top 100 Resorts | Travel

Meta has unveiled an audio-only pair of smart glasses and yes, it’s quite the waste of time

Raoul Pal: “The Next 14 Days Will Create The Biggest Bitcoin Bull Run Ever”

Weekend Open Thread – Corporette.com

Weekend Open Thread: Talbots – Corporette.com

Memory prices are slowing because buyers ran out of money
Raoul Pal: “The Next 14 Days Will Create The Biggest Bitcoin Bull Run Ever”

FINANCIAL PLANNING CUMA BUAT ORANGKAYA? #shorts #gajiumr #financialplanning #upgradeskill #motivasi

BTC $70K vs $100K: Can the 200MA Stop Bitcoin Again
-
 Fashion6 days ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech4 days ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Crypto World2 days ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-

 Crypto World4 days ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-

 Crypto World6 days ago
Circle launches Arc Studio AI agent for building onchain apps
-

 Fashion11 hours ago
8 iPhone Accessories That Add Personality
-

 Crypto World7 days ago
Mortgage and refinance interest rates today, Thursday, September 17, 2026
-
 NewsBeat6 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World6 days ago
Trading Bitcoin on Robinhood? Why 2% Spread Has Traders Worried
-

 Crypto World6 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Business4 days ago
Analog Devices (ADI) Bets $1.35 Billion on Chips that Let Machines Think for Themselves
-

 Tech3 days ago
Google’s $899 Googlebook is a bet that you’ll buy a new laptop for Gemini
-

 Tech5 days ago
Trump suggests rebranding AI with a new name, says he’s also creating an AI Force
-

 Crypto World4 days ago
Coinbase, Robinhood, Circle Seen as Tokenized-Stock Winners
-

 Tech7 days ago
GPT-6 Astra Reached the Nether in Minecraft, Lost Its Stash to a Creeper, and Farmed Potatoes for Hours
-
 Business2 days ago
Oil Price Today (September 23): Crude oil below $100 on hopes of US-Iran talks. What did Trump say?
-

 Crypto World6 days ago
World Money launches in 150+ countries with Stripe
-

 Crypto World6 days ago
Silver prices recover quickly, hitting weekly high today
-

 Crypto World2 days ago
Trump-Xi Polymarket Odds for Handshake Hit 50%
-

 Crypto World23 hours ago
Bitcoin Threatens Sub-$84,000 Breakdown as Long Liquidations Spike
You must be logged in to post a comment Login