
Crypto World
Zcash Launches First European ETP After US ETF Approval

21Shares has expanded its European ETP lineup with two physically backed products—one linked to Zcash (ZEC) and another tied to Ether.fi’s ETHFI token. The Zcash launch marks the first exchange-traded product in Europe specifically offering exposure to the privacy-focused coin through regulated market infrastructure.
On Tuesday, the firm listed its physically backed Zcash ETP on Euronext Paris and Amsterdam, enabling investors to obtain ZEC exposure via traditional brokerage accounts without directly holding the cryptocurrency. In parallel, 21Shares introduced a physically backed ETP tracking ETHFI, the governance and utility token of Ether.fi, also trading on Euronext Paris and Amsterdam.
Key takeaways
- 21Shares launched Europe’s first Zcash-linked physically backed ETP on Euronext Paris and Amsterdam.
- A second new product tracks Ether.fi’s ETHFI token, also in physically backed form on the same venues.
- Both ETPs charge a 2.5% annual management fee—significantly higher than many comparable European crypto products focused on bitcoin and ether.
- The expansion follows the U.S. debut of a Grayscale Zcash ETF trading on NYSE Arca under ticker ZCSH, underlining growing institutional reach for ZEC.
Regulated access for Zcash in Europe
ETPs have become a common route for institutional and retail investors to access crypto exposure within traditional market frameworks. By listing a physically backed Zcash ETP, 21Shares is effectively bringing ZEC into that ecosystem on two major Euronext markets: Paris and Amsterdam.
The listing structure is straightforward: rather than using derivatives or synthetic exposure, a physically backed ETP is designed to hold the underlying asset. For investors, that can simplify operational considerations—especially for those who prefer not to self-custody or manage direct exchange and wallet logistics—while still accessing ZEC exposure through a broker.
However, the economics matter. The 2.5% annual management fee is well above the level charged by many bitcoin and ether ETPs in Europe, which could influence investor demand—particularly for those assessing total cost over time rather than only near-term price momentum.
ETHFI ETP broadens the theme beyond privacy coins
Alongside the Zcash product, 21Shares launched an ETP tracking ETHFI, the token associated with Ether.fi, a decentralized finance protocol offering staking and other crypto-based financial services. Like the Zcash offering, the ETHFI ETP is physically backed and trades on Euronext Paris and Amsterdam.
This second listing signals that 21Shares is not only focused on privacy-coin exposure. Instead, it is also adding a product tied to the broader DeFi ecosystem—where token value is often linked to participation in protocol services such as staking, governance, and network activity. For investors, that creates a choice between two different “entry points” into crypto themes: privacy-focused infrastructure on the one hand, and DeFi utility on the other.
As with the Zcash ETP, the 2.5% annual fee also sets a notable baseline. Traders and long-term holders will likely weigh that ongoing cost against expected volatility and the pace at which token fundamentals can change in DeFi markets.
Zcash’s surge renews Bitcoin comparisons
21Shares’ decision to launch the Zcash ETP arrives amid a renewed spotlight on the coin after a strong market run. According to CoinMarketCap data cited in the original reporting, Zcash recently pushed above $1,500 and has gained nearly 1,100% over the past year.
That performance has pulled Zcash back into debates about whether it can operate as more than a niche privacy asset. In particular, renewed attention has returned to the idea of Zcash acting as a potential alternative to bitcoin—an argument that has appeared in past discussions around network effects and long-term survivability.
Grayscale head of research Zach Pandl has previously argued that Zcash could benefit from “second-mover advantages” that might help it overcome bitcoin’s entrenched network effects, according to earlier commentary covered by Cointelegraph. The broader question for investors is whether Zcash can convert price momentum into durable demand from institutional channels—especially as more regulated products become available.
At the same time, the existence of institutional ETP and ETF wrappers does not automatically solve underlying adoption challenges. For privacy-focused networks, sustainability often depends not only on price cycles but also on ecosystem growth, developer activity, liquidity depth, and regulatory treatment across jurisdictions.
Institutional momentum: U.S. ETF and ongoing mining activity
Europe’s new Zcash ETP follows a related development in the U.S. Earlier coverage highlighted the launch of a Grayscale Zcash ETF that trades on NYSE Arca under the ticker ZCSH, described in the original reporting as arriving after U.S. regulatory approval.
Taken together, a U.S. exchange-traded product plus the arrival of a European ETP suggests Zcash is increasingly on the radar of asset managers that focus on regulated access. That shift matters because it can widen the investor base—particularly among participants who may face internal constraints on direct cryptocurrency ownership.
There are also signals of scale within the network’s proof-of-work ecosystem. Fortitude Digital Mining told Cointelegraph that it mined about 28% of all ZEC produced in the first half of 2026, framing its focus on Zcash around its proof-of-work model, capped supply, and privacy features. While such statements do not directly determine price, they can be relevant to how investors think about network participation and the operational depth behind the asset.
For now, investors should treat the product rollout as a step forward in access rather than a guarantee of sustained outperformance. The key variable will be whether higher-cost ETP structures—especially with a 2.5% fee—can attract steady flows as the market digests Zcash’s recent rally.
Looking ahead, readers should watch how trading volumes and inflow dynamics develop for both of the new Euronext listings, and whether Zcash’s institutional exposure continues to broaden after the U.S. ETF addition—alongside any further clarity on long-term catalysts for ZEC that go beyond price momentum.

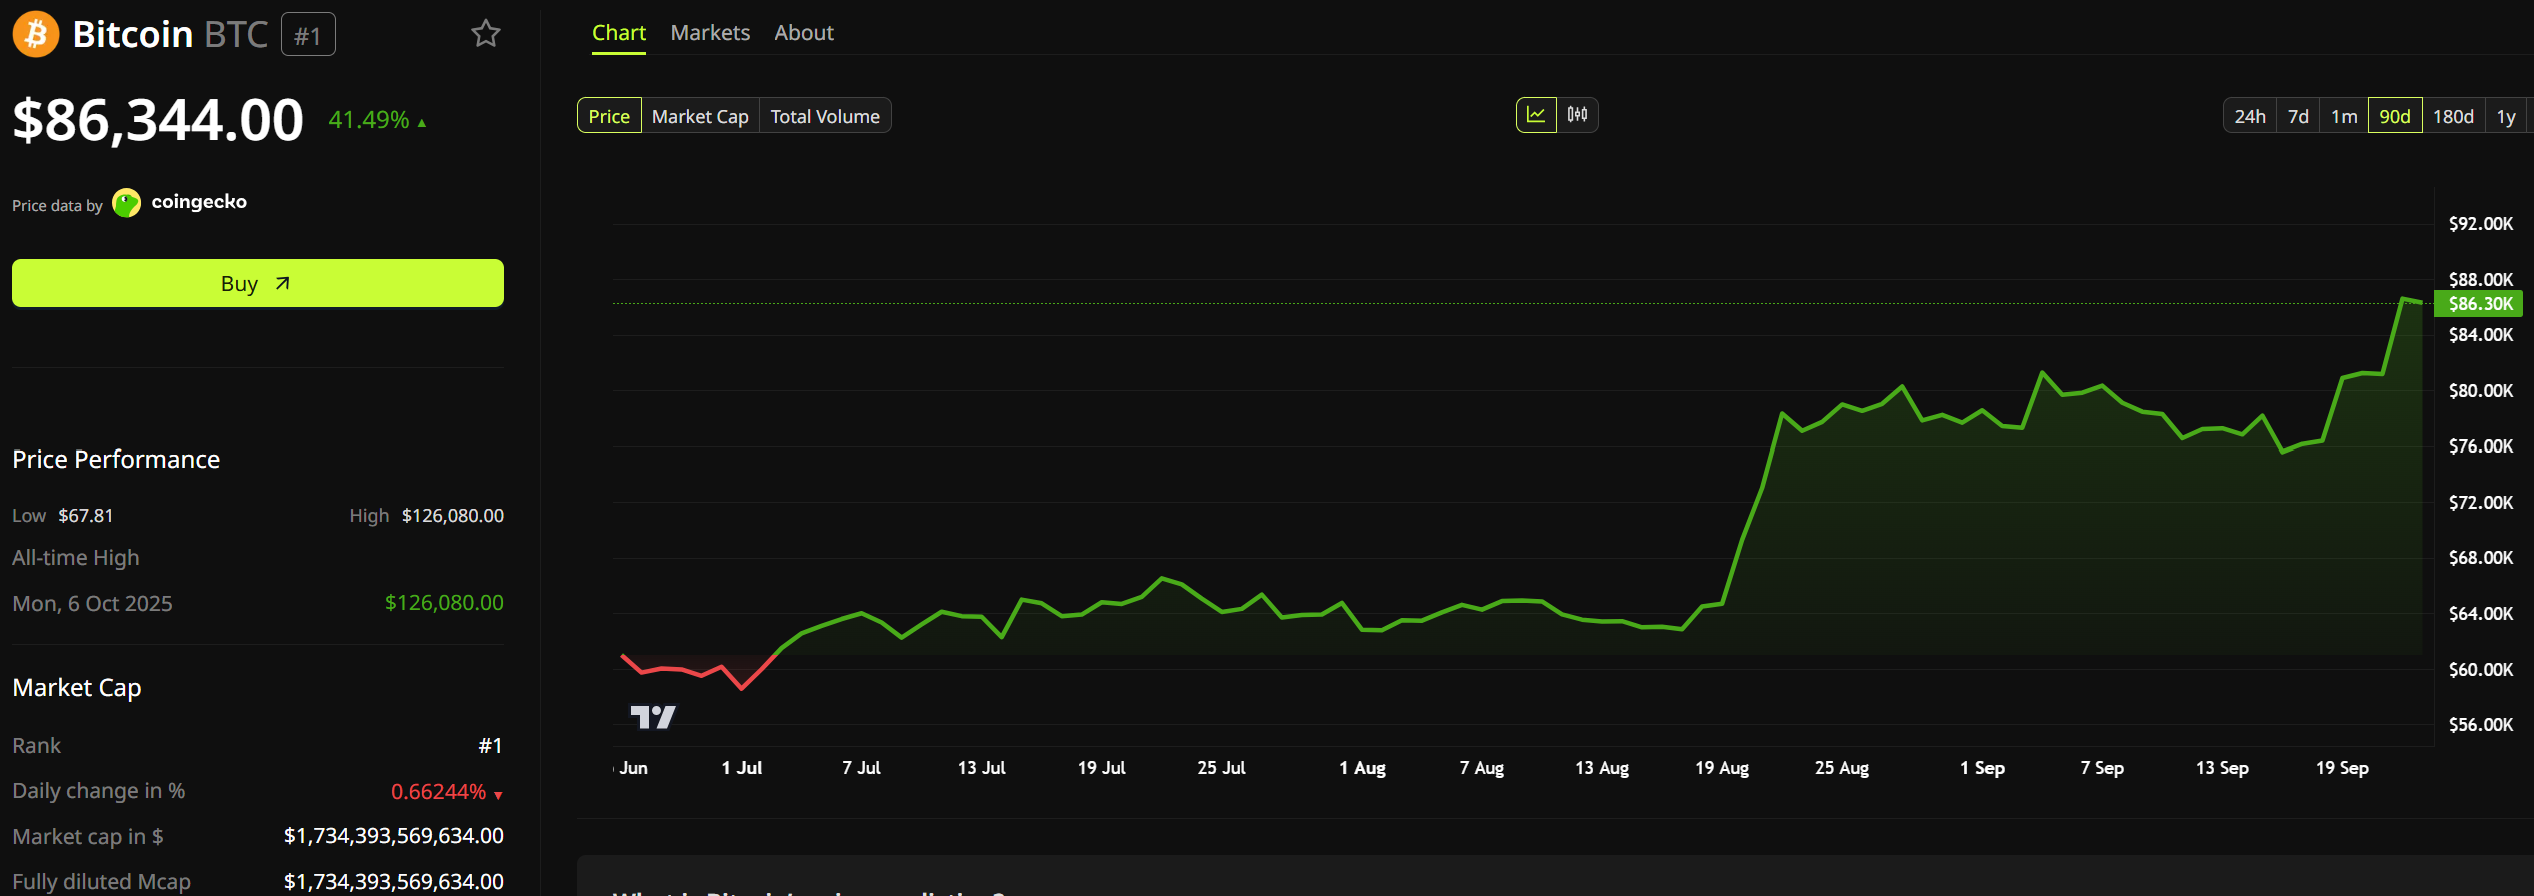
Bitcoin (BTC) traded at $86,423 on Tuesday, up from below $76,000 a week ago. Tom Lee and iTrustCapital’s CEO, Kevin Maloney, say the worst is now behind investors.
Both men made their case after a US interest rate hike and a failed crypto bill, the CLARITY Act. Neither event stopped the pioneer crypto’s rebound.

iTrustCapital CEO Says the Crypto Winter Is Over
Maloney runs iTrustCapital, a platform for crypto and stock investing in retirement accounts. In an interview with Paul Barron, he said the long crypto slump, often called the “crypto winter,” had ended.
His firm was holding about $350 million in idle client cash, Maloney said. He added that “significant portions” were now being invested again.
“Bitcoin doesn’t need Clarity Act,” Maloney said in the interview.
Maloney also named a level to watch. A weekly close above $85,000, he said, would leave Bitcoin in a good position.
Tom Lee Says the Fed Cannot Get More Hawkish
Elsewhere, Fundstrat Capital chief investment officer Tom Lee sees the rate hike as a peak, not the start of a squeeze. He has made that call repeatedly this month.
In his weekly update, Lee pointed to a change in how the government measures inflation, due September 30. He said economists expect it to cut the Personal Consumption Expenditures (PCE) inflation rate, the Fed’s preferred gauge, from 3.4% to near 3%.
“They can’t get any more hawkish than this,” Tom Lee stated.
Lee added that even one more 0.25-point hike would not break the economy or the stock market.
Their Remarks Come After Two Setbacks in One Week
On September 15, the CLARITY Act failed a Senate procedural vote 50-49, short of the 60 needed. The bill would have set out which US regulator oversees digital assets.
A day later, the Federal Reserve raised its benchmark rate by 0.25 percentage points to a 3.75% to 4% range. It was the first increase since 2023. Bitcoin slipped below $76,000 after the vote. It has since recovered.

Fed Projections and ETF Outflows Point the Other Way
Not every signal agrees. Sixteen of 18 Fed officials expect another hike this year, according to the central bank’s projections.
Investors also pulled $450 million from Bitcoin exchange-traded funds (ETFs) on September 15, according to ETF fund flow figures.
Bitcoin sits 0.6% higher on the day, BeInCrypto price data shows. The next test arrives September 30, when the revised inflation figures land.
The post Tom Lee and iTrustCapital CEO Say the Worst Is Over: Can Bitcoin Hold $86,000? appeared first on BeInCrypto.
Crypto World
Democrats ‘chose visceral hatred for’ Donald Trump over crypto Clarity Act, Lummis says
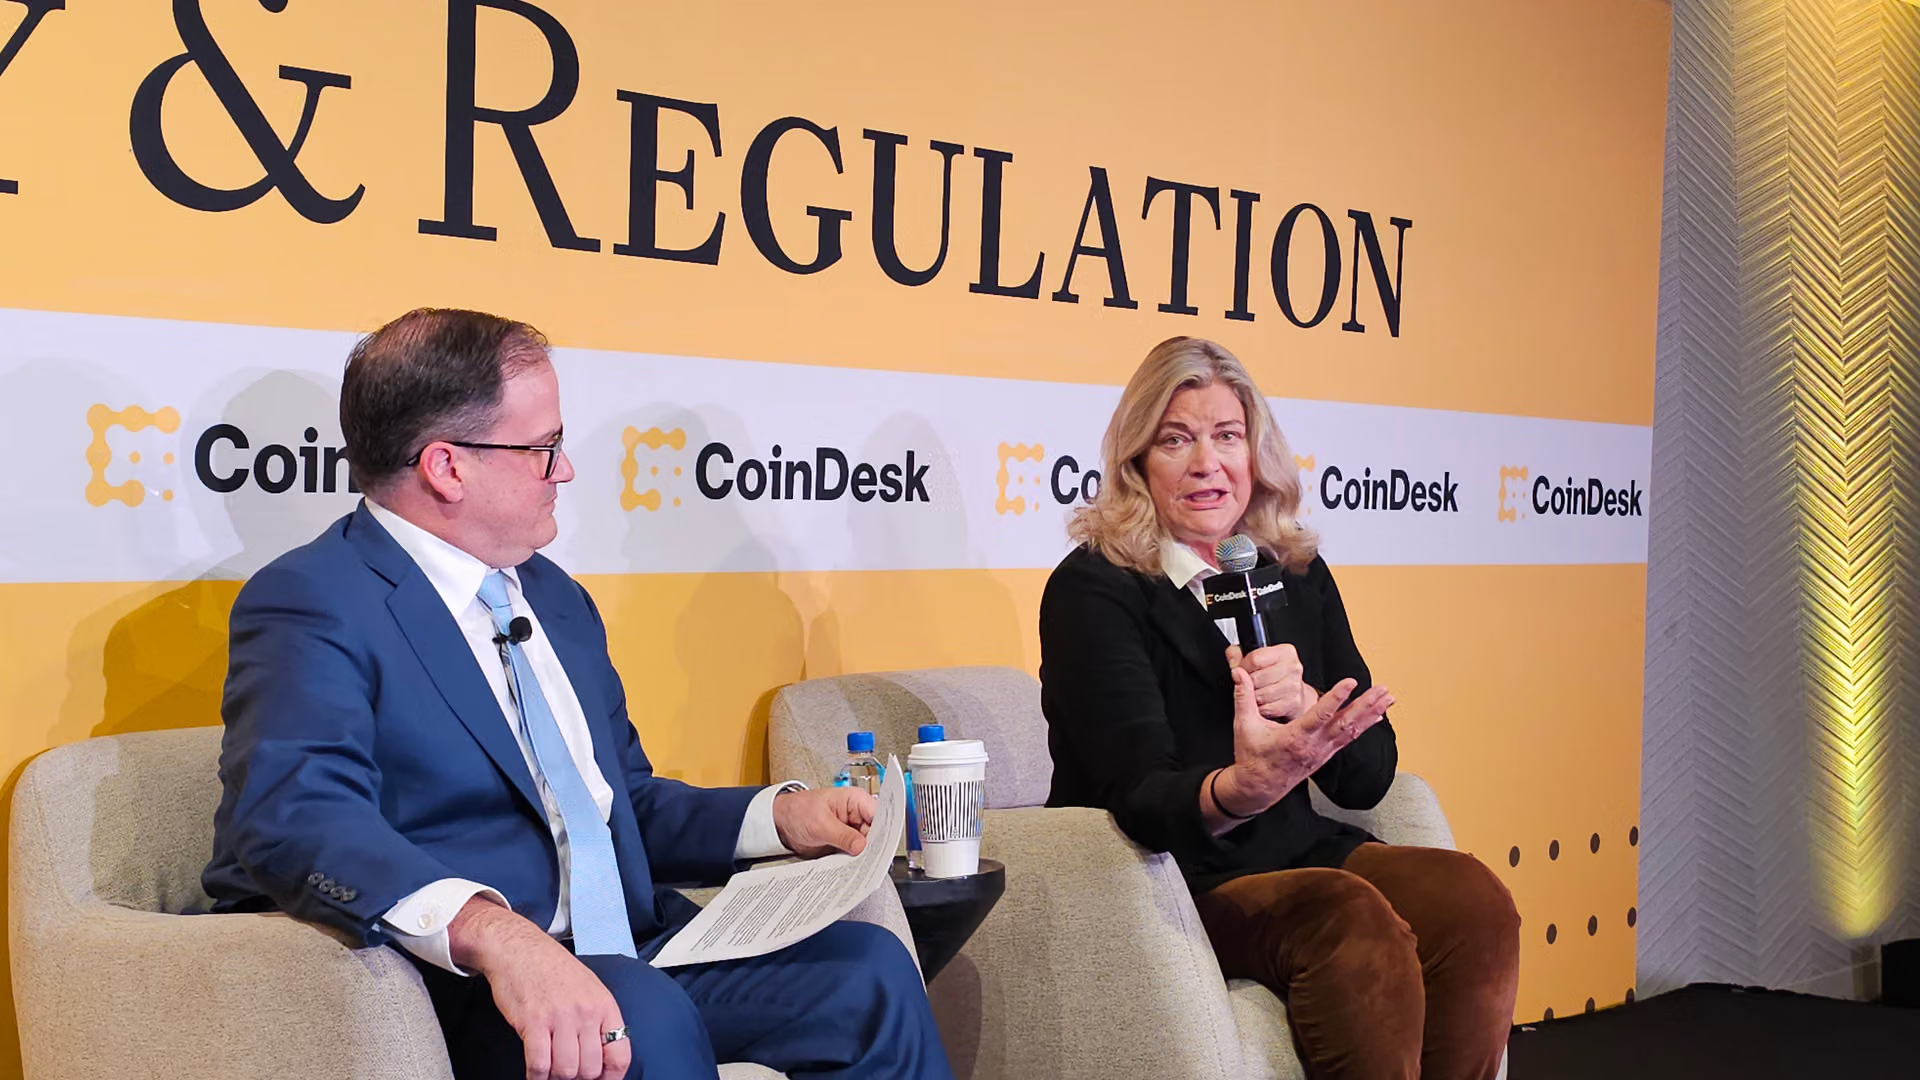
WASHINGTON, D.C. — Senator Cynthia Lummis said she was “dismayed, dumbfounded and saddened” that the Senate couldn’t advance a key procedural vote for crypto market structure legislation last week.
Lummis blamed Democrats for the bill’s failure at an appearance Tuesday at CoinDesk’s Policy & Regulation event, saying that while the bill was the result of negotiations between members of both parties.
“The problem was, as I see it, Democrats hate President [Donald] Trump more than they like good policy, and the way I see it is they chose their visceral hatred for President Trump and denied the opportunity to pass important policy legislation before a midterm,” she said. “They chose that … pin it on the Democrats.”
The bill itself was a bipartisan product which grew from some 300 pages to over 600, she said, after Democrats asked for provisions addressing issues like bankruptcy protections, among other items.
After overseeing 150-year-old insurance giant MetLife’s multi-year, $3.2 billion modernization initiative, Bill Pappas turned his focus to AI. In two years, the effort has moved the numbers that matter: faster claims adjudication, lower expenses, better customer experience. “AI is not technology-led; it’s CEO-led,” Pappas says. “It’s changing the way we look at efficiency, at individual productivity, and our growth.” He’s just as focused on defense: he also built a team to “use AI to protect against AI,” aware that the same tools unlocking value are dangerous in the hands of threat actors.
Pappas says his biggest lesson in managing a workforce spanning five generations in the AI era came from an unexpected place: climbing Mount Kilimanjaro with his two adult daughters. He had a fixed process in mind; they improvised better than he did. “This whole thing is about learning, unlearning, and relearning,” he says. It’s the mindset he now encourages among his more than 38,000 technology and operations staff.
Crypto World
Trump Administration to Cancel Obamacare Coverage for 760,000 Enrollees Over Alleged Fraud
A poll conducted by health policy research group KFF in June found that most voters believe there is at least some fraud in government health programs, and that more than 70% feel it is an extremely or very important issue for candidates to discuss ahead of the midterm elections. For Republican voters, fraud topped all health care issues asked about in the survey, including costs.
But health care costs, which have become increasingly expensive in the U.S. in recent years, weighed more significantly for voters overall, and the poll found that only a minority of those surveyed believed that reducing fraud in government programs would reduce such costs for them personally.
Amid the Trump Administration’s moves to withhold millions in Medicaid payments, 71% also voiced the belief that preserving access to coverage through the insurance program was more important than rooting out fraud. Meanwhile, 65% believed that the Administration’s Medicaid payment deferrals were mostly politically motivated.
Prometheum has detailed how international investors would hold, redeem, and receive legal protection for tokenized US stocks under a proposed distribution arrangement involving HashKey and Velocity Capital.
Summary
- Cede & Co. would remain the registered owner of the underlying shares held at DTC.
- International customers would receive securities entitlements protected under UCC Article 8.
- Investors could convert their tokens into conventional shares or sell their positions for cash.
- The proposed pilot remains subject to final agreements, regulatory clearance and technical integration.
Tokenized US stocks will use existing ownership rules
Prometheum co-CEO Aaron Kaplan told crypto.news that the proposed structure would operate through the indirect holding system established under Article 8 of the Uniform Commercial Code, rather than making each tokenholder the registered shareholder on a company’s official books.
Cede & Co., the nominee used by the Depository Trust Company, would remain the registered owner of the underlying shares. Kaplan said tokenization would not change that arrangement, which is already used for nearly all publicly traded US equities held through brokerage accounts.
Within the planned structure, the participant connected to a registered blockchain wallet would hold the securities entitlement. Acting as a securities intermediary, the participant would then treat its customer as an entitlement holder under Article 8.
“The Token itself does not create or define the customer’s ownership interest,” Kaplan said.
According to Kaplan, the customer’s rights would instead come from the participant’s duties under Article 8, the Securities and Exchange Commission’s Customer Protection Rule and the Securities Investor Protection Act. Each protection would apply independently of the blockchain used to represent the position.
Kaplan’s explanation draws a distinction between appearing as the registered owner and holding a legally protected interest through an intermediary. Under the proposed system, an international customer’s name would not replace Cede & Co. on the issuer’s official shareholder record, but the customer would have an entitlement through the regulated custody chain.
A recent ownership review found that blockchain records alone do not turn stock-linked tokens into legal shares. The legal structure can instead give an investor a direct or beneficial interest in a security, a custodial claim, or only a contract tied to its market price.
The structure differs from synthetic and SPV products
Kaplan said synthetic or special-purpose vehicle structures place investors in a different legal position because an offshore entity may own the conventional shares while a customer holds only a contractual claim against that entity.
In a synthetic product, the token can track the price of a listed stock without giving its holder rights in the underlying company. An SPV-backed product may hold real shares, but the tokenholder’s claim can run against the separate legal entity rather than through the established US securities holding system.
Prometheum, HashKey Digital Asset Group and Velocity Capital intend to use shares custodied at DTC as the assets behind the proposed tokens. The companies described each token as a digital twin of a conventional security rather than a synthetic instrument or an offshore wrapper.
Kaplan said the planned model would preserve the legal protections attached to securities held through SEC-registered broker-dealers. Prometheum Capital is registered with the SEC and belongs to the Financial Industry Regulatory Authority, while Velocity is an SEC-registered, FINRA-member broker-dealer with traditional securities clearing and execution permissions.
The ownership question has also entered current US policy. Under a five-year SEC exemption announced on Sep. 17, qualifying tokenized National Market System stocks must provide the same rights as their conventional counterparts, including applicable voting, dividend, and liquidation rights. Synthetic products offering only price exposure do not qualify under the order.
As previously reported on investor rights, the SEC framework also allows an issuer to object when an unaffiliated party seeks to offer a tokenized version of its shares. The regulator can modify the temporary exemption while it considers permanent rules for onchain securities trading.
Prometheum’s arrangement concerns international distribution rather than an offer to US investors. HashKey would provide access through eligible licensed exchanges in several jurisdictions, subject to local laws, licensing terms and investor eligibility requirements.
Investors could redeem tokens through standard DTC processes
For an investor seeking to leave the blockchain-based position, Kaplan said each token could be converted into a conventional share or sold for cash through the broker-dealer. Both routes would use DTC’s standard securities processes because the corresponding shares would already sit within its custody system.
“Each token is a digital twin of a share already held at DTC, and investors can convert the token position back into a conventional share or sell it for cash through the broker-dealer, using DTC’s standard processes,” Kaplan said.
Dividends, stock splits and other corporate actions would also move through the same DTC channels used by the US securities market, according to Kaplan. His comments did not set out separate procedures for voting or for processing corporate actions when a token trades outside regular US exchange hours.
In the event of a broker-dealer failure, Kaplan said SEC Rule 15c3-3 would require customer securities to remain separate from the firm’s own property. Segregated shares could then be returned to customers rather than becoming part of the failed company’s estate.
SIPA provides another layer of protection within the US broker-dealer system, although the proposed international distribution chain would also involve HashKey exchanges operating under the rules of their respective jurisdictions. The binding memorandum does not itself establish the treatment of customer claims under every participating country’s insolvency law.
Traditional market infrastructure has begun supporting other tokenized investment products. On Sep. 16, Ondo Finance subsidiary Oasis Pro Markets joined DTCC’s Fund/SERV, becoming the first tokenization platform admitted to a network that processes more than 85% of US mutual fund transaction activity.
Oasis Pro, like Prometheum Capital and Velocity, operates through US securities registrations. Its Fund/SERV connection supports transaction processing and distribution, while the legal rights attached to each product still depend on its custody and ownership structure.
HashKey would distribute the securities internationally
Under the MOU, HashKey would act as the international distributor through eligible exchanges within its licensed network. Prometheum Capital and Velocity would provide the custody, trade execution, and clearing services needed to connect the token positions with conventional securities held in the United States.
“Through this collaboration, eligible clients in multiple jurisdictions will have the opportunity to access tokenized U.S. equities supported by SEC-registered clearing infrastructure, subject to applicable laws and regulatory requirements,” HashKey CEO Xiao Feng said.
HashKey has already entered DTCC’s digital-assets work. Earlier in September, the company joined its industry group after DTC completed initial production transactions involving tokenized equities, exchange-traded funds and Treasury products in July.
Velocity CEO Roy Yan said the underlying shares would need to be executed, cleared and held according to the same standards used in regulated US equity markets. Velocity holds memberships with DTC, the National Securities Clearing Corporation and the Options Clearing Corporation.
The proposed product list could include companies in the Russell 1000, which covers the 1,000 largest publicly traded US companies by market value. ETFs tracking major indexes and US Treasury bills, notes and bonds could also qualify.
DTC has said its tokenized assets will carry the same ownership rights, investor protections and entitlements as securities held in conventional form. DTCC scheduled the full launch of its Tokenization Service for October 2026 after conducting limited production transactions in July, and the organization said DTC held more than $114 trillion in assets when it announced the program’s timetable.
Prometheum, HashKey and Velocity are still selecting the securities and jurisdictions for the initial pilot, Kaplan said. A launch requires definitive agreements, regulatory approval, completed technical and operational integration, relevant licenses and the availability of DTCC’s tokenization infrastructure.
The European Central Bank and the EU’s 27 national central banks have asked regulators to replace MiCA’s 30% and 60% bank-deposit floors for stablecoin reserves with maturity-based liquidity requirements.
Summary
- MiCA requires regular stablecoin issuers to hold 30% of reserves in commercial bank deposits.
- The bank-deposit requirement rises to 60% for stablecoins classified as significant.
- European central banks said large redemptions could transmit stress from stablecoins to commercial lenders.
- Tether CEO Paolo Ardoino warned about the same reserve structure in 2024.
The European System of Central Banks said in its response to the European Commission’s MiCA consultation that stablecoin issuers should not have to place a fixed share of their reserves in bank deposits.
Instead, the ESCB recommended setting minimum proportions for reserve assets that mature within one working day and five working days. Such a model would focus on how quickly an issuer can access its reserves during redemptions rather than how much money it keeps at commercial banks.
MiCA currently requires issuers to hold at least 30% of their reserves as bank deposits. For issuers whose tokens receive the “significant” classification, the requirement rises to 60%.
“If reserves are held as bank deposits, stablecoins can alter banks’ funding structures by replacing relatively stable retail deposits with deposits from stablecoin issuers, which tend to be less stable and more sensitive to market conditions,” the central banks said in their response, according to Reuters.
MiCA deposit rule could transmit redemption stress
Under the existing model, a stablecoin issuer may receive money from customers and place the required portion with one or more commercial banks. A rush to redeem tokens could then force the issuer to withdraw a large amount of those deposits within a short period.
The ESCB said such withdrawals could expose commercial lenders to a stablecoin run because deposits from token issuers behave differently from ordinary household deposits. Issuer deposits may leave quickly when crypto markets face stress or token holders seek redemptions.
While drafting MiCA, EU policymakers treated bank deposits as a source of readily available liquidity. An ECB study published in April said a significant stablecoin issuer could meet redemptions equal to as much as 60% of its supply by drawing down deposits without immediately selling sovereign bonds.
The same study also identified a second risk: withdrawals during a stablecoin run could pass financial stress into the banking system. Deposits may protect bond markets from forced sales at first, according to the ECB, while placing the commercial banks holding the money under pressure.
MiCA’s reserve design has already affected which stablecoins European exchanges can support. As crypto.news reported in July, USDT lost access to regulated EU exchange order books after Tether declined to seek authorization under the framework.
Coinbase Europe removed USDT in December 2024, followed by Crypto.com in January 2025. Binance restricted European USDT trading pairs in March 2025, while Kraken moved the token to a sell-only model before ending support.
Tether flagged MiCA reserve risk in 2024
More than two years before the ESCB response, Tether CEO Paolo Ardoino argued that MiCA’s deposit floor could expose stablecoin holders to failures at commercial banks.
In an August 2024 interview with Wired, Ardoino used a hypothetical €10 billion stablecoin to explain his concern. Under the 60% requirement, an issuer would need to place €6 billion with banks, which could then use much of the money for lending.
“Imagine a customer asks to redeem €2 billion [worth of stablecoin], but the bank has only €600 million,” Ardoino said. “Then you are in a situation in which both the bank and stablecoin go bankrupt.”
Ardoino said he did not consider the structure safe and argued that it could create “additional systemic risks in Europe” instead of reducing them. His comments focused on the possibility that an issuer could lose access to uninsured deposits precisely when token holders request large redemptions.
Several months earlier, in April 2024, Ardoino had pointed to the collapse of Silicon Valley Bank as evidence of the risk attached to uninsured deposits. Circle’s USDC temporarily lost its dollar peg in March 2023 after the company disclosed that $3.3 billion of its reserves were held at the failed bank.
“Uninsured cash deposits are not a good idea,” Ardoino wrote. “If a bank goes bankrupt, uninsured cash goes into bankruptcy.”
Calling for issuers to be allowed to keep all reserves in Treasury bills, Ardoino argued that securities would return to their legal owner following a bank failure. Tether has kept much of USDT’s backing in U.S. Treasury securities rather than adopting MiCA’s European bank-deposit model.
The company later said it would reconsider a MiCA application only when the framework became safer for issuers and consumers. European restrictions have continued in the meantime, with OKX Europe opening a one-way conversion route in July for customers moving from USDT into MiCA-authorized USDC.
MiCA review gives regulators a route to amend reserves
The ESCB submitted its recommendation through the European Commission’s review of MiCA, which began with a public consultation on May 20 and accepted responses through Aug. 31.
According to the Commission, the review sought input from token issuers, crypto service providers, financial institutions, technology companies, academics, industry groups and public authorities. Officials are examining whether MiCA remains suitable after changes in digital-asset markets and international regulation.
Feedback will inform a report required under Articles 140 and 142 of MiCA. The Commission could attach a legislative proposal if it decides that the regulation needs amendments, as previously covered in a report on the planned MiCA review in 2027.
Stablecoin reserve rules are not the ECB’s only focus. A separate paper published in September called for the current prohibition on issuer-paid stablecoin interest to cover rewards offered through affiliated exchanges, lending products and staking services. The proposal to expand the yield ban addresses returns paid to users, while the latest ESCB recommendation concerns the assets held against tokens.
U.S. rules allow deposits and Treasury securities
For U.S. token holders, the dispute provides a direct comparison with the reserve system created by the GENIUS Act, which President Donald Trump signed into law in July 2025.
The U.S. framework requires permitted payment stablecoin issuers to maintain reserves of at least one dollar for every dollar of tokens in circulation. Eligible assets include U.S. dollars, funds held at certain regulated or insured depository institutions, short-term Treasury securities, Treasury-backed reverse repurchase agreements and qualifying money market funds.
Unlike MiCA, the U.S. law does not require issuers to keep a fixed 30% or 60% of reserves in commercial bank deposits. The White House described the permitted backing as liquid assets such as dollars and short-term Treasuries, while the law also requires issuers to publish monthly reserve-composition disclosures.
The Office of the Comptroller of the Currency proposed implementation rules in February 2026. Its proposal would require issuers under OCC oversight to show that they can convert each type of reserve asset into cash, including through Treasury sales or repurchase agreements.
The ESCB also addressed stablecoins issued through connected entities inside and outside the EU. It supported the European Systemic Risk Board’s position that interchangeable multi-issuance models are not permitted under current MiCA rules and said any future authorization should require safeguards, including an assessment of whether the other country’s regulatory system is equivalent to the EU framework.
Canada’s six largest banks have formed a joint project to test transfers of tokenized Canadian-dollar deposits between regulated financial institutions.
Summary
- Six major Canadian banks will jointly explore an interbank tokenized deposit system.
- The first phase will test transfers of digital bank deposits among participating institutions.
- Tokenized deposits remain bank liabilities, unlike separately issued stablecoins backed by reserve assets.
- The Canadian project could eventually connect with other bank-led digital asset networks.
TD Bank has announced that Bank of Montreal, Canadian Imperial Bank of Commerce, National Bank of Canada, Royal Bank of Canada, Scotiabank and Toronto-Dominion Bank Group will participate in the initiative. Other banks may join the project as it develops.
The lenders plan to begin with transfers of tokenized deposits among themselves, creating a common process for moving digital representations of Canadian-dollar bank balances. According to their joint statement, the first phase will focus on efficient circulation between Canadian financial institutions before any links are built to other digital asset programs.
Unlike a retail stablecoin or cryptocurrency, each tokenized deposit represents money already held at a participating commercial bank. Its value remains recorded as a liability of that bank, while digital ledger technology provides the infrastructure for transferring or programming the deposit.
Tokenized deposits could support round-the-clock bank payments
By representing conventional deposits digitally, the project could allow participating banks to process certain transfers outside the operating windows used by traditional payment systems. Programmable instructions could also release funds when agreed conditions are met, subject to each bank’s compliance and risk controls.
A shared network would address one of the limits of products operated by a single institution. When separate banks issue tokens only for their own clients, the funds may be unable to move directly to another bank’s platform without being converted or settled through existing systems.
Canada’s Big Six are instead exploring transfers between participating institutions from the project’s first phase. Their longer-term plan includes connecting the Canadian system with other digital asset programs, although the banks have not provided a timetable for testing, commercial deployment or outside access.
The initiative follows a regulatory clarification issued earlier in September. As crypto.news previously reported, Canada’s Office of the Superintendent of Financial Institutions said tokenized deposits are not legally different from conventional deposits merely because banks use blockchain or another digital system to represent them.
OSFI uses a technology-neutral approach, meaning it assesses the financial product rather than the technology used to deliver it. Banks must continue meeting the legal, operational, cybersecurity, and third-party risk requirements that apply to their existing deposit businesses.
The regulator also expects federally regulated institutions to contact their lead OSFI supervisors before introducing novel financial products or services. Its guidance points banks to the B-13 technology and cyber-risk guideline and the B-10 framework for managing outside service providers.
Canada’s tokenized deposit system differs from stablecoins
Tokenized deposits and stablecoins can both provide digital payments and programmable transfers, but their financial structures differ. A tokenized deposit remains a claim against the bank that issued it, just as money held in a conventional account remains a liability on the bank’s balance sheet.
Stablecoins are generally issued as separate tokens backed by cash, government securities or other reserve assets. Their legal status, redemption rights and regulatory treatment depend on the issuer and the rules covering the product.
Canada is developing a separate framework for fiat-backed stablecoins. The country’s 2025 federal budget included measures for a regulatory system administered in part by the Bank of Canada, with C$10 million allocated over two years beginning in 2026.
The planned rules would amend the Retail Payment Activities Act to cover payment providers handling stablecoin transactions. Bank of Canada Governor Tiff Macklem previously said stablecoins should maintain a one-to-one link with central bank currency, hold liquid government assets and give users clear information about redemption terms, costs and timing.
Canadian-dollar stablecoins are already entering regulated financial channels. In May, Anchorage Digital added institutional custody for CADD, a Canadian-dollar token issued by Tetra Digital Group and backed one-to-one by Canadian dollars held at a licensed trust company.
The Big Six project follows a different route because the participating banks would tokenize deposits they already hold instead of creating a separate reserve-backed asset. Each institution would retain responsibility for the deposit and the controls surrounding its transfer.
US banks are building a similar interbank network
Across the border, major American lenders are working on an interbank system with many of the same planned functions. In July, JPMorgan Chase, Bank of America, Citigroup and Wells Fargo were reported to be developing a shared deposit network through The Clearing House.
The U.S. project is targeting the first half of 2027 and plans to offer multinational companies programmable treasury services, real-time liquidity management and cross-border transfers. More than a dozen other financial institutions, including TD Bank, BNY, HSBC, PNC, Truist and U.S. Bank, have supported the initiative.
JPMorgan and Citigroup already operate their own digital payment systems, but a shared network would allow tokenized deposits to move between participating banks. According to the earlier report, JPMorgan’s Kinexys platform processes more than $7 billion in average daily volume and has handled over $40 trillion since its launch.
Wells Fargo has also announced a separate product for corporate and commercial clients. Its planned tokenized deposit service will initially cover selected U.S. dollar-to-British-pound transactions before adding clients, countries and currencies during 2027.
For U.S. companies operating in Canada, compatible bank-led systems could eventually provide another route for moving funds between Canadian and American financial institutions. Neither project has announced a direct connection, and the Canadian banks have not identified which outside networks they may support.
Canadian banks build on Project Samara test
Canada’s latest bank-led project also follows the completion of Project Samara in March. The Bank of Canada, Export Development Canada, RBC Capital Markets, RBC Investor Services and TD Bank tested the issuance, trading and settlement of a C$100 million tokenized bond using distributed ledger technology.
Export Development Canada issued the bond with a maturity of less than three months to a closed group of investors. The Project Samara experiment used wholesale central bank deposits for payments and managed the security on a platform built with Hyperledger Fabric.
The system supported cash and bond issuance, bidding, coupon payments, redemption, secondary trading and settlement on connected cash and securities ledgers. According to the Bank of Canada, the test allowed transactions to settle directly on the platform.
Project Samara found improvements in operational efficiency, data integrity and transaction workflows, while the central bank also identified liquidity costs, governance demands and integration problems. The experiment reduced counterparty and settlement risk but introduced technology, audit and fallback risks, according to the Bank of Canada.

South Korea’s FTC Opens Merger Review of Uber’s Bid to Acquire Baemin Owner Germany’s Delivery Hero SE

Executives of the Year: Matt Madrigal
What Makes ‘The Real Housewives’ So Addictive? An Expert Explains




-

 Fashion4 days ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech2 days ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Crypto World4 days ago
Circle launches Arc Studio AI agent for building onchain apps
-
 NewsBeat4 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World2 days ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-

 Crypto World4 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Crypto World4 days ago
Trading Bitcoin on Robinhood? Why 2% Spread Has Traders Worried
-

 Crypto World6 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 Crypto World7 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-
 Tech7 days ago
Webb’s IC 348 Mosaic Includes Two-Jupiter Dwarfs, Twin Jets, and a Nursery Still Making Worlds
-

 Crypto World5 days ago
Mortgage and refinance interest rates today, Thursday, September 17, 2026
-

 Crypto World4 days ago
World Money launches in 150+ countries with Stripe
-
 Entertainment7 days ago
Big Brother Update: Melody Explodes at Drew as Illness Sweeps BB28 House
-

 Crypto World4 days ago
Silver prices recover quickly, hitting weekly high today
-

 Business2 days ago
Analog Devices (ADI) Bets $1.35 Billion on Chips that Let Machines Think for Themselves
-

 Tech5 days ago
GPT-6 Astra Reached the Nether in Minecraft, Lost Its Stash to a Creeper, and Farmed Potatoes for Hours
-
 NewsBeat4 days ago
US was ‘on brink of war’ with China over false AI report of nukes moving in Middle East
-

 Crypto World2 days ago
Coinbase, Robinhood, Circle Seen as Tokenized-Stock Winners
-

 Crypto World2 days ago
Bitcoin price holds above $81K as key catalysts line up
-
 Business7 days ago
Federal Reserve expected to hike interest rates 25 basis points at FOMC meeting
You must be logged in to post a comment Login