Connect with us

Business

HDFC Bank share price target: What are Jefferies, 3 other foreign brokerages saying as CEO hunt intensifies?

Published

on

HDFC Bank share price target: What are Jefferies, 3 other foreign brokerages saying as CEO hunt intensifies?
HDFC Bank, India’s largest private lender, has submitted the names of two candidates to the RBI for the CEO role, formally beginning the succession process for Sashidhar Jagdishan, who is due to retire later this year. HDFC Bank shares rose 3% to Rs 727 on Tuesday.

While the lender has not named the two candidates, people familiar with the matter told The Economic Times that the bank’s deputy managing director Kaizad Bharucha and an external candidate are on the list. ICICI Prudential Life CEO Anup Bagchi and Citi India CEO K Balasubramanian are among those being considered for the external candidate slot.

Last month, Managing Director and CEO Sashidhar Jagdishan decided not to seek another term at the helm of the country’s largest private lender. Jagdishan’s current tenure ends on October 26, 2026.

Also read: HDFC CEO race: One insider, one outsider in contention for the top job

Advertisement

The bank said in an exchange filing over the weekend that its board had tried to persuade Jagdishan to continue, but he remained firm on his decision not to seek re-appointment. The development comes amid concerns over governance that began in March this year after its former part-time Chairman Atanu Chakraborty resigned, stating that some practices within the bank did not match his personal values and ethics.

What are brokerages saying?

Jefferies has retained a Buy rating and a target price of Rs 880 (24% upside) and believes a smooth leadership transition at HDFC Bank would benefit both the lender and the broader banking sector. The brokerage said the board move came at the right time and that confirming the new appointment before Jagdishan’s term ends on October 26, 2026, could ease investor concerns and reduce uncertainty’s impact on business momentum.
HDFC Bank is currently trading at 1.5x FY27E adjusted price-to-book value, around 30% below ICICI Bank’s valuation, 15% below Kotak, at par with Axis Bank and around 15% above SBI. Jefferies noted that weakness in HDFC Bank has also weighed on the performance of other banks. It believes greater clarity on the leadership transition, along with improved business momentum, could support a broader re-rating.Jefferies said its conversations with investors indicate they are comfortable with a change in leadership but believe former leaders from PSU banks should not be considered as they could complicate the transition.

The brokerage sees Kaizad Bharucha, DMD overseeing corporate, business banking and retail assets, among other areas, as a key internal candidate. Bharucha was appointed Executive Director in June 2014 and could have a tenure of 2.8-3 years in the role. Jefferies said the bank could consider having Bharucha lead the lender while preparing for a smoother transition over the longer term.

Nomura sees strong upside in HDFC Bank shares

With a Buy rating and a target price of Rs 950 (34% upside), Nomura believes a possible internal appointment of Kaizad Bharucha could provide initial relief by ensuring continuity and limiting disruption at HDFC Bank. His familiarity with the bank and its businesses could also facilitate a smoother transition, the brokerage said. However, it noted that a credible external candidate could provide a longer runway and a cleaner slate.

Advertisement

Nomura says an external appointment could have greater significance for the stock over the medium term, as a new leader would have more scope to reassess strategy, challenge existing practices and drive a strategic reset. With HDFC Bank having materially underperformed, the brokerage said a credible external candidate with a strong operating track record could act as a catalyst for a re-rating, particularly if accompanied by a clear roadmap for growth, deposits, margins and returns.

Read more: HDFC Bank shares hit 52-week lows over consecutive sessions while analysts scream Buy

Bernstein, Macquarie sees over 60% upside in HDFC Bank stock

With a price target of Rs 1,150, Bernstein retains its Outperform rating on HDFC Bank. The brokerage noted that HDFC Bank’s board has proposed elevating Jimmy Tata to the position of whole-time director and increasing the total number of board seats to four, according to ET Now.

Bernstein added that the leadership succession timeline remains on track ahead of the current CEO’s retirement.

Advertisement

Macquarie maintained its Outperform rating on HDFC Bank with a target price of Rs 1,150 per share, implying more than 62% upside from the stock’s previous closing price. The brokerage said the appointment of an external CEO is being viewed as the key catalyst for a re-rating of HDFC Bank’s stock.

Who will become the new HDFC Bank CEO?

Jefferies said potential external candidates could include Anup Bagchi, currently CEO of ICICI Pru Life and previously an Executive Director at ICICI Bank overseeing retail banking; Paresh Sukthankar, who was earlier DMD at the bank before exiting in 2018; Vibha Padalkar, CEO of HDFC Life; Aseem Dhru, former HDFC banker and former CEO of SBFC; Rajiv Sabharwal, currently CEO of Tata Capital; and Amitabh Chaudhry, CEO of Axis Bank.

The brokerage said its conversations with investors suggest they are comfortable with a change in leadership, but believe the appointment of former leaders from PSU banks should be avoided as it could complicate the transition.

HDFC Bank share price performance

Stock market heavyweight HDFC Bank shares have been hitting fresh 52-week lows for several consecutive sessions, even as analysts continue to maintain their Buy ratings after the stock has fallen around 29% so far in 2026.

Advertisement

India’s largest private sector lender slipped to a fresh 52-week low of Rs 681.90 apiece on Friday, taking the decline to more than 33% from its record high of Rs 1,020.50 apiece touched in October last year.

HDFC Bank has been the worst-performing constituent of the Nifty Bank index this year. The weakness has not been limited to the current year, with the lender’s shares also delivering poor returns over the past three and five years, declining nearly 14% and 9%, respectively.

Disclaimer: This article has been written by Veer Sharma, who is not a SEBI-registered Research Analyst or an Investment Adviser. Veer Sharma and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.

Advertisement
Continue Reading
Click to comment

You must be logged in to post a comment Login

Leave a Reply

Business

Spiceology’s winning flavor strategy | Food Business News

Published

on

Spiceology’s winning flavor strategy | Food Business News

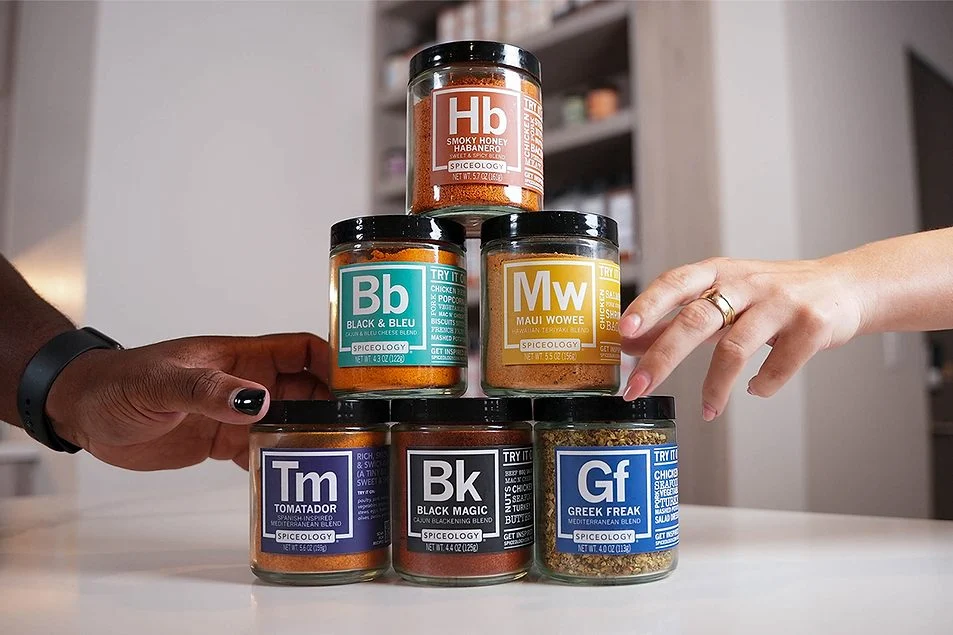
SPOKANE, WASH. — A core value of Spiceology, a spice blend manufacturer, is cooking and eating should be joyous experiences.

The company was founded in 2013 by Pete Taylor, an executive chef, and Heather Scholten, a food blogger, with the intention to liven up the spice category. Since its establishment, the company has introduced more than 300 spices and spice blends for both foodservice and retail.

The company prides itself on its commitment to creating fresh versatile blends. Each blend is formulated with whole spice that’s domestically sourced.

Spiceology manufactures its blends in small batches, leading to fresher products, McLean said.

Advertisement

However, with premium ingredients comes premium prices.

“We don’t use extracts or artificial flavoring; we don’t do any funky stuff,” McLean said. “Those things are more expensive to include, and yet we feel it’s absolutely worth it.”

The company’s commitment to premium coincides with its commitment to flavor innovation.

“We have an obsession with breaking spices and flavor out of application prison,” McLean said. “Spiceology’s products are, in addition to being innovative, they’re versatile.

Advertisement

“You might get something like Greek Freak and put it on your chicken, and it’ll be delicious and blow your mind, but you might think, ‘Oh, boy, what if I put that on my asparagus?’ or ‘I could rim a glass with this.’ If you really think about the blend, you could put a whole meal around it.”

McLean said the company is data driven, using trends to map out its next class of spices.

Additionally, Spiceology collaborates with its consumers to test an experimental flavor through its Test Kitchen program. The company shares a flavor it is considering launching and, if enough consumers pledge to purchase the spice once it’s launched, it gets added to the company’s portfolio.

“Test Kitchen is really a fantastic way for us to engage with our audiences, find what they’re liking,” McClean said. “It’s a really fun way for us to make sure that flavor enthusiasts and our biggest fans are also the ones deciding what’s coming out in the coming weeks ahead for Spiceology.”

Advertisement

The company’s mission to elevate the spice category comes at an apt time, as younger consumers are interested in elevating comfort meals with experimental flavors.

“Younger consumers don’t just want the tried-and-true flavors, they are curious about what different flavor profiles might mean,” McClean said. “They’re curious about ways they could spice up, for lack of a better term, the food they received at home as children. Spiceology meets them where they are with high-quality ingredients, ideas and a community with whom they can share ideas and recipes.”

Spiceology’s portfolio is distributed to foodservice providers nationally and may be found at select retailers. McLean said consumers can expect to see the company’s products expand into regional grocery stores in 2027. 

Continue Reading

Business

Rs 1.13 lakh crore boom in one corner, a bust in another: What changed in the AI trade?

Published

on

Rs 1.13 lakh crore boom in one corner, a bust in another: What changed in the AI trade?
Calls in the US to slow down artificial intelligence (AI) growth turned out to be a double-edged sword for investors on Dalal Street as the Nifty IT Index surged 5%, adding Rs 1.13 lakh crore in market value, even as stocks tied to the power and infrastructure buildout needed to support AI models fell as much as 6%.

The slowdown calls turned out to be good news for India’s battered software technology stocks as HCL Tech and Tech Mahindra gained 5% each while Infosys, LTIMindtree and Tata Consultancy Services (TCS) advanced 4%.

The move was exactly the opposite in the power play segment. TD Power slid 6% while Sterlite Technologies and GE Vernova T&D India lost 4%. HFCL, Hitachi Energy, CG Power and Siemens declined 2-3%.

The divergence reflects a rapid shift in investor positioning. Technology leaders, including representatives from Anthropic and OpenAI, have advocated industry-wide guardrails to address AI safety risks, prompting investors to rotate away from semiconductor manufacturers and other infrastructure beneficiaries and toward software companies.

Advertisement

Also Read | Infosys, HCLTech, TCS, other IT stocks soar up to 6%; Nifty IT rallies 5% as global AI slowdown calls boost sentiment


India’s IT stocks have been major laggards over the past year as new AI tools threatened the business models of traditional software services companies. But calls to slow the pace of frontier AI development are now offering the sector a potential reprieve, with investors betting that disruption may take longer to play out.
Analysts said when the narrative shifts from unchecked development to regulated and responsible use of AI, short-covering backed by fresh buying in frontline IT stocks is quite possible.The trigger was a call by Anthropic Chief Executive Officer Dario Amodei for AI companies to slow the pace at which they develop the technology. He called on Saturday for an industry-wide accord to “pace the frontier” and better control the breakneck progress of AI, citing the risk of attacks by swarms of AI agents going rogue.

“It’s my worry that in 6-12 months such a swarm could be capable of taking over the entire internet,” potentially causing hundreds of billions of dollars in damage, Amodei wrote in a 3,800-word post on his website.

His warning won support from OpenAI Chief Executive Officer Sam Altman and Elon Musk of xAI. The comments initially spooked markets, sending AI and other technology stocks lower and weighing on broader equity markets. But they also triggered a reassessment of the relative risks facing software companies and AI infrastructure providers.

Also Read | Fed hike, rising US Yields could trigger fresh selloff in Indian stocks

Advertisement

A more measured pace of frontier-model development could reduce concerns over rapid obsolescence and disruption for traditional software companies, while raising questions about the speed and scale of spending on chips, data centres, power and related infrastructure.

Valuations are giving investors another reason to revisit Indian IT stocks. The Nifty IT Index remains 37% below its record high and trades at about 16 times forward earnings—two standard deviations below its five-year average, according to data compiled by Bloomberg.

That depressed valuation leaves the sector more sensitive to any improvement in sentiment.

The implications for Indian IT could extend beyond short-covering. A more measured AI development cycle could give enterprises greater visibility on technology choices, reducing concerns around near-term obsolescence and encouraging customers that have adopted a wait-and-watch approach to resume technology spending, according to Choice Institutional Equities.

Advertisement

That would be incrementally positive for Indian IT companies involved in AI implementation, cloud transformation, governance and cybersecurity. It could also extend the monetisation window for technology vendors, giving them more time to offset productivity-led pressure on legacy services.

The structural risk remains that AI-driven productivity gains are passed on to clients, putting pressure on the pricing and revenue of traditional services companies. The key monitor, according to Choice, will be the pace of AI-led revenue creation relative to productivity-led deflation.

The market’s reassessment is also raising questions around the infrastructure commitments made in anticipation of accelerating AI demand. Anthropic is preparing for an imminent initial public offering to raise billions of dollars for development and massive data centres supporting its power-hungry models. Altman, meanwhile, has said OpenAI will not pursue an IPO this year, calling it “ill advised” amid the safety concerns.

The developments have revived investor worries over “circular investments,” in which AI companies invest in one another. Nvidia, the AI-chip behemoth, has been described as the “central bank of AI” for providing large amounts of infrastructure financing to companies around the world.

Advertisement

Companies have also committed to building their own power plants, supporting demand in so-called picks and shovels sectors such as construction and logistics.

The near-term direction of Indian IT stocks will also depend on the Federal Reserve. Markets are pricing in about a 90% probability of a 25-basis-point rate cut at the September 16 decision, according to Choice Institutional Equities. Fed guidance, US yields and inflation commentary will remain important drivers for Indian IT companies given their high exposure to North America.

(Disclaimer: This article has been written by Nikhil Agarwal, who is not a SEBI-registered Research Analyst or an Investment Adviser. Nikhil Agarwal and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here)

Advertisement
Continue Reading

Business

Kymera Therapeutics, Inc. (KYMR) Presents at Morgan Stanley 24th Annual Global Healthcare Conference Transcript

Published

on

OneWater Marine Inc. (ONEW) Q1 2026 Earnings Call Transcript