
Crypto World
Bitcoin ETFs have erased a $5.8 billion hole

Bitcoin investors have done it.
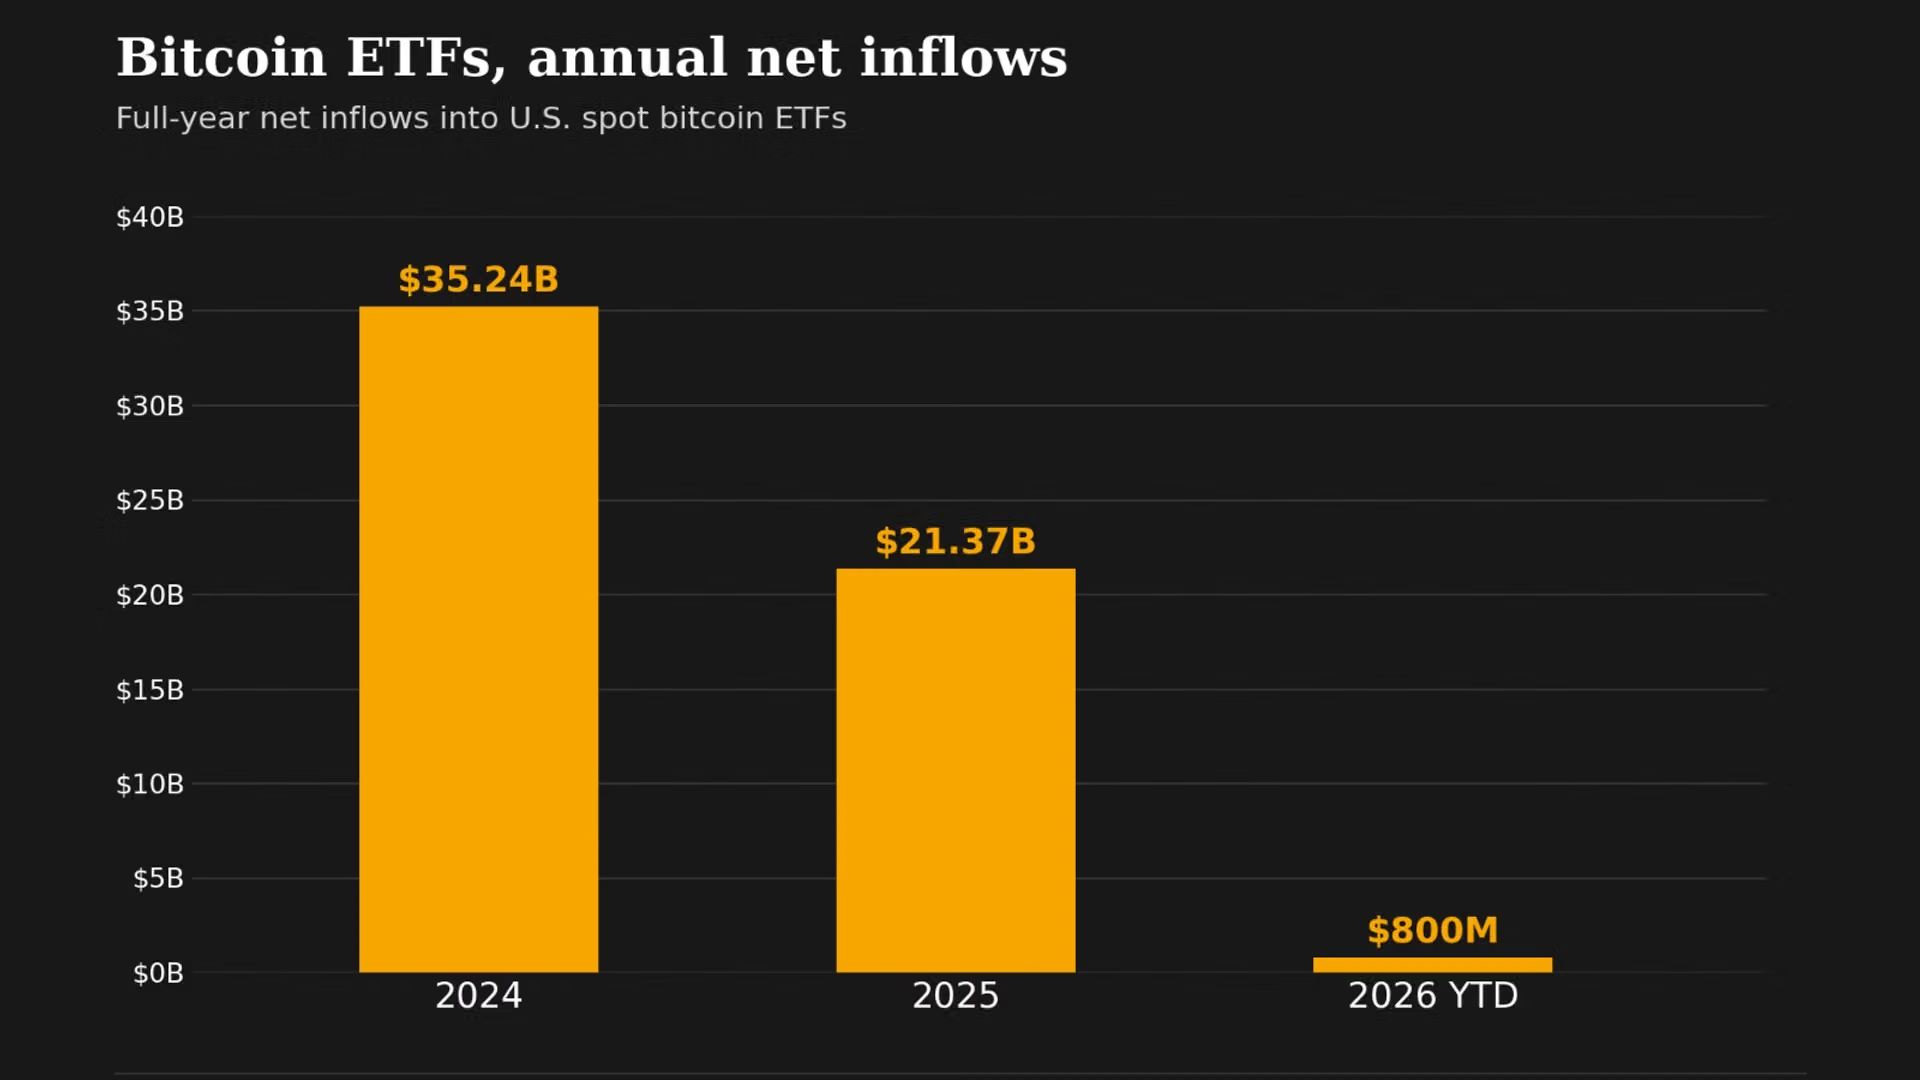
They’ve poured billions into U.S.-listed spot bitcoin exchange-traded funds (ETFs) in recent weeks. The result: these ETFs now sit on nearly $800 million in net inflows for the year, according to data source SoSoValue. That’s a 180-degree turn from the red ink earlier this year.
Here’s how bad it got. On July 13, the same ETFs were down $5.8 billion for the year. That was the low point, according to data analyzed by CoinDesk.
The turnaround lines up with bitcoin’s price recovery to $85,000 from under $58,000 in early June. That price rise, combined with the ETF inflows, has convinced some analysts a new bull run is already underway.
Nearly $4 billion of those inflows have come in since U.S. Treasury Secretary Scott Bessent’s August announcement of increased bond purchases, a liquidity management tool rolled out as bond yields surged to multi-year highs.
Still, there is much work to do for the bulls. At $800 million, net inflows for the year are still way smaller than $35.2 billion in 2024 and $21.4 billion in 2025.
Six-day winning streak
These ETFs have pulled in money for six straight days, even as bitcoin’s rally has stalled above $85,000 since Tuesday.

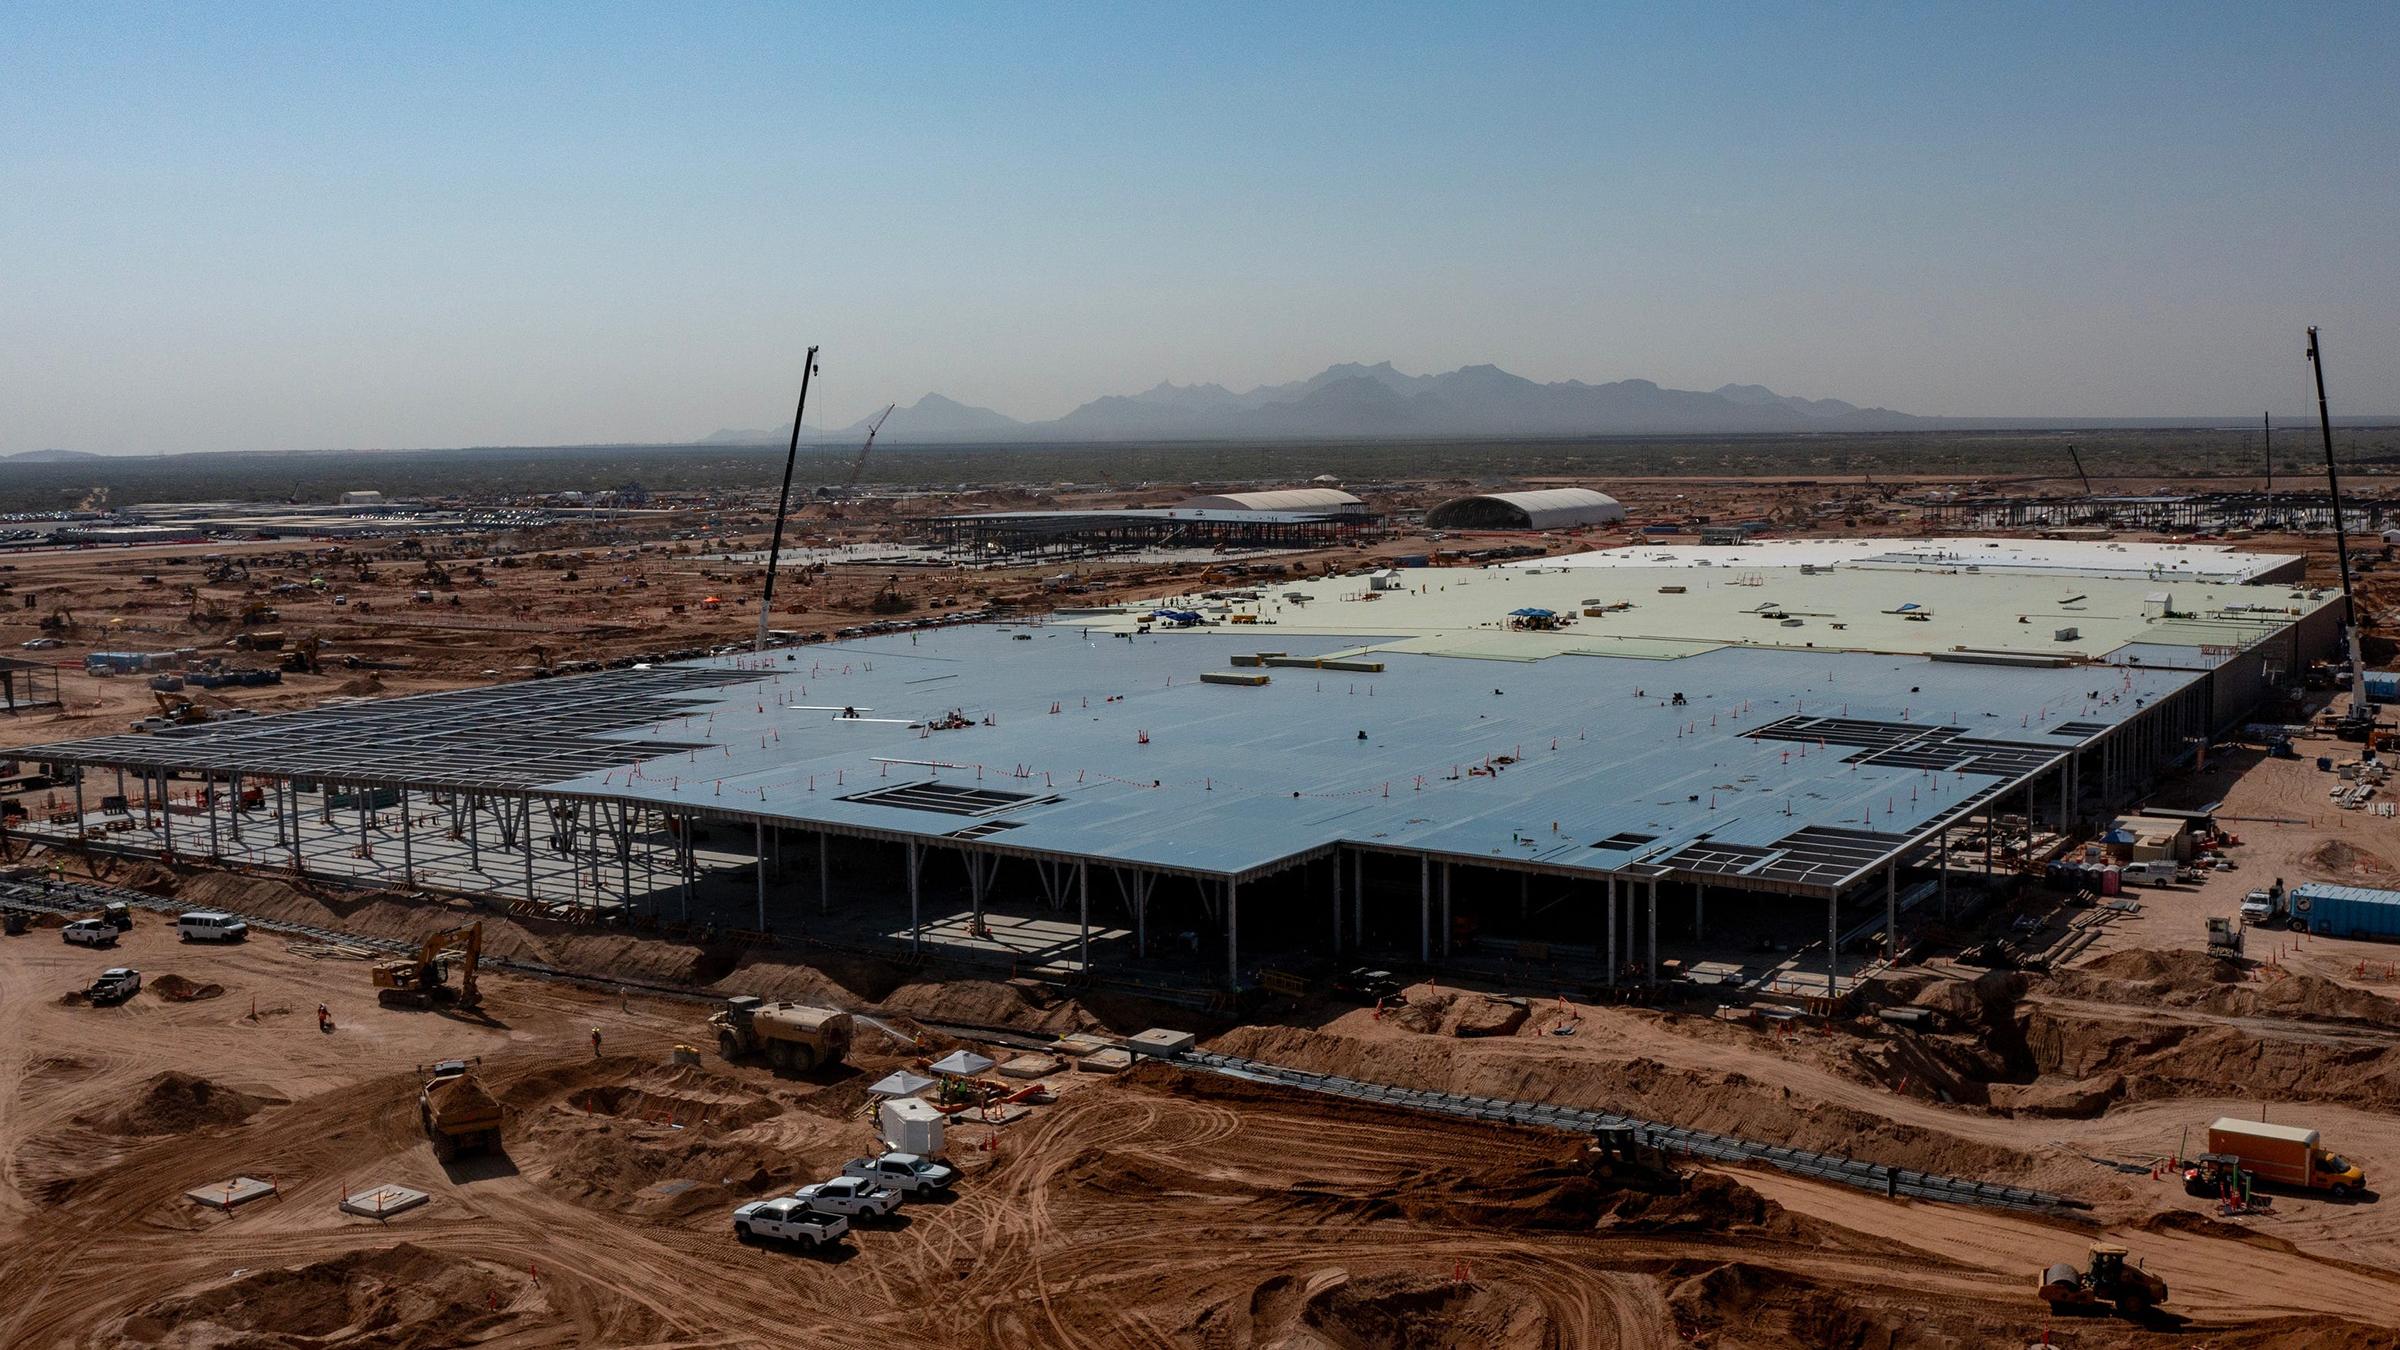
This debate also coincides with proposed changes to Section 106, a clause in the National Historic Preservation Act of 1966 that requires federal agencies to assess how development affects historic sites, which are decades in the making. If these changes are enacted, federal land, where Native Nations hold consultation rights under extant law, could theoretically become terrain AI data center developers could claim without a federal review process.
More than 700 organizations, including Native Nations, have already signed a letter opposing this change to Section 106—but this isn’t the first time it has been targeted.
Near the end of President Donald Trump’s first term, the Secretary of the Interior issued Secretarial Order 3389, exempting major energy and land-management projects from standard Section 106 review. It was a move the Biden administration noticed early on and swiftly reversed.
The current Advisory Council on Historic Preservation rewrite picks up where that order left off, and is part of energy, transmission, and mining’s long game to weaken Section 106 as a source of delay for infrastructure—one that predates the AI boom by years.
Samourai Wallet co-founder Keonne Rodriguez has said he faces another federal prison transfer after a drug-treatment program at FCI McKean was deactivated.
Summary
- Rodriguez says FCI McKean ended his treatment program, triggering another transfer with roughly seventy inmates.
- Completing the federal drug program could cut Rodriguez’s five-year sentence by up to twelve months.
- His previous transfer from Morgantown to McKean took thirty days despite a four-hour driving distance.
- DOJ says Samourai transmitted more than $237 million in criminal proceeds through its privacy services.
- Senate CLARITY legislation containing developer protections failed to advance on a 49–50 procedural vote September.
Rodriguez’s September 24 post on X says the prison warden informed program participants that he and roughly 70 other inmates would be transferred to facilities where the treatment remains available. The Federal Bureau of Prisons had not published a separate notice confirming McKean’s program shutdown at the time of reporting, so the transfer details come from Rodriguez’s account.
Why is Rodriguez facing another prison transfer?
Rodriguez entered the Residential Drug Abuse Program, or RDAP, because successful completion can reduce an eligible federal inmate’s sentence. The BOP explains that eligible participants may receive an early-release reduction after completing the residential treatment program.
For sentences of 37 months or longer, current BOP policy allows an early-release reduction of up to 12 months. Rodriguez is serving five years, making that maximum theoretically relevant if he satisfies the program’s eligibility and completion requirements. The reduction is not automatic because the BOP retains authority over eligibility and the amount granted.
Rodriguez said he had only recently settled into FCI McKean when inmates learned the treatment program would no longer continue there. His account says participants now expect reassignment to institutions that still offer RDAP.
An older BOP program-location guide listed a residential drug program at McKean, although the agency’s public materials reviewed for this report do not independently confirm the September 2026 deactivation Rodriguez described.
His last four-hour transfer took 30 days
The prospect of another move follows what Rodriguez described as a month-long transfer from FPC Morgantown in West Virginia to FCI McKean in Pennsylvania.
In a September 24 letter published by The Rage, Rodriguez said the facilities were approximately a four-hour drive apart. His transfer instead began June 10 and involved buses, two flights and a stop at the Federal Transfer Center in Oklahoma City.
Rodriguez said he requested permission to make the journey through a transfer furlough because he had minimum-security status and had self-surrendered to begin his sentence. He wrote that officials denied the request without explanation on June 8. Those descriptions are his personal account and have not been independently confirmed by the BOP.
During the transfer, Rodriguez said officers placed him in ankle restraints and handcuffs secured to a waist chain before taking him by bus to an airport. He described passing through detention facilities with inmates from different security classifications and spending long periods inside cells.
Rodriguez called the journey the “absolute worst 30 days” of his life. He wrote that he shared one cell with a man serving a murder sentence and described sleeping on part of a foam mattress while part of his body rested on the metal bunk.
The BOP says prison placement and transfers can depend on security classification, bed availability, program needs, medical requirements and other factors. Federal law directs the agency to consider housing inmates reasonably close to their primary residences when practicable, but programming needs can affect placement decisions.
Samourai case ended with five- and four-year sentences
Rodriguez is serving a five-year sentence after pleading guilty in August 2025 to conspiracy to operate an unlicensed money-transmitting business. Co-founder William Lonergan Hill received four years.
The U.S. Attorney’s Office for the Southern District of New York said Samourai transmitted more than $237 million in traceable criminal proceeds through its services. Prosecutors linked the funds to darknet markets, fraud, cybercrime, sanctioned jurisdictions and other offenses.
Samourai offered Whirlpool, which mixed Bitcoin transactions, and Ricochet, which inserted extra transaction hops between sending and receiving addresses. Prosecutors said more than 80,000 BTC, then valued above $2 billion, moved through the services after their launches.
Judge Denise Cote sentenced Rodriguez on November 6, 2025. The court imposed three years of supervised release after imprisonment and a $250,000 fine. Rodriguez and Hill paid approximately $6.37 million in forfeiture representing Samourai fees, according to the Justice Department.
As crypto.news previously reported, Rodriguez later sought public donations after saying legal expenses left him more than $2 million in debt. He said at the time that he was still seeking presidential clemency while preparing to begin his sentence.
Developer protections remain unresolved after CLARITY vote
Rodriguez’s case has continued to appear in U.S. debates over when developers of non-custodial crypto software can face money-transmission obligations.
The final Senate CLARITY Act text released September 14 contained provisions derived from the Blockchain Regulatory Certainty Act. Senator Cynthia Lummis’s office said the language would shield qualifying developers from money-transmission registration requirements and create a civil safe harbor.
As crypto.news previously reported, Coin Center had urged lawmakers to preserve protections for non-custodial blockchain developers. The advocacy group argued that software developers who never control customer assets should not automatically be treated as money transmitters.
The Senate did not advance H.R. 3633 on September 15. The official roll call shows the cloture motion failed 49–50, short of the three-fifths threshold required to proceed.
Lawmakers gave different reasons for opposing the measure. Republican Senator Susan Collins said the legislation required more study, including questions over community-bank deposits. Democratic senators including Catherine Cortez Masto and Angela Alsobrooks cited unresolved concerns over ethics, illicit-finance enforcement and other provisions.
The failed procedural vote left the proposed developer language unenacted. Rodriguez’s conviction and sentence remain governed by the law and judgment already entered in his criminal case.
For Rodriguez, the immediate issue is administrative rather than legislative. His latest account says the BOP must designate another institution where he can continue the treatment program tied to his potential sentence reduction. No destination or transfer date had been publicly disclosed when his September 24 update was published.
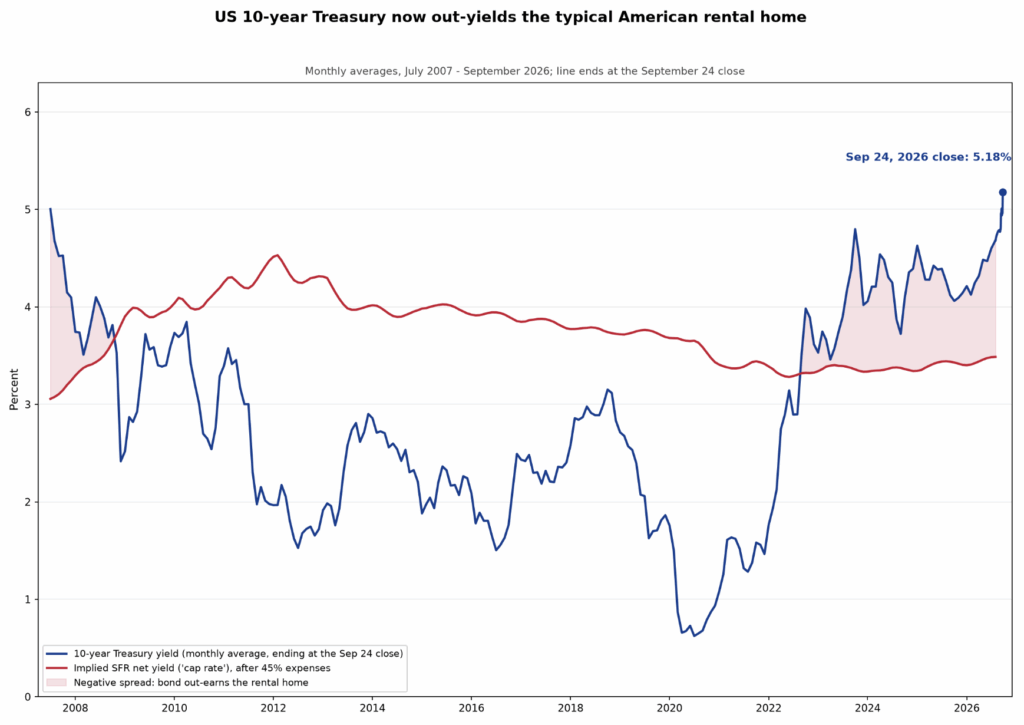
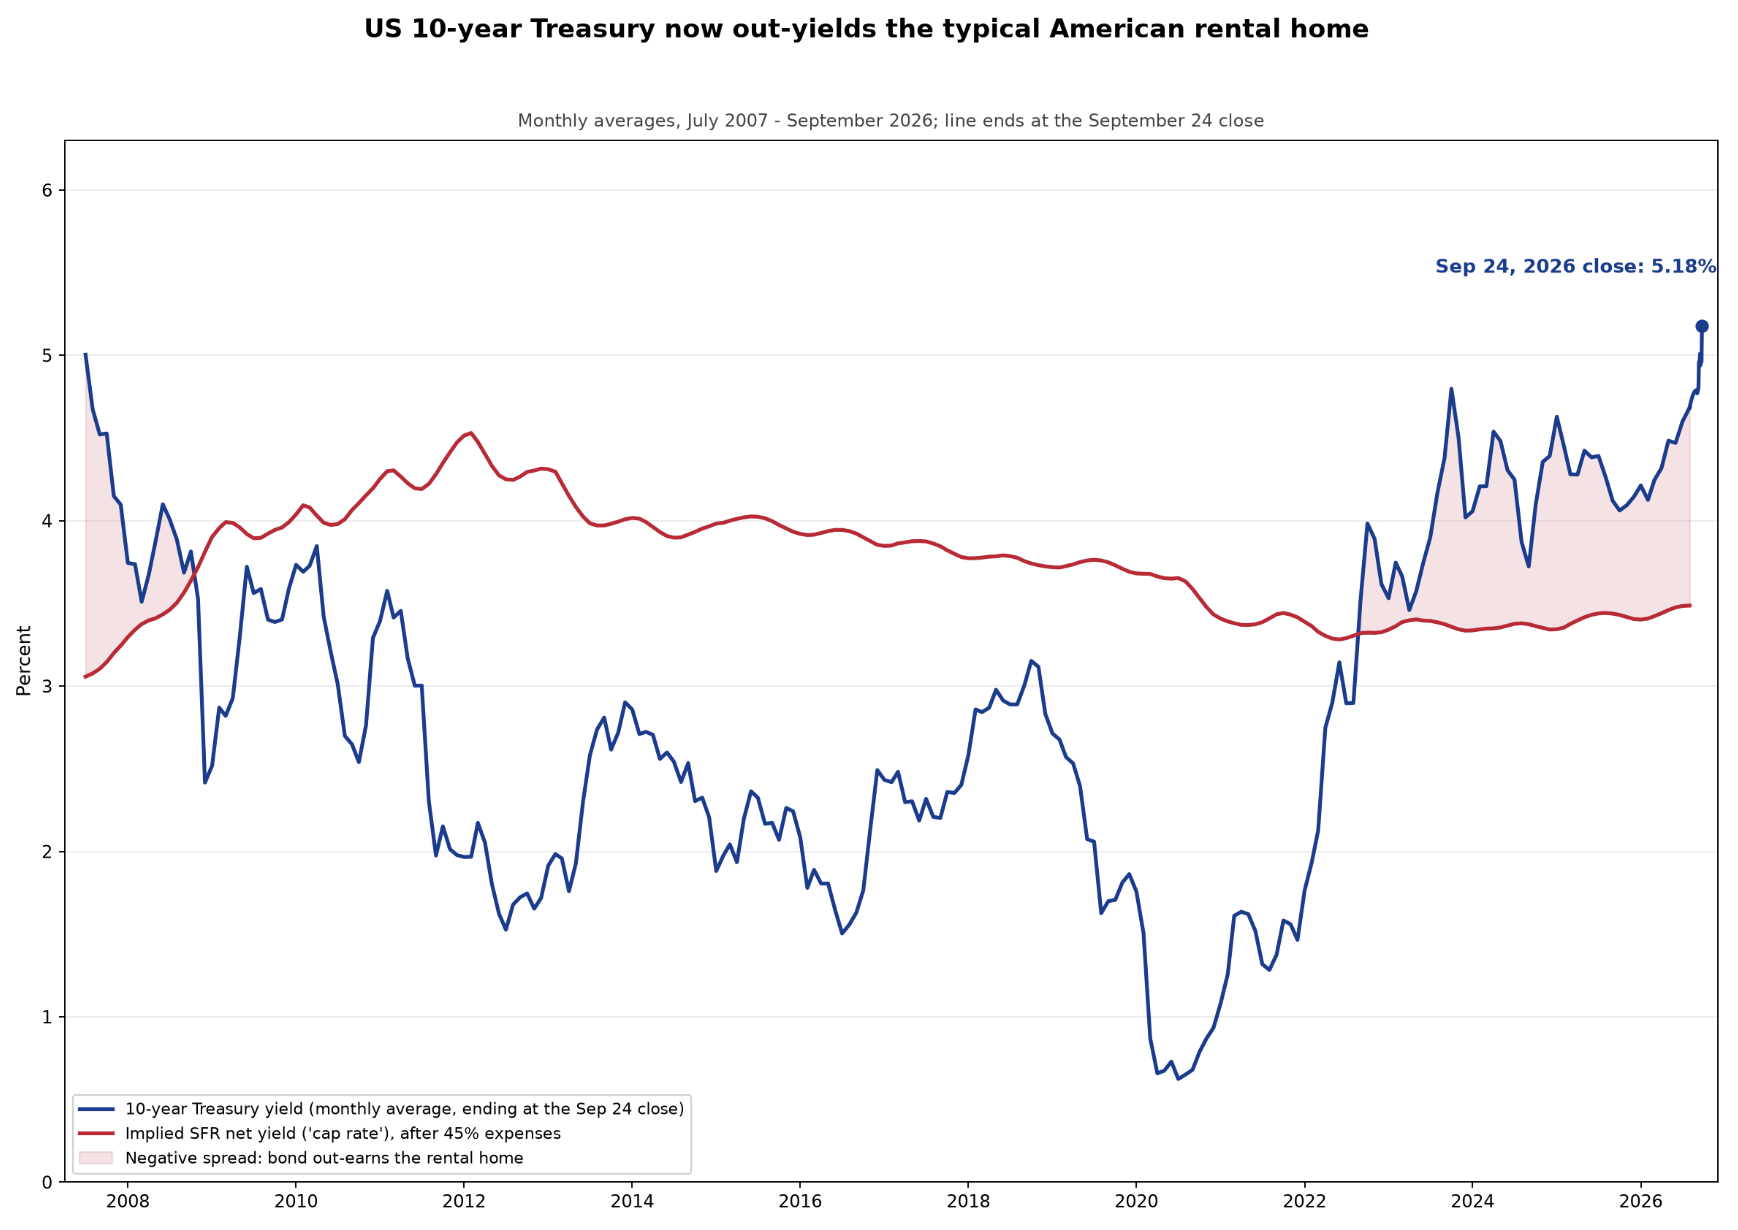
It would be more profitable for the average investor to buy a 10 year US government bond than to become a typical landlord. Indeed, this relative profitability is at its highest level since July 2007.
Negative housing spreads occur when the interest rate “spread” between low-risk US Treasuries are outperforming the risky operations of renting-out real estate.
Specifically, the US 10-year Treasury yield-to-maturity closed at 5.11% on Wednesday and pushed further to 5.18% on Thursday.
An oil shock and borrowing spree during the US war with Iran helped push Treasury bond yields to bizarre heights this year.
A recent rate hike from the Federal Reserve then catapulted yields past the 2007 housing bubble.
Last week, Chairman Kevin Warsh announced the Fed’s first hike in three years, and his committee’s own projections for an additional increase to their Fed Funds Rate this year.
Read more: US 20-year bond auction just had its worst showing ever
Negative housing spreads cause rental investment collapse
Nick Gerli, CEO of a real estate data firm, posted a chart drawing more than 250,000 views with a simple statement: Real estate for cash flow has a negative opportunity cost relative to government bonds.
According to his calculation, 10-year Treasuries above 5.1% easily beat the 4.8% single family house rental cap rate.
That 4.8% figure is one of many benchmarks for after-cost returns on rental properties. Individual property owners might earn double-digit returns during great years with minimal repairs, and then lose money the next year amid unexpected costs or low occupancy. Real estate returns vary drastically.
Got a tip? Send us an email securely via Protos Leaks. For more informed news and investigations, follow us on X, Bluesky, and Google News, or subscribe to our YouTube channel.
Yuga Labs’ 0xQuit said the NFTs are safe and will be returned once the risk passes, while holders were urged to revoke NFT permissions.
A single account for currencies, digital assets and commodities can simplify trading, but a tidy interface says little about what sits underneath.
Compare how each product is structured, priced, executed and governed – not the length of the instrument list.
Why crypto-native traders are looking beyond crypto
For traders used to crypto markets, adding currencies or gold can broaden the set of market drivers they follow. The scale is different too: the BIS 2025 Triennial Central Bank Survey recorded average OTC foreign-exchange turnover of $9.6 trillion per day in April 2025.
More markets do not automatically mean better diversification
Bitcoin, a technology-stock CFD and a high-beta currency may all fall when risk appetite fades. Diversification depends on correlations, position sizes and how those relationships change – not the number of symbols on screen.
Why product structure matters
“Buying gold” could mean owning a security, trading a futures contract or taking a leveraged CFD position. Crypto access might involve the underlying asset or a derivative with no wallet withdrawal. Before comparing forex and crypto trading, identify what is actually traded, who the counterparty is, how the position is margined and whether it expires or incurs overnight financing.
What “multi-asset trading platform” should mean in practice
Market access and instrument availability
Ask for the exact instrument schedule available in your country. “Stocks” may mean shares or CFDs, while “forex” may cover rolling spot-style products rather than futures. Compare trading hours, contract size, quote currency and what happens to orders when the underlying market is closed.
As crypto-native traders add currency and commodity exposure, providers increasingly compete on consolidated market access and risk tools. The 1xTrade trading platform is one example of this approach. As with any provider, traders should independently confirm which products are available in their jurisdiction and review the applicable costs, execution terms and legal disclosures before opening an account.
One interface versus one risk model
A unified online trading platform should show total margin use and exposure across asset classes. Test whether order tickets behave consistently, profit and loss are converted clearly into the account currency, and stops can be reviewed alongside exposure elsewhere.
Check 1: Execution and order handling
Why FX execution is different from a centralised exchange
Crypto traders may expect one visible order book, but retail OTC FX commonly involves dealer pricing. The BIS analysis of the 2025 FX execution landscape describes a decentralised, fragmented market in which spot and most FX derivatives trade over the counter; dealers internally match more than 80% of customer trades.
Ask how market orders, limits and stops are handled, whether slippage can be positive as well as negative, and what happens during gaps or connection failures. Evaluate execution quality using fill records, not a speed slogan or demo alone.
Check 2: Total trading costs
Spreads, commissions and overnight costs
Trading platform fees should be assessed for a realistic holding period. Add the bid–ask spread, commission, overnight financing or swap, currency-conversion charge and any market-data or inactivity fee. Then review deposit and withdrawal charges. A narrow headline spread may still produce a higher all-in cost for a position held for several days.
Check 3: Risk controls before leverage
Position sizing, stops and exposure limits
Leverage increases market exposure relative to deposited capital, amplifying losses as well as gains. A stop can constrain an intended exit but cannot guarantee its price in a fast or gapping market. Useful controls, therefore, include a pre-trade margin preview, position-size input, account-wide exposure view and clear liquidation rules.
Before placing an order:
- Set the maximum account loss for the trade in cash, not just percentage points.
- Calculate the size from the stop distance and contract value.
- Check the combined exposure of correlated positions.
Check 4: Funding and withdrawals
Read the operational terms before funding. Confirm supported currencies and rails, identity checks, minimums, fees, processing windows and whether withdrawals must use the original method. Test a small withdrawal early. “Processed” is not “received” when a bank, card network or blockchain adds another settlement step.
Check 5: Legal, jurisdictional and product disclosures
Trading platform due diligence starts with the exact contracting entity – not the brand name. Check that entity on the relevant regulator’s official register, then match its permissions to the product and your location. Corporate registration alone does not establish financial-services authorisation.
The CFTC’s retail forex advisory tells US customers to research OTC dealers before depositing, verify CFTC registration and review NFA disciplinary history. Wherever you live, read the client agreement, execution policy, risk disclosure, complaints route and rules on client-money protection before opening an account.
A practical multi-asset platform checklist
| Factor | What to verify | Why it matters |
| Market access | Exact products available in your jurisdiction | Familiar asset labels can hide different legal structures |
| Execution | Order types, pricing model, slippage and execution disclosures | Fills affect real cost and exit quality |
| Costs | Spread, commission, financing, conversion and withdrawal charges | Headline pricing rarely captures the full cost |
| Risk controls | Stops, sizing, margin rules and exposure tools | Small market moves can become large account moves |
| Legal status | Entity, jurisdiction, permissions and restrictions | The protections must match the actual provider and product |
| Withdrawals | Processing terms, verification and fees | Access to capital is part of platform usability |
Final thoughts: Convenience should not replace due diligence
The right trading platform 2026 is one whose products, costs and rules you can explain before committing capital. Apply the same checklist to every forex trading platform and crypto trading platform considered. A unified workflow matters only if it makes exposure, execution and obligations easier to see.
Disclosure: This content is provided by a third party. Neither crypto.news nor the author of this article endorses any product mentioned on this page. Users should conduct their own research before taking any action related to the company.
Samourai Wallet co-founder Keonne Rodriguez says he is facing yet another prison transfer after a drug treatment program at FCI McKean was deactivated, threatening the availability of the rehabilitation program he had been counting on to potentially shorten his sentence.
Rodriguez, who is serving a five-year federal term following a guilty plea tied to an alleged unlicensed money-transmitting business, said on X that McKean’s warden told program participants that Rodriguez and roughly 70 others would be moved to institutions where treatment would still be available. He entered the program because completing it could reduce his sentence by up to a year.
Key takeaways
- Keonne Rodriguez says FCI McKean shut down the drug treatment program he relied on for possible sentence reduction.
- Rodriguez claims McKean officials told program participants—him and about 70 others—that they would be transferred to facilities where treatment remains available.
- The transfer risk comes alongside broader U.S. legislative efforts to clarify whether non-custodial crypto developers should be treated as financial intermediaries.
- Congressional momentum for the CLARITY Act has stalled recently after a failed Senate effort to advance the bill.
Rehabilitation disruption at FCI McKean
Rodriguez said the most recent setback began when the program at FCI McKean was deactivated. He wrote that McKean’s warden informed the group that he and dozens of other participants would be moved to different federal facilities where treatment is still offered.
According to Rodriguez, his decision to enter the program was driven by the potential sentencing benefit: completing the treatment could, he said, reduce his term by as much as a year. With the program turned off at McKean, the practical question for him is whether the next facility will keep the promised pathway to sentence reduction within reach.
Earlier, Rodriguez described the movement between prisons as far more punishing than the distance might suggest. In a letter published by The Rage, he called the transition from FPC Morgantown to McKean the “absolute worst 30 days” of his life and said his request to make the roughly four-hour trip himself was denied.
From Morgantown to a “federal transfer” flow
Rodriguez’s account depicts a system built around transfers rather than continuity of routine. He said inmates leaving Morgantown were placed in ankle shackles and handcuffs attached to waist chains. He then described being taken by bus to an airport and flown to the Federal Transfer Center in Oklahoma City.
At the Federal Transfer Center, Rodriguez said he was housed with prisoners from different security classifications and spent much of his time locked in a cell. He described the experience in stark, prison-era language, saying he wondered whether “all the circles of hell” were contained within the federal transfer facility.
He also said that eventually he was assigned a cell with an inmate serving a murder sentence and that he was given only part of a foam mattress. Rodriguez stated that the setup left part of his body resting on a metal bunk overnight.
Rodriguez later faced another major procedural milestone: he is serving time after pleading guilty in a case involving Samourai Wallet’s operations. The U.S. Department of Justice said in a release that Rodriguez and co-founder William Lonergan Hill transmitted more than $237 million in criminal proceeds through the service.
Sentencing context and what Rodriguez claims is at stake
Rodriguez is currently serving a five-year sentence, and he has been vocal about conditions and the operational uncertainty that comes with prison transfers. The new claim about McKean’s treatment program matters because it directly affects whether he can stay enrolled in a structured course that, he says, could reduce his sentence.
His account also underscores a broader reality for incarcerated people: even when rehabilitation is available at one facility, a change in programming can force a relocation—sometimes on short notice—where eligibility and access may differ.
Rodriguez’s statements also echo a theme that has repeatedly appeared in federal criminal cases involving crypto: the practical consequences of how a defendant’s sentence interacts with institutional rules, program availability, and transfer logistics.
Legislative backdrop: developer protections still unresolved
The prison news arrives while lawmakers continue wrestling with how U.S. rules apply to crypto developers, particularly in situations where developers do not control users’ assets.
According to a recent report on the CLARITY Act, the latest Senate draft retained provisions intended to protect non-controlling developers from certain money-transmission requirements under the Bank Secrecy Act. However, the legislative effort has not advanced smoothly: Cointelegraph reported that the Senate failed to advance the CLARITY Act on Sept. 15 after a procedural vote fell short of the 60 votes needed to move the legislation forward.
That contrast—ongoing legal uncertainty for developers in Washington alongside Rodriguez’s real-world account of how institutions can change course—highlights a persistent issue for the industry: while policy debates continue, compliance expectations remain uneven, and the consequences can extend well beyond code and into enforcement and sentencing.
The CLARITY Act’s stalled progress means that questions about regulatory treatment—especially around whether certain developer behaviors could be interpreted as financial intermediation—remain unresolved for the moment. Even if the bill’s drafting language includes protective measures, the key uncertainty for builders and users is whether legislation will actually move, and how any final framework would be applied.
For Rodriguez, the immediate thing to watch is whether his next facility preserves access to the treatment program he says could reduce his sentence. More broadly, industry readers should monitor how the CLARITY Act debate evolves in the Senate, because the outcome will shape how investors, developers, and compliance teams plan for what the law requires.

Key takeaways
- Uniswap retreated after climbing to an intraweek high of approximately $10.95.
- UNI’s weekly RSI has entered overbought territory at around 73.
- A correction could target $7.83, while losing that support may expose $6.91.
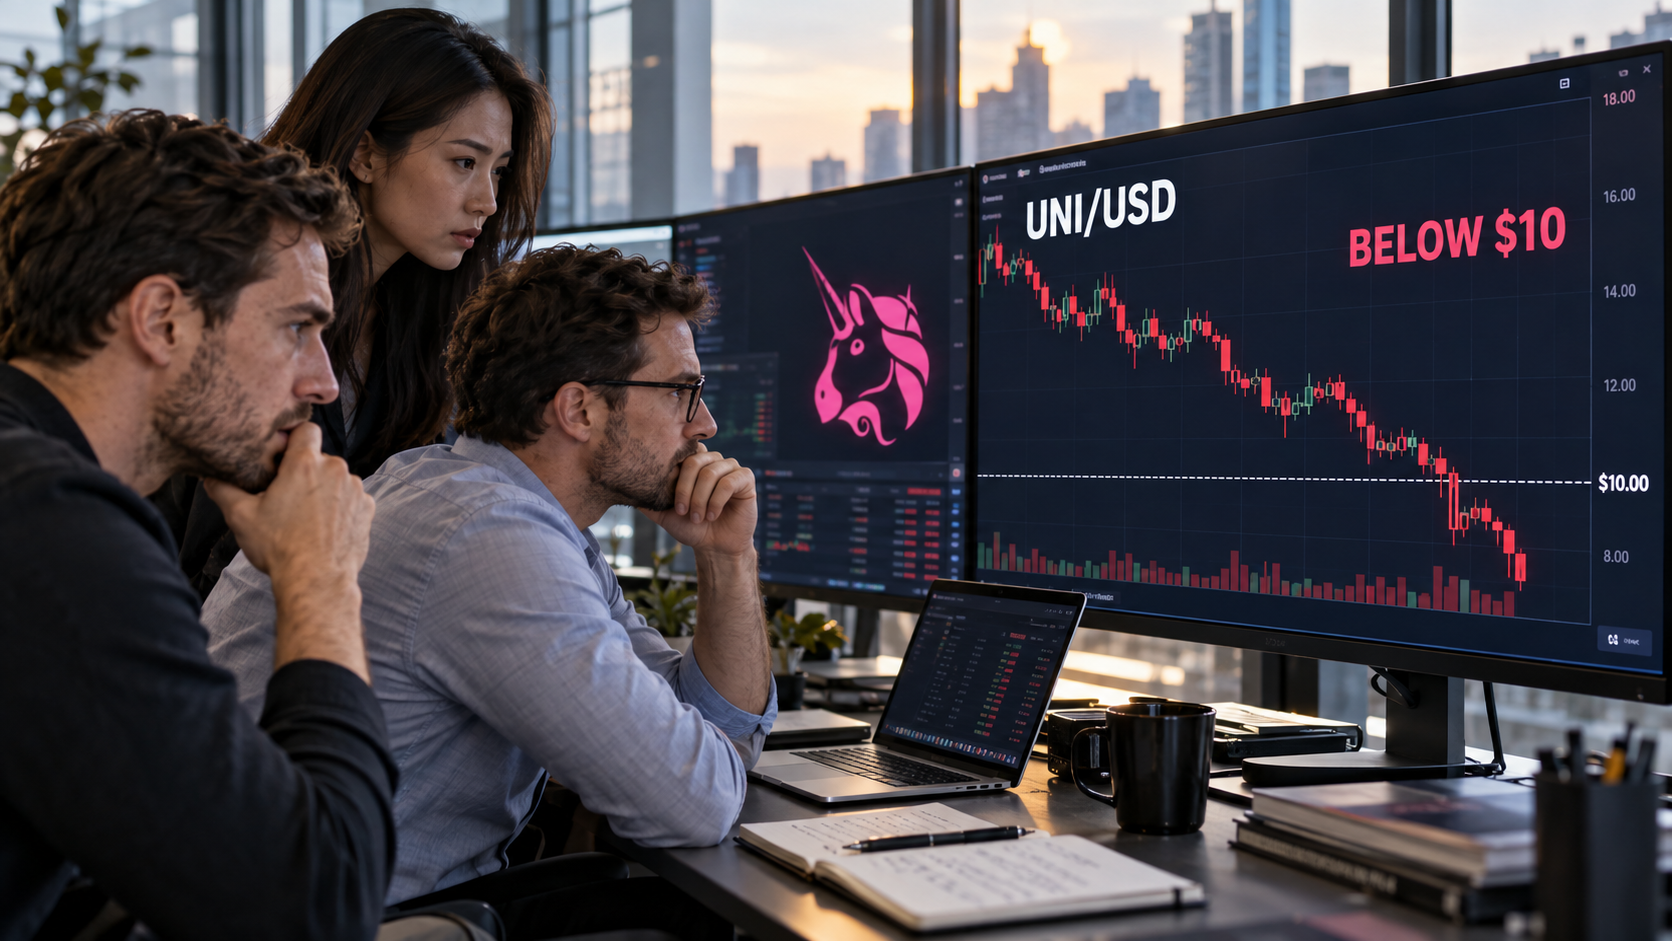
Uniswap (UNI) could decline toward $7.80 over the coming weeks after its latest rally lost momentum near a major resistance area.
An overbought weekly Relative Strength Index (RSI), a rejection below the $11.51 Fibonacci level and a concentration of leveraged long positions below the market all point to an elevated risk of a correction.
UNI traded near $9.11 on September 25 after reaching an intraweek high of roughly $10.95. Although its longer-term technical structure has improved, the token may need to cool further before attempting another sustained advance.
UNI Rally Loses Momentum Below $11.50
Uniswap’s recent rebound brought the price close to the 0.786 Fibonacci retracement level at approximately $11.51. That area represented an important upside target following UNI’s breakout above a long-term descending resistance trendline.
However, the token failed to reach or break the level convincingly. Sellers emerged around $10.95, pushing the price back toward $9.11 and leaving a substantial upper wick on the developing weekly candle.
A long upper wick typically signals that buyers drove the price higher during the period but could not hold those gains. While this pattern does not guarantee a reversal, it indicates that selling pressure has increased near the recent high.
The rejection is especially relevant because it occurred close to major Fibonacci resistance. Unless UNI can reclaim the $10.95-$11.51 region, traders may treat the latest move as an unsuccessful breakout attempt rather than the beginning of another sustained rally.
Overbought RSI raises correction risk
Momentum indicators also suggest that Uniswap’s advance may be becoming stretched. UNI’s weekly RSI has risen to around 73, placing it above the traditional overbought threshold of 70.
An overbought RSI does not automatically mean that a sell-off is imminent. During strong trends, cryptocurrencies can remain overbought for extended periods while prices continue rising. Nevertheless, UNI’s previous sharp weekly rallies have frequently been followed by consolidation or multi-week corrections as traders lock in profits.
The combination of an elevated RSI, resistance near $11.51, and the recent upper wick strengthens the possibility of a short-term pullback.
The first major technical target on the downside is the 200-week exponential moving average at approximately $7.83. A decline from $9.21 to that level would represent a correction of about 15%.
If buyers defend the $7.80-$7.85 area, UNI could establish a higher low and prepare for another attempt at $11.50. Losing that support, however, would expose the 100-week EMA near $6.91.
Despite these near-term risks, Uniswap’s broader chart remains healthier than it was earlier in the year. UNI is still trading above several important weekly moving averages and has broken through a long-term descending resistance line. A pullback to $7.83 could therefore function as a retest of support rather than the start of a larger bearish reversal.
Derivatives positioning creates an additional source of downside pressure. CoinGlass data shows a significant cluster of leveraged long positions around $8.87 on Binance’s UNI/USDT market.
Approximately $5.16 million in liquidation leverage is concentrated near that price. If UNI falls toward $8.87, the move could expose an estimated $10.35 million in cumulative long liquidations.
When a leveraged long position is liquidated, the exchange closes it automatically by selling the underlying exposure. If many positions are forced to close in a short period, that selling can accelerate the decline and trigger further liquidations at lower prices.
This dynamic makes $8.87 a potential liquidity magnet. A modest pullback toward that level could develop into a sharper move if forced selling overwhelms available demand.
The liquidation heatmap also identifies short-position liquidity above the current market, meaning that an unexpected rally could still generate a short squeeze. However, the larger concentration of vulnerable longs immediately below the price makes the downside risk more pressing in the near term.

Can UNI recover toward $11.50?
Uniswap’s next move may depend on whether buyers can protect the $8.87 liquidity zone and the stronger technical support around $7.83.
A successful defense of these levels would preserve the improving weekly structure and leave UNI positioned for another test of $11.50. A decisive weekly close above that resistance would weaken the correction scenario and could open the door to higher targets.
Conversely, a liquidation-driven decline below $8.87 would increase the probability of a move toward the 200-week EMA at $7.83. If that floor also breaks, the 100-week EMA near $6.91 would become the next significant downside level.
For now, UNI’s longer-term recovery remains intact, but overbought momentum and crowded leveraged positioning suggest that volatility—and potentially a 15% correction—could come first.
According to Bloomberg, the Trump administration is weighing an initiative aimed at encouraging the use of dollar-backed stablecoins outside the United States, framing the push as a way to strengthen the dollar’s role as the world’s reserve currency.
The report, citing people familiar with the plans, says the US government could support stablecoin projects by partnering through joint ventures with private-sector firms. The effort could involve multiple agencies, including the Treasury Department, the State Department, and the US International Development Finance Corporation (DFC). Bloomberg reported the details on Wednesday.
Key takeaways
- Bloomberg reports a potential US government initiative to promote overseas adoption of dollar-backed stablecoins.
- The proposed approach would reportedly rely on joint ventures with private-sector firms, potentially involving multiple federal agencies.
- US officials have repeatedly tied stablecoin expansion to strengthening dollar dominance and increasing demand for US Treasurys.
- The plan arrives as other regions accelerate digital infrastructure work, including CBDC pilots and cross-border payment platforms.
Why stablecoins are part of US dollar strategy
The reported initiative highlights a broader policy theme: dollar-backed stablecoins are increasingly viewed by senior US officials not only as financial technology, but also as infrastructure that can reinforce the dollar’s global settlement role.
In February 2025, venture capitalist David Sacks—who at the time served as the White House crypto and AI czar—argued that stablecoins could “extend the dollar’s dominance internationally,” and potentially “generate trillions of dollars” in additional demand for US government debt. Earlier Cointelegraph coverage connected these claims to the administration’s stance on stablecoin regulation and the dollar economy. Earlier coverage from Cointelegraph noted how officials framed the relationship between stablecoin growth and US Treasury demand.
That linkage has also appeared in subsequent statements by Treasury leadership. In July 2025, US Treasury Secretary Scott Bessent said the GENIUS Act—legislation that created a federal regulatory framework for payment stablecoins—could strengthen the dollar’s status as a reserve currency, broaden access to the dollar economy, and increase demand for US Treasurys. Cointelegraph previously reported on this framing, including the argument that stablecoin rules are designed to “cement” US dollar prominence. Cointelegraph’s analysis also highlighted concerns that the rules’ treatment of foreign issuers remained unclear.
GENIUS implementation continues as the government considers a wider push
While the overseas initiative is still at the consideration stage, the administration’s domestic stablecoin work has continued in parallel. The Treasury Department has been moving forward with implementation of the GENIUS Act, including rulemaking focused on how payment stablecoins can be issued, offered, and sold.
On Aug. 17, the Treasury issued a notice of proposed rulemaking seeking public comment on provisions that would govern issuance, offering, and sale of payment stablecoins. Cointelegraph reported on the move, and the reporting noted Bessent’s comments that the rules would help “cement” the US dollar’s status as the world’s reserve currency.
For investors and market participants, that matters because overseas adoption would likely require a predictable compliance framework—especially for the kinds of projects that would be eligible for public-private support. A government-linked push could also change competitive dynamics abroad by accelerating distribution partnerships and expanding the set of jurisdictions where dollar stablecoins can be used for settlement and retail payments.
Global competition: CBDCs and cross-border pilots advance elsewhere
The potential US push for dollar-backed stablecoins comes amid rapid movement in other parts of the world to modernize payments, including central bank digital currency efforts and cross-border experimentation.
Cointelegraph noted that China’s digital yuan is used in Project mBridge, a platform designed for cross-border CBDC transactions. Earlier coverage from Cointelegraph described how participating institutions have treated mBridge as a practical sandbox for multinational settlement use cases.
In Europe, the European Central Bank is preparing a 12-month digital euro pilot expected to begin in the second half of 2027, according to Cointelegraph. That reporting underscored how the euro area is building a timeline for experimentation with a digital euro that could eventually influence cross-border payments and merchant settlement preferences.
Against that backdrop, a US initiative promoting dollar stablecoins overseas would be entering a competitive environment where governments are exploring multiple settlement rails—CBDCs, tokenized assets, and stablecoin-based payment networks. The key uncertainty is whether the US will prioritize stablecoin issuance and compliance standards, partnerships and distribution, or targeted support for specific cross-border use cases.
What remains unclear—and what to watch next
Bloomberg’s report suggests the US government could use joint ventures with private-sector firms to help drive adoption of dollar-backed stablecoins internationally, with Treasury, State, and the DFC among the agencies that may be involved. However, details on how such arrangements would be structured, which jurisdictions would be targeted, and what regulatory constraints would apply are not provided in the available reporting.
Cointelegraph said it reached out to the US Treasury, the DFC, and several US-based stablecoin companies for comment but did not receive a response before publication.
Readers should watch for follow-on disclosures—especially any indication of which stablecoin activities could receive support, how the initiative would interact with GENIUS implementation, and whether the administration’s goal of increasing US Treasury demand translates into specific, measurable policy outcomes.
KelpDAO filed a lawsuit against LayerZero and its co-founder, blaming the universal bridge protocol for the largest exploit of this year, which drained $292 million and triggered one of the largest DeFi runs in crypto history, according to a post on X on Thursday.
“The exploit was a direct result of LayerZero’s failures, including a failure to disclose weaknesses and risks inherent in LayerZero’s own technology,” KelpDAO said.
KelpDAO, a decentralized liquid staking protocol on Ethereum, also accused LayerZero of failing to prevent infiltration of its security infrastructure, claiming that this allowed attackers to exploit the universal bridge’s alleged weaknesses.
“Rather than take responsibility, over the last few months, LayerZero and Mr. Pellegrino publicly blamed us for their failures,” KelpDAO said.
Pellegrino immediately responded that he would see them in a Canadian court.
“Evercrest (KelpDAO) filed a notice of civil claim today in BC (British Columbia, Canada) against myself and LZ (LayerZero),” Pellegrino said. “The claim continues to be meritless. I will meet them in Vancouver and defend myself accordingly.”
KelpDAO has filed a lawsuit against cross-chain protocol LayerZero following the roughly $292 million exploit of its rsETH bridge earlier this year, alleging that failures in LayerZero’s security infrastructure contributed to the attack.
KelpDAO said Friday that LayerZero failed to disclose risks in its technology or prevent attackers from compromising its infrastructure. It also alleged that LayerZero had reviewed and endorsed its deployment and configuration in writing before the exploit.
The lawsuit also names LayerZero co-founder and CEO Bryan Pellegrino.
“Our number one priority has always been and will remain the security of our users’ assets,” Kelp wrote. “But we also need to correct the record, and hold LayerZero and Mr. Pellegrino accountable for the harm they have caused us and the broader DeFi ecosystem.”
Pellegrino called the claim “meritless” and said he would defend the case in Vancouver.
The lawsuit escalates a months-long dispute over whether the loss was caused by the compromise of LayerZero’s infrastructure, KelpDAO’s bridge configuration, or both.
Cointelegraph contacted LayerZero for further comment, but did not receive a response before publication.
Kelp and LayerZero have disputed responsibility since April
The April 18 attack resulted in the theft of 116,500 rsETH, worth about $292 million at the time, from Kelp’s LayerZero-powered bridge.
In its final incident report, LayerZero said attackers compromised its internal nodes and caused its verifier to approve a forged cross-chain message. It argued that the loss was possible because Kelp’s bridge relied on a single LayerZero decentralized verifier network (DVN) as its only verification path.
Related: Recovery hopes fade as Kelp DAO hacker launders nearly all $220M in stolen funds
With no second independent verifier required, the bridge released the rsETH after receiving LayerZero’s verifier approved the forged message. LayerZero said it had recommended using multiple DVNs and subsequently stopped acting as the sole required verifier for applications.
Kelp has disputed LayerZero’s account of responsibility. In May, it said its DVN configuration had previously been discussed with LayerZero and “confirmed as secure,” while accusing LayerZero of failing to adequately warn it about the risks. Kelp subsequently announced plans to migrate the rsETH bridge to Chainlink’s Cross-Chain Interoperability Protocol.
Magazine: Winners and losers of the SEC’s new tokenized stocks rules

Packers booed by own fans during loss to Falcons

New Carbonato malware uses AI agents to hijack exposed Docker hosts

BITCOIN WILL NOT WAIT FOR YOU




-

 Fashion7 days ago
Weekend Open Thread: Talbots – Corporette.com
-

 Crypto World2 days ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-

 Tech4 days ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Fashion23 hours ago
8 iPhone Accessories That Add Personality
-

 Crypto World4 days ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-

 Crypto World6 days ago
Circle launches Arc Studio AI agent for building onchain apps
-
 NewsBeat6 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World6 days ago
Trading Bitcoin on Robinhood? Why 2% Spread Has Traders Worried
-

 Tech6 days ago
Trump suggests rebranding AI with a new name, says he’s also creating an AI Force
-

 Crypto World6 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Business4 days ago
Analog Devices (ADI) Bets $1.35 Billion on Chips that Let Machines Think for Themselves
-

 Tech4 days ago
Google’s $899 Googlebook is a bet that you’ll buy a new laptop for Gemini
-

 Crypto World4 days ago
Coinbase, Robinhood, Circle Seen as Tokenized-Stock Winners
-

 Crypto World2 days ago
This Bearish Netflix Stock Trade Can Cash In On Video Streaming Giant’s Woes
-
 Business2 days ago
Oil Price Today (September 23): Crude oil below $100 on hopes of US-Iran talks. What did Trump say?
-

 Crypto World3 days ago
Trump-Xi Polymarket Odds for Handshake Hit 50%
-

 Crypto World1 day ago
Crude Oil Prices Pressured by Diplomatic Hopes in the Middle East
-

 Crypto World6 days ago
World Money launches in 150+ countries with Stripe
-

 Entertainment2 days ago
These 17 Fall Amazon Dresses Seriously Look Like Anthropologie
-

 Crypto World7 days ago
Silver prices recover quickly, hitting weekly high today
You must be logged in to post a comment Login